Key takeaways
- The CRS, approved by the OECD Council on July 15, 2014, requires financial institutions in participating jurisdictions to report the name, address, tax residence, taxpayer identification number, account balance, and income of accounts held by foreign tax residents, and tax authorities exchange that data once a year (OECD, Standard for Automatic Exchange of Financial Account Information in Tax Matters).
- Information on more than 134 million financial accounts, holding almost €12 trillion in assets, was exchanged automatically in 2023 (Global Forum, Peer Review of the Automatic Exchange of Financial Account Information 2024 Update).
- There is no minimum balance for individual accounts: a forgotten savings account with a few hundred euros is reportable, preexisting individual accounts above $1 million get enhanced review, and only preexisting entity accounts may benefit from an optional $250,000 threshold (OECD Standard, Sections III and V).
- The CRS turns on tax residence, not citizenship, and it looks through passive entities: for a trust, the settlor, trustees, any protector, and the beneficiaries are all reported as controlling persons (OECD Standard, Section VIII).
- The United States has never joined the CRS, and a 2020 study in the Journal of Public Economics found that the standard cut cross-border deposits in tax havens by about 11.5% while deposits in the United States rose (Casi, Spengel and Stage, 2020).
- Real estate remains largely outside automatic exchange: the OECD's framework for exchanging information on foreign-held property had pledges from 26 jurisdictions as of December 2025 (OECD, December 2025), and the United States is scheduled to begin crypto-asset exchanges under the CARF only by 2029, later than the 2027 first wave.
What happened in the thirty years before the Standard?
The idea that tax authorities should share information with one another is as old as tax treaties themselves. But for decades, cooperation rested on a single mechanism, exchange "on request": one country's tax agency, suspecting a taxpayer, sends a reasoned inquiry to its foreign counterpart. The flaw is obvious. To ask, you already have to know: the taxpayer's name, the bank, ideally the account. Tax evasion consists precisely of making sure the government knows nothing. And many financial centers answered such requests by invoking banking secrecy, in some cases backed by criminal penalties.
The OECD took up the issue in 1998 with its report on "harmful tax competition," followed in 2000 by a list of tax havens, both described in the OECD's 2000 report Towards Global Tax Co-operation. The offensive bogged down, particularly after the Bush administration withdrew U.S. support in 2001. What came out of it was a model information exchange agreement in 2002 and, in 2005, a rewrite of Article 26 of the OECD's model tax treaty establishing that a country cannot cite banking secrecy as grounds for refusing a request. On paper, that was progress. In practice, Switzerland, Luxembourg, Austria, and Belgium entered reservations, and nothing changed.
The European Union, for its part, tried something more ambitious. The Savings Directive of 2003, in force from July 2005, created automatic exchange for the first time: banks would report interest paid to residents of other member states. But the political compromise that made it possible gutted much of its substance. Austria, Belgium, and Luxembourg won the right to substitute an anonymous withholding tax, as did Switzerland under a parallel agreement. Worse, the directive covered only interest and only individuals. Shift a bond portfolio into stocks, or drop a Panamanian company or a Liechtenstein foundation between yourself and the account, and you were out of scope. Private bankers did it for their clients in a matter of weeks. The Savings Directive endures as a textbook case: a good idea ruined by its exceptions.
How did the 2008-2009 crisis shift the balance of power?
It took two scandals and a financial crisis to break the logjam. The UBS and LGT affairs in 2008 exposed the industrial scale of evasion run out of Switzerland and Liechtenstein. At the same time, governments that had just bailed out their banks at enormous cost were looking for revenue and for someone to blame. On April 2, 2009, the G20 leaders meeting in London declared in their communiqué that the era of banking secrecy was over, as recorded in the Global Forum's own history of the period. The same day, the OECD published a gray list of uncooperative jurisdictions. The way off the list: sign 12 information exchange agreements.
The result looked spectacular. Within months, every holdout dropped its reservations on Article 26, and hundreds of agreements were signed. The Global Forum on Transparency and Exchange of Information for Tax Purposes, restructured in Mexico City in September 2009 and opened to all countries, launched peer reviews. But the standard was still exchange on request, and some havens signed their 12 agreements with one another, or with Greenland and the Faroe Islands. Economists Niels Johannesen and Gabriel Zucman would show in 2014 that this wave of treaties mostly shifted deposits from havens that signed to havens that hadn't, with no meaningful repatriation (Johannesen and Zucman, "The End of Bank Secrecy? An Evaluation of the G20 Tax Haven Crackdown," American Economic Journal: Economic Policy, 2014).
Switzerland, sensing the wind changing, floated a counter-model: the "Rubik" agreements, under which its banks would levy a final withholding tax on foreign clients' assets and remit it to their home countries without ever revealing who they were. The United Kingdom and Austria signed on. But Germany's upper house, the Bundesrat, rejected its agreement in late 2012, and Rubik died with it. Anonymity in exchange for cash: the offer came too late.
What was the American detonator?
Because in the meantime, Washington had changed everything. By enacting FATCA in March 2010, the United States unilaterally required banks around the world to report their American clients or face a punitive 30% withholding tax on their U.S.-source income. For European governments, the position became politically untenable: how do you explain to voters that your banks automatically hand the IRS what they refuse to give their own tax authority, or the one next door?
On February 8, 2012, France, Germany, Italy, Spain, and the United Kingdom issued a joint statement with the United States on implementing FATCA through intergovernmental agreements. This "G5" immediately announced its intention to use those agreements as the template for a multilateral standard. A most-favored-nation clause in the EU's directive on administrative cooperation finished the job: having agreed to give to the Americans, Luxembourg and Austria could no longer legally refuse their fellow Europeans. In April 2013, Luxembourg, then led by Jean-Claude Juncker, announced it would give up banking secrecy for nonresidents. The European lock had been picked.
From there, things moved fast, at least by diplomatic standards. In April 2013, G20 finance ministers endorsed automatic exchange as the future global standard. The G8 summit at Lough Erne in June, then the G20 in St. Petersburg in September, confirmed the goal and handed the OECD the mandate. At the organization's tax policy center, run by Frenchman Pascal Saint-Amans, the staff built deliberately on FATCA's Model 1 agreement: banks had already spent billions complying with it, and a standard that reused the same plumbing would be that much easier to accept. The Common Reporting Standard was unveiled in February 2014 and endorsed by G20 finance ministers in Sydney, as recited in the preamble of Council Directive 2014/107/EU. The full text, with commentary, was approved by the OECD Council on July 15, 2014, according to the OECD's published Standard.
On October 29, 2014, in Berlin, 51 jurisdictions signed the multilateral agreement that brought it to life, as recorded in the States of Jersey ratification proposition for the MCAA. Among them: Liechtenstein, Luxembourg, the Cayman Islands, Jersey. Switzerland signed a few weeks later, on November 19, 2014 (Swiss Federal Council press release). Five years had passed since the London G20 declaration. Four since FATCA.
What are the three layers of the legal architecture?
The CRS is not a treaty. It is a standard, meaning a set of model rules that each jurisdiction must write into its own law to bind its financial institutions. Its international legal force comes from elsewhere, from a layered structure worth describing precisely.
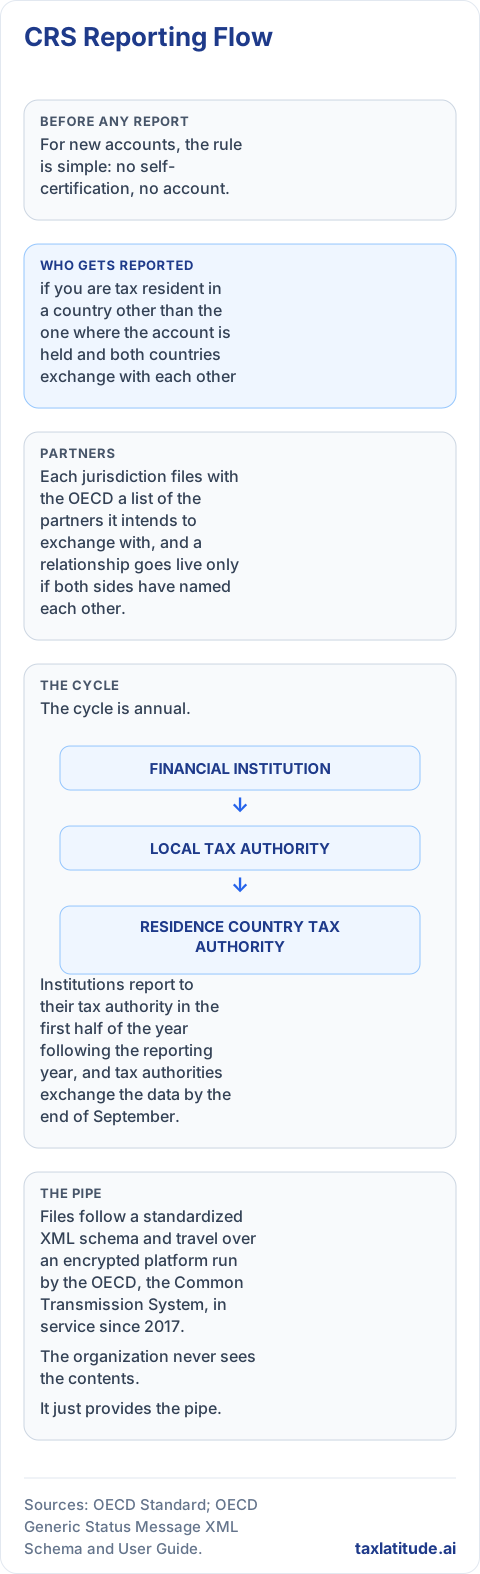
The foundation is the Convention on Mutual Administrative Assistance in Tax Matters, drafted by the OECD and the Council of Europe in 1988, amended in 2010, and opened to all countries the following year. Its Article 6 permits automatic exchange between parties that agree to it. The second layer is the Multilateral Competent Authority Agreement (MCAA), the document signed in Berlin, which spells out what is exchanged, when, and how. The third layer holds an important subtlety: the agreement is multilateral in form but bilateral in effect. Each jurisdiction files with the OECD a list of the partners it intends to exchange with, and a relationship goes live only if both sides have named each other. That lets a country decline to send data to a partner whose confidentiality safeguards it considers inadequate. Several thousand bilateral relationships are active today.
The European Union went its own way. Directive 2014/107/EU of December 9, 2014, known as DAC2, writes the CRS into EU law and makes exchange mandatory among member states. The Savings Directive, now redundant, was repealed in 2015 by Council Directive (EU) 2015/2060. Mirror agreements were struck with Switzerland, Liechtenstein, Andorra, Monaco, and San Marino, as the European Commission's DAC2 page confirms.
National implementation varies in its details. France, for example, codified the regime in its tax code, has its institutions report to the national tax authority for onward transmission, and tightened the rules in a 2018 anti-fraud law requiring banks to report account holders who refuse to provide a self-certification of tax residence (BOFiP, BOI-INT-AEA-20-25).
Who reports, and what do they report?
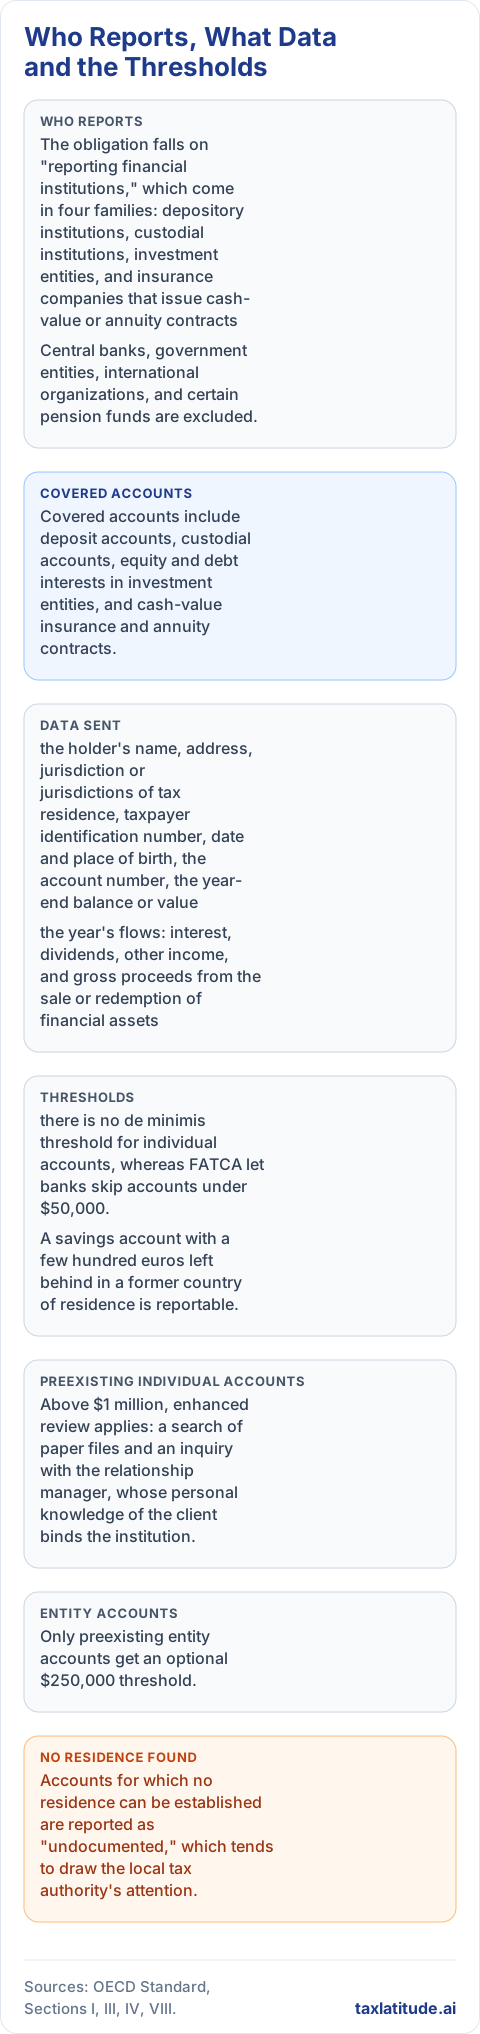
The mechanics borrow FATCA's grammar. The obligation falls on "reporting financial institutions," which come in four families: depository institutions, custodial institutions, investment entities, and insurance companies that issue cash-value or annuity contracts (OECD Standard, Section VIII). The investment entity category is the broadest and the trickiest. It takes in funds and asset managers, but also many private wealth structures, trusts, and family holding companies, as long as their financial assets are professionally managed. A trust managed by a private bank is thus itself a financial institution, required to report on its own beneficiaries. Central banks, government entities, international organizations, and certain pension funds are excluded.
Covered accounts include deposit accounts, custodial accounts, equity and debt interests in investment entities, and cash-value insurance and annuity contracts. Each country may carve out products with a low risk of evasion, typically regulated retirement and employee savings plans, provided it lists them publicly.
For each reportable account, the institution transmits the holder's name, address, jurisdiction or jurisdictions of tax residence, taxpayer identification number, date and place of birth, the account number, the year-end balance or value, and the year's flows: interest, dividends, other income, and gross proceeds from the sale or redemption of financial assets (OECD Standard, Section I). That last item is often underestimated. The receiving tax authority sees not just a snapshot but movement.
Which jurisdictions participate?
As of the OECD's most recent update (7 April 2026), 126 jurisdictions have committed to exchange information under the CRS, with first exchanges phased in starting in 2017 and the latest commitments, including Papua New Guinea's, not due until 2027 (OECD, CRS by jurisdiction). The list below is current as of that update:
Albania, Andorra, Anguilla, Antigua and Barbuda, Argentina, Armenia, Aruba, Australia, Austria, Azerbaijan, Bahamas, Bahrain, Barbados, Belgium, Belize, Bermuda, Brazil, British Virgin Islands, Brunei Darussalam, Bulgaria, Cameroon, Canada, Cayman Islands, Chile, China (People's Republic of), Colombia, Cook Islands, Costa Rica, Croatia, Curaçao, Cyprus, Czechia, Denmark, and Dominica.
Ecuador, Estonia, Faroe Islands, Finland, France, Georgia, Germany, Ghana, Gibraltar, Greece, Greenland, Grenada, Guernsey, Hong Kong (China), Hungary, Iceland, India, Indonesia, Ireland, Isle of Man, Israel, Italy, Jamaica, Japan, Jersey, and Jordan.
Kazakhstan, Kenya, Korea, Kuwait, Latvia, Lebanon, Liechtenstein, Lithuania, Luxembourg, Macau (China), Malaysia, Maldives, Malta, Marshall Islands, Mauritius, Mexico, Moldova, Monaco, Mongolia, Montenegro, Montserrat, Morocco, Nauru, Netherlands, New Zealand, Nigeria, Niue, Norway, Oman, Pakistan, Panama, Papua New Guinea, Peru, Poland, and Portugal.
Qatar, Romania, Russian Federation, Rwanda, Saint Kitts and Nevis, Saint Lucia, Saint Vincent and the Grenadines, Samoa, San Marino, Saudi Arabia, Senegal, Seychelles, Singapore, Sint Maarten, Slovak Republic, Slovenia, South Africa, Spain, Sweden, Switzerland, Thailand, Trinidad and Tobago, Tunisia, Türkiye, Turks and Caicos Islands, Uganda, Ukraine, United Arab Emirates, United Kingdom, Uruguay, and Vanuatu.
The United States is not on this list — it never signed onto the CRS, relying on FATCA's narrower, one-way reporting instead. A jurisdiction's absence from this list does not mean it never asks for account information; it means financial institutions there are not yet required to collect and exchange it automatically under this specific standard.
What does due diligence for finding the residence involve?
The operational heart of the CRS is the identification procedure, which differs depending on whether the account predates the regime or was opened afterward.
For new accounts, the rule is simple: no self-certification, no account. The client states in writing where they are tax resident and provides their tax ID numbers, and the bank must check that statement for reasonableness against what it otherwise knows, including through its anti-money-laundering files (OECD Standard, Section IV). A client who claims to be a resident of Dubai but whose mail all goes to an address in Lyon presents a problem the bank is not allowed to ignore.
For preexisting individual accounts, the standard sets two tiers (OECD Standard, Section III). Up to $1 million, the bank may rely on the residence address on file if it is supported by documentation, or otherwise run an electronic search for indicia: a mailing address or phone number in a foreign country, standing instructions to transfer funds there, a power of attorney granted to someone who lives there, or a hold-mail or "in care of" address as the only address on file. Above $1 million, enhanced review applies: a search of paper files and an inquiry with the relationship manager, whose personal knowledge of the client binds the institution. Accounts for which no residence can be established are reported as "undocumented," which tends to draw the local tax authority's attention.
Two major differences from FATCA stand out. First, the test is tax residence, not citizenship: the CRS has no equivalent of the "accidental American." Second, there is no de minimis threshold for individual accounts, whereas FATCA let banks skip accounts under $50,000. A savings account with a few hundred euros left behind in a former country of residence is reportable.
Did you leave a small account behind in your last country of residence? Under CRS there's no minimum balance for individuals — a forgotten account with a few hundred euros gets reported just like a large one, and the IRS expects its own FBAR/Form 8938 reporting regardless of size. Check whether you still need to report it →
Only preexisting entity accounts get an optional $250,000 threshold. TaxLatitude's free tax residency tool helps work out which country counts as your tax residence after a move.Many countries have also adopted the "wider approach," under which banks collect tax residence information from all foreign clients, not just those living in current partner countries, so they don't have to redo the exercise every time a new jurisdiction joins.
How do you pierce the structure to look through entities?
The Savings Directive's fatal flaw was the shell company. The CRS answers with a look-through rule. Entity account holders fall into two categories. "Active" non-financial entities, which essentially means businesses with genuine commercial operations, publicly traded companies, and nonprofits, are reported only in their own name. "Passive" entities, those with more than half their income or assets of an investment nature, get pierced: the bank identifies the "controlling persons" and reports them to their own country of residence (OECD Standard, Sections V and VIII).
The concept is borrowed from the beneficial ownership recommendations of the Financial Action Task Force, with a 25% ownership threshold in practice for companies. For trusts, the standard casts a deliberately wide net: the settlor, the trustees, the protector if there is one, and the beneficiaries are all deemed controlling persons, whether or not they exercise any actual control.
An anti-avoidance clause takes direct aim at countries outside the system: an investment entity located in a non-participating jurisdiction is treated as a passive entity. One notable consequence is that a U.S. fund or trust holding an account in Geneva or Singapore gets looked through, and its French or German beneficiaries are reported. The American shelter, as we'll see, works only for assets held in the United States itself.
What are the calendar and the plumbing?
The cycle is annual. Institutions report to their tax authority in the first half of the year following the reporting year, and tax authorities exchange the data by the end of September. Files follow a standardized XML schema and travel over an encrypted platform run by the OECD, the Common Transmission System, in service since 2017. The organization never sees the contents. It just provides the pipe.
Forty-nine "early adopter" jurisdictions, including nearly all of the EU, made their first exchanges in September 2017, covering 2016 data, according to the OECD's announcement of the first exchanges. Some 50 more, including Switzerland, Singapore, Hong Kong, and the Bahamas, followed in September 2018. Panama, initially a holdout, came around in 2016, a few weeks after the Panama Papers broke. More than 120 jurisdictions have now committed, as noted in the Global Forum's 2023 plenary statement (123 jurisdictions at the time).
The volumes are staggering. According to the Global Forum, exchanges in 2019 covered 84 million accounts holding about €10 trillion in assets. By 2022, the figures were 123 million accounts and nearly €12 trillion (Global Forum, December 1, 2023).
What did the Standard change?
The most tangible effect came before the first exchange ever took place. Knowing transparency was inevitable, hundreds of thousands of taxpayers came clean through voluntary disclosure programs around the world. For Americans specifically, TaxLatitude's guide to the Streamlined Filing Compliance Procedures covers the IRS route for catching up on unfiled returns. In France alone, a dedicated disclosure unit open from mid-2013 through the end of 2017 handled on the order of 50,000 cases and recovered roughly €8 billion, according to a French government answer to a parliamentary question. Worldwide, the Global Forum puts at more than €120 billion the additional revenue identified since 2009 through voluntary disclosures and offshore investigations (Global Forum, December 1, 2023), an aggregate figure to be handled with care, since it lumps together very different programs and counting methods.
Independent research points the same way. An OECD analysis published in 2019 found that bank deposits held by foreigners in international financial centers fell by roughly a quarter between 2008 and 2019, with automatic exchange accounting for a substantial share of the drop. Researchers Elisa Casi, Christoph Spengel, and Barbara Stage, in a 2020 paper, measured a decline of around 11% in cross-border deposits in tax havens attributable to the CRS. The EU Tax Observatory went further in its 2023 global report: offshore tax evasion by individuals has fallen by a factor of about three in ten years. Before 2013, the bulk of offshore financial wealth, the equivalent of 10% of world GDP, went untaxed; today that is true of only about a quarter. Gabriel Zucman, no one's idea of an OECD cheerleader, calls it one of the few undeniable successes of international tax cooperation.
What are the blind spots?
The picture has its dark areas, though, and the first is the size of a continent. The United States never joined the CRS. Washington maintains that its reciprocal FATCA agreements serve the same purpose, which is inaccurate: the information the IRS sends abroad is far more limited, with no account balances and no identification of the beneficial owners behind entities.
Think FATCA already tells your home country everything the CRS would? It doesn't — the data the IRS sends abroad excludes account balances and the people behind trusts and companies, a gap you shouldn't rely on for your own reporting. Understand what actually gets shared about you →
The Casi, Spengel, and Stage study found that the United States was the only major financial center where cross-border deposits rose after the standard took effect. South Dakota, Nevada, and Delaware have built a trust industry on that asymmetry. The OECD, which owes its standard to American pressure, has never put the United States on a list of uncooperative jurisdictions.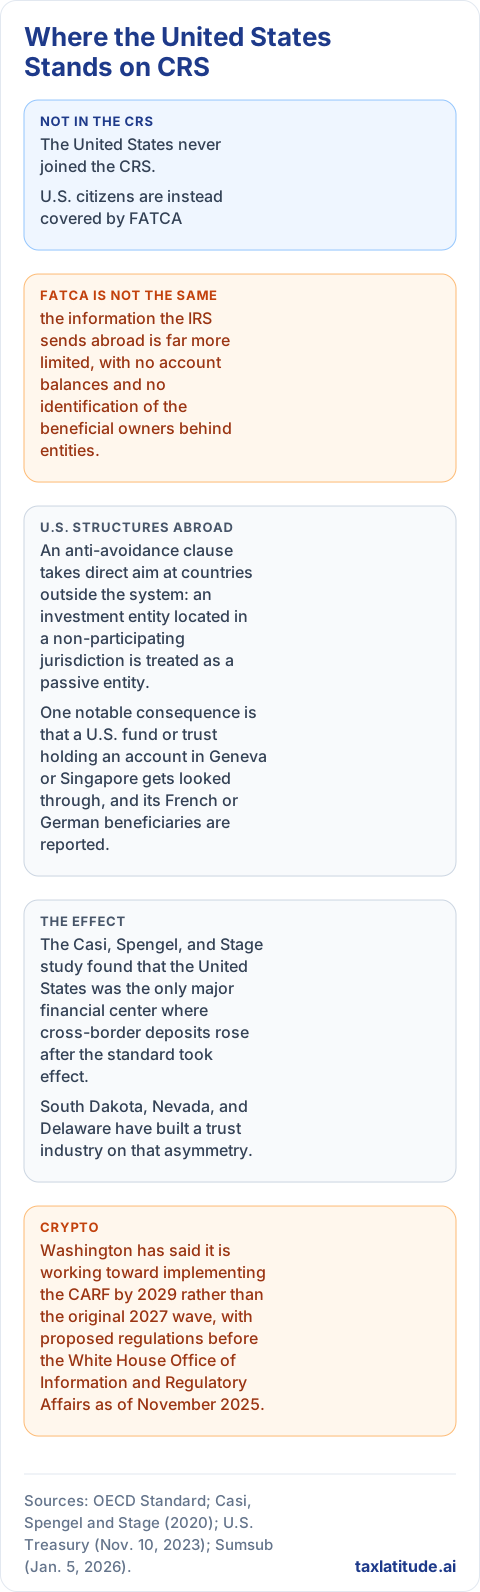
The second gap is scope. The CRS covers only financial assets held through intermediaries. Directly owned real estate, physical gold, art, and the contents of safe deposit boxes and freeports fall outside it. The available research suggests that some of the wealth that left offshore accounts went into property, in London, Dubai, and elsewhere, a shift the EU Tax Observatory's Global Tax Evasion Report discusses under the growing importance of offshore real estate. Crypto assets and e-money, nonexistent or marginal when the standard was designed, weren't covered either.
The third gap is residence itself. Since everything hinges on declared tax residence, all you have to do is buy one. A number of jurisdictions sell residence permits or passports in exchange for investment, with no requirement of actual physical presence. A European taxpayer holding a residence certificate from a Caribbean island can present it to the bank, which will then report the data to a government that will do nothing with it. In October 2018, the OECD published a list of high-risk programs and asked banks to apply extra scrutiny. It also drew up, that same year, mandatory disclosure rules for CRS avoidance arrangements, which the EU folded into its DAC6 directive requiring intermediaries to report the schemes they design.
The fourth limit is less visible: the North-South divide. To receive data, a country must show it can protect it and must have the systems to process it. Many developing countries, particularly in Africa, remain outside the system or are joining late, even though they are proportionally the hardest hit by capital flight. Conversely, several tax havens with no income tax participate on a "non-reciprocal" basis: they send, and ask for nothing back.
Finally, receiving data is not the same as using it. Matching millions of records to taxpayers, with transliterated names and missing or wrong tax ID numbers, takes resources not every tax agency has. The Global Forum has supplemented its reviews of legal frameworks with reviews of effectiveness in practice, and the first findings, in 2022, showed very uneven results (Global Forum, AEOI effectiveness ratings). Concentrating data this sensitive also creates a risk of its own: after Bulgaria's tax agency was hacked in 2019, several partners suspended their transmissions to Sofia (Global Forum statement on the data breach in the National Revenue Agency of Bulgaria; Swiss State Secretariat for International Finance). Lawyers, particularly in the United Kingdom, have also challenged the regime's proportionality under the General Data Protection Regulation, so far without obtaining a landmark ruling from the EU's Court of Justice — a separate GDPR case now pending before that court, Case C-804/25, concerns FATCA data transfers from Belgium to the United States, not the CRS.
What is CRS 2.0, and how does it move into crypto?
The OECD has undertaken the standard's first major overhaul. In 2022, it adopted the Crypto-Asset Reporting Framework (CARF), which requires exchanges and other service providers to report their customers' transactions along lines modeled on the CRS. In parallel, the CRS itself was amended: e-money and central bank digital currencies were brought in, indirect crypto investments through funds or derivatives were covered, and the data transmitted was enriched, particularly regarding the exact role of controlling persons, joint accounts, and the validity of self-certifications. The package was published in consolidated form in 2023 (OECD, International Standards for Automatic Exchange of Information in Tax Matters: Crypto-Asset Reporting Framework and 2023 update to the Common Reporting Standard).
Some 50 jurisdictions pledged in November 2023 to implement the CARF (U.S. Treasury, "Collective Engagement to Implement the Crypto-Asset Reporting Framework," November 10, 2023), and the framework took effect on January 1, 2026 in the 46 jurisdictions due to make first international exchanges in 2027 (OECD Global Forum, CARF commitments list, last updated September 14, 2026). The United States itself is now tracking later: Washington has said it is working toward implementing the CARF by 2029 rather than the original 2027 wave, with proposed regulations before the White House Office of Information and Regulatory Affairs as of November 2025. The EU wrote both pieces into its DAC8 directive of October 2023, applicable from January 1, 2026 — though twelve member states (Belgium, Bulgaria, Cyprus, Czechia, Estonia, Greece, Luxembourg, Malta, the Netherlands, Poland, Portugal, and Spain) missed the December 31, 2025 deadline to transpose it into national law, and the European Commission opened infringement procedures against all twelve on January 30, 2026. At the G20's request, the OECD has also moved on cross-border real estate ownership, long the biggest remaining blind spot: in December 2025, 26 jurisdictions pledged to implement a new Multilateral Competent Authority Agreement on the Exchange of Readily Available Information on Immovable Property, with first exchanges targeted for 2029 or 2030.
Is this a success, and what is its limit?
The CRS accomplished what 30 years of tax diplomacy had not: it made bank opacity the exception rather than the rule. Fifteen years ago, keeping an undeclared account in Geneva or Luxembourg was routine practice among well-off Europeans. Today it is a criminal exposure that almost no established bank will take on. The standard got there without a binding treaty, without a world tax organization, through nothing more than peer pressure, blacklists, and the pull of an American statute.
That is also its limit. A system that owes its existence to one country's power is powerless against that country. As long as the United States stays outside, the CRS will be a fine-mesh net stretched around a hole. And as long as residence can be bought and fortunes converted into apartments, banking transparency will mostly capture the people who can't afford to get around it. The wider history of international tax cooperation picks up from here — BEPS, the global minimum tax, and the power struggle now testing all of it.
A note on scope: this article is general information, not tax or legal advice. Whether a given account or entity is reportable under the CRS depends on your own facts and on each country's domestic implementing rules, which this overview does not substitute for. Consult a qualified professional before acting on your own reporting position.
Frequently asked questions
Will my bank report my foreign account to my home country under CRS?
Yes, if you are tax resident in a country other than the one where the account is held and both countries exchange with each other: the bank reports your name, address, tax ID, date and place of birth, account number, year-end balance, and income to its own tax authority, which sends it to your country of residence by the end of September of the following year.
Is there a minimum balance below which CRS doesn't apply?
No, not for individual accounts. Unlike FATCA, the CRS has no de minimis threshold for individuals, so even a dormant savings account with a few hundred euros is reportable; only preexisting entity accounts may benefit from an optional $250,000 threshold.
Does CRS apply to U.S. citizens or to accounts held in the United States?
The United States has never joined the CRS, so U.S. banks do not report under it, and the CRS test is tax residence rather than citizenship. U.S. citizens are instead covered by FATCA, and a U.S. fund or trust holding an account in a CRS country is treated as a passive entity and looked through to its controlling persons.
What happens if I don't return my bank's CRS self-certification form?
For a new account, the bank cannot open it without a self-certification of your tax residence. For older accounts, the bank falls back on the indicia in its files, and an account whose residence cannot be established is reported as "undocumented"; in France, banks must also report account holders who fail to return the form (BOFiP, BOI-INT-AEA-20-25).
Are trusts and family holding companies reported under CRS?
Yes. A professionally managed trust or holding company is usually an investment entity that reports on its own beneficiaries, and a passive entity holding an account elsewhere is looked through: the settlor, trustees, any protector, and the beneficiaries of a trust are all reported as controlling persons, whether or not they exercise control.
Does CRS cover crypto-assets and real estate?
The original CRS covers neither directly held crypto-assets nor real estate. Crypto is being brought in through the separate CARF and the 2023 CRS amendments, which the EU applies through DAC8 from January 1, 2026, while directly owned property remains outside automatic exchange except where jurisdictions join the OECD's new immovable property framework, which 26 pledged to implement in December 2025 (OECD, December 2025).
When should you hire a professional?
Because CRS reporting happens automatically and the data lands with your tax authority whether or not you declared the account, the moment to get advice is before a reported account and your own tax return tell different stories.
- Undocumented account drawing attention. If your account was reported as "undocumented" and your tax authority has started asking questions, a professional can reconstruct your residence history and respond before the inquiry becomes an audit.
- Trusts and passive entities. If you are a settlor, trustee, protector, or beneficiary of a trust, or own a holding company, controlling-person analysis decides who gets reported where, and an error can expose several family members at once.
- Purchased residence or citizenship. If you obtained residence or a passport through an investment program, banks may treat your self-certification with extra scrutiny under the OECD's 2018 guidance, and your actual tax residence may not be the one on your certificate.
- Moving countries mid-year. If you changed residence during the year, which tax authority receives the report, and whether you are dual resident under a treaty tie-breaker, needs a careful look at both countries' rules.
- Active or passive classification. If you own a company with an account abroad, whether more than half its income or assets are investment-type determines whether the bank looks through it to you, and the classification is often less obvious than it seems.
- Old undeclared accounts. If an account from a former country of residence was never declared, a professional can assess whether a voluntary disclosure route still exists before the CRS data does the disclosing for you.
A CPA or enrolled agent fits ordinary filing and disclosure of reported accounts, a tax attorney fits cases with audit or penalty exposure, and a cross-border specialist familiar with both countries' CRS implementation fits trusts, entity classification, and dual-residence questions.
Sources
All sources accessed October 16, 2026. Page dates are given only where the page showed one; otherwise the cell says so.
| Source | URL | Used for | Page date |
|---|---|---|---|
| OECD, Standard for Automatic Exchange of Financial Account Information in Tax Matters, Second Edition | https://www.oecd.org/en/publications/standard-for-automatic-exchange-of-financial-account-information-in-tax-matters-second-edition_9789264267992-en.html | CRS text, July 15, 2014 Council approval, reporting, due diligence, entity rules | March 27, 2017 |
| OECD, Common Reporting Standard page (CRS MCAA, signatories, consolidated text) | https://www.oecd.org/tax/automatic-exchange/common-reporting-standard.html | Multilateral Competent Authority Agreement | Not shown |
| OECD, Convention on Mutual Administrative Assistance in Tax Matters | https://www.oecd.org/ctp/exchange-of-tax-information/convention-on-mutual-administrative-assistance-in-tax-matters.htm | 1988 Convention, 2010 Protocol | Not shown |
| Council of Europe, Convention on Mutual Administrative Assistance in Tax Matters as amended by the 2010 Protocol (text) | https://rm.coe.int/16806a42b0 | Article 6 automatic exchange | Not shown |
| OECD, Towards Global Tax Co-operation (2000 progress report) | https://t4.oecd.org/tax/harmful/2090192.pdf | 1998 harmful tax competition report, 2000 tax haven list | Not shown |
| IFC Review, "Improved cooperation to counter offshore non compliance" | https://ifcreview.com/articles/2011/february/improved-cooperation-to-counter-offshore-non-compliance | 2002 model information exchange agreement (secondary) | February 2011 |
| EUR-Lex, Council Directive 2003/48/EC (Savings Directive) | https://eur-lex.europa.eu/eli/dir/2003/48/oj/eng | Savings Directive scope | June 26, 2003 (Official Journal) |
| Global Forum, History | https://www.oecd.org/en/networks/global-forum-tax-transparency/who-we-are/history.html | April 2009 G20 declaration and OECD list | Not shown |
| OECD, 5th Global Forum meeting, Mexico City, September 1-2, 2009 | https://web.archive.org/web/20210311162023/http://www.oecd.org/mexico/5thglobalforumontransparencyandexchangeofinformation1-2september2009mexicocity.htm | Global Forum restructuring | Not shown |
| Johannesen and Zucman, "The End of Bank Secrecy? An Evaluation of the G20 Tax Haven Crackdown," AEJ: Economic Policy 6(1) | https://doi.org/10.1257/pol.6.1.65 | 12-agreement rule, deposit shifting between havens | February 2014 |
| The Local Switzerland, "Bern and bankers digest German tax deal veto" | https://www.thelocal.ch/20121123/bern-and-bankers-digest-german-tax-deal-veto | Bundesrat rejection of Rubik agreement (secondary) | November 23, 2012 |
| Cleary Gottlieb, "Treasury and the IRS Release Proposed Regulations under FATCA" | https://www.clearygottlieb.com/news-and-insights/publication-listing/treasury-and-the-irs-release-proposed-regulations-under-fatca3 | FATCA enactment date (secondary) | February 15, 2012 |
| GOV.UK, Joint Statement regarding an Intergovernmental Approach to Improving International Tax Compliance and Implementing FATCA | https://www.gov.uk/government/news/joint-statement-regarding-an-intergovernmental-approach-to-improving-international-tax-compliance-and-implementing-fatca | February 8, 2012 G5 statement | February 8, 2012 |
| CNN Money, "Europe's bank secrecy crumbles" | https://money.cnn.com/2013/04/10/news/economy/europe-bank-secrecy/index.html | Luxembourg April 2013 announcement (secondary) | April 10, 2013 |
| EUR-Lex, Council Directive 2014/107/EU (DAC2) | https://eur-lex.europa.eu/eli/dir/2014/107/oj | DAC2; February 2014 release and G20 endorsement of the CRS | December 16, 2014 (Official Journal) |
| States of Jersey, P.117/2015, Ratification of the Multilateral Competent Authority Agreement | https://statesassembly.gov.je/assemblypropositions/2015/p.117-2015.pdf | October 29, 2014 Berlin signing by 51 jurisdictions | Lodged October 13, 2015 |
| Swiss Federal Council, "Switzerland takes further step towards introduction of automatic exchange of information" | https://admin.ch/gov/en/start/documentation/media-releases.msg-id-55327.html | Swiss MCAA signature, November 19, 2014 | November 19, 2014 |
| EUR-Lex, Council Directive (EU) 2015/2060 | https://eur-lex.europa.eu/eli/dir/2015/2060/oj/eng | Repeal of the Savings Directive | November 18, 2015 (Official Journal) |
| European Commission, DAC2 | https://taxation-customs.ec.europa.eu/dac2_en | Agreements with Andorra, Liechtenstein, Monaco, San Marino, Switzerland | Not shown |
| BOFiP, BOI-INT-AEA-20-25 (Common Reporting Standard: account holders' obligations) (in French) | https://bofip.impots.gouv.fr/bofip/11549-PGP.html/identifiant%3DBOI-INT-AEA-20-25-20181107 | French self-certification and reporting of non-certifying holders | November 7, 2018 |
| OECD, Generic Status Message XML Schema and User Guide | https://t4.oecd.org/ctp/exchange-of-tax-information/generic-status-message-xml-schema-user-guide-tax-administrations.htm | Common Transmission System launched in 2017 | Not shown |
| OECD, "First automatic CRS exchanges between 49 jurisdictions to take place" | https://web.archive.org/web/20231005001320/https://www.oecd.org/tax/automatic-exchange/news/first-automatic-crs-exchanges-between-49-jurisdictions-to-take-place-over-2000-bilateral-exchange-relationships-in-place.htm | 49 first exchangers in 2017, 53 in 2018 | Not shown |
| EY Global Tax Alert, "Panama commits to implementing the OECD's Common Reporting Standard as of 2018" | https://taxnews.ey.com/news/2016-0724-panama-commits-to-implementing-the-oecds-common-reporting-standard-as-of-2018 | Panama 2016 commitment (secondary) | April 20, 2016 |
| Modern Diplomacy, republication of OECD release "International community continues making progress against offshore tax evasion" | https://moderndiplomacy.eu/2020/07/02/international-community-continues-making-progress-against-offshore-tax-evasion/ | 2019 exchange volumes, bilateral relationships (secondary) | July 2, 2020 |
| Global Forum, "Global Forum charts course for its future tax transparency agenda" | https://www.oecd.org/en/networks/global-forum-tax-transparency/news-events/2023/global-forum-charts-course-for-its-future-tax-transparency-agenda-building-on-remarkable-achievements-so-far.html | 2022 exchange volumes, 123 committed jurisdictions, €126 billion revenue | December 1, 2023 |
| Global Forum, Peer Review of the Automatic Exchange of Financial Account Information 2024 Update | https://www.oecd.org/en/publications/peer-review-of-the-automatic-exchange-of-financial-account-information-2024-update_1aa02413-en | 2023 exchange volumes | Not shown |
| Assemblée nationale, written question No. 9240 and government answer (STDR) | https://www.assemblee-nationale.fr/dyn/15/questions/QANR5L15QE9240.pdf | French disclosure unit: 50,000 cases, recoveries | Not shown |
| O'Reilly, Parra Ramirez and Stemmer, "Exchange of Information and Bank Deposits in International Financial Centres," OECD Taxation Working Paper No. 46 | https://read.oecd-ilibrary.org/en/publications/exchange-of-information-and-bank-deposits-in-international-financial-centres_025bfebe-en.html | 24% fall in foreign-owned IFC deposits, 2008-2019 | Not shown |
| Casi, Spengel and Stage, "Cross-border tax evasion after the common reporting standard: Game over?" Journal of Public Economics 190 | https://doi.org/10.1016/j.jpubeco.2020.104240 | 11.5% fall in tax-haven deposits, rise in U.S. deposits | 2020 |
| EU Tax Observatory, Global Tax Evasion Report 2024 | https://halshs.archives-ouvertes.fr/halshs-04563948v1/file/global_tax_evasion_report_24.pdf | Threefold fall in offshore evasion, offshore real estate | Deposited April 30, 2024 |
| OECD, "OECD clamps down on CRS avoidance through residence and citizenship by investment schemes" | https://web.archive.org/web/20240620183232/https://www.oecd.org/tax/oecd-clamps-down-on-crs-avoidance-through-residence-and-citizenship-by-investment-schemes.htm | October 2018 high-risk CBI/RBI list | October 16, 2018 |
| OECD, Model Mandatory Disclosure Rules for CRS Avoidance Arrangements and Opaque Offshore Structures | https://www.oecd.org/en/publications/model-mandatory-disclosure-rules-for-addressing-crs-avoidance-arrangements-and-opaque-offshore-structures_e3cabd80-en.html | 2018 mandatory disclosure rules | March 9, 2018 |
| EUR-Lex, Council Directive (EU) 2018/822 (DAC6) | https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=celex:32018L0822 | DAC6 intermediary reporting | Not shown |
| Global Forum, AEOI effectiveness ratings | https://www.oecd.org/en/networks/global-forum-tax-transparency/resources/automatic-exchange-of-information-ratings.html | 2022 effectiveness reviews and uneven ratings | Not shown |
| Global Forum, Statement on the data breach in the National Revenue Agency of Bulgaria | https://www.oecd.org/en/networks/global-forum-tax-transparency/news-events/2019/statement-on-the-data-breach-in-the-national-revenue-agency-of-bulgaria.html | 2019 Bulgarian hack and suspension of exchanges | August 30, 2019 |
| Swiss State Secretariat for International Finance, "Switzerland suspends AEOI with Bulgaria" | https://www.sif.admin.ch/en/switzerland-suspends-aeoi-bulgaria | Partner suspension of transmissions to Bulgaria | September 20, 2019 |
| Mishcon de Reya, "CRS background and further information" | https://www.mishcon.com/news/crs-background-and-further-information | GDPR challenges to the CRS (secondary) | Not shown |
| Mayer Brown, "EU Court of Justice to Examine GDPR Compliance of FATCA-Related Bank Data Transfers" | https://www.mayerbrown.com/en/pdf/insights/publications/2025/12/eu-court-of-justice-to-examine-gdpr-compliance-of-fatca-related-bank-data-transfers | Case C-804/25 (FATCA, distinct from CRS) (secondary) | December 2025 |
| OECD, International Standards for Automatic Exchange of Information in Tax Matters: Crypto-Asset Reporting Framework and 2023 update to the Common Reporting Standard | https://www.oecd.org/en/publications/2023/06/international-standards-for-automatic-exchange-of-information-in-tax-matters_ab3a23bc/full-report.html | CARF and CRS amendments | June 2023 |
| U.S. Treasury, "Collective Engagement to Implement the Crypto-Asset Reporting Framework" (FRASER archive copy) | https://fraser.stlouisfed.org/files/docs/publications/treaspr/2023/2023-11-10_jy1895.pdf | November 2023 joint statement and its signatories, including the United States | November 10, 2023 |
| Sumsub, "Global Crypto Tax Data Collection to Begin in 48 Countries Under CARF" | https://sumsub.com/media/news/global-crypto-tax-data-collection-under-carf/ | CARF 2027/2028 waves; United States in 2029 (secondary) | January 5, 2026 |
| OECD Global Forum, Jurisdictions committed to implement the Crypto-Asset Reporting Framework | https://www.oecd.org/content/dam/oecd/en/networks/global-forum-tax-transparency/commitments-carf.pdf | 46 jurisdictions committed to first CARF exchanges by 2027 | September 14, 2026 |
| Government of Jersey, Crypto-Asset Reporting Framework and expansion of the CRS | https://www.gov.je/TaxesMoney/InternationalTaxAgreements/IGAs/Pages/CryptoAssetReporting.aspx | 48 jurisdictions committed for the 2026 CARF reporting period | Not shown |
| EUR-Lex, Council Directive (EU) 2023/2226 (DAC8) | https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=OJ:L_202302226 | DAC8 text | October 24, 2023 (Official Journal) |
| KPMG TaxNewsFlash, "EU: EC launches infringement procedures for failure to transpose DAC9 and DAC8" | https://kpmg.com/us/en/taxnewsflash/news/2026/02/ec-launches-infringement-procedures-dac9-dac8.html | DAC8 infringement procedures against 12 member states (secondary) | February 13, 2026 |
| ATOZ, "Law transposing DAC8 adopted by Luxembourg Parliament" | https://atoz.lu/media/law-transposing-dac8-adopted-luxembourg-parliament | Luxembourg DAC8 law of March 19, 2026 (secondary) | Not shown |
| OECD, "OECD welcomes pledge by 26 jurisdictions to implement new international tax transparency framework for offshore real estate" | https://www.oecd.org/en/about/news/announcements/2025/12/oecd-welcomes-pledge-by-26-jurisdictions-to-implement-new-international-tax-transparency-framework-for-offshore-real-estate.html | IPI MCAA real estate framework and pledges | December 2025 |