In under twenty years, the world buried banking secrecy, set up automatic data exchange on more than 100 million accounts, and established the principle of a global minimum tax on multinationals. This revolution, born of the 2008 crisis and a string of spectacular leaks, goes by a misleading name. There is no international tax “harmonization,” only coordination extracted under pressure, unfinished, and now being challenged by the very power that made it possible.
Key takeaways
- The rules that still decide which country taxes cross-border profit — taxation at source through a physical "permanent establishment" and "arm's length" pricing between affiliates — trace back to the League of Nations' 1923 Report on Double Taxation and now run through more than 3,000 bilateral treaties.
- Banking secrecy for foreigners ended after the G20 declared in its London communiqué of April 2, 2009 that its era was over, followed by FATCA in 2010 (a 30% withholding penalty on non-reporting foreign banks) and the OECD's 2014 Common Reporting Standard.
- The OECD's BEPS project produced 15 actions in October 2015, including country-by-country reporting for groups with €750 million or more in revenue under the Action 13 final report.
- Pillar Two sets a 15% minimum effective tax rate, calculated country by country, for groups with €750 million or more in revenue; the EU made it binding through Council Directive (EU) 2022/2523 with rules taking effect in 2024.
- The United States rejected the 2021 deal in a January 20, 2025 presidential memorandum, and under the Inclusive Framework's side-by-side package U.S.-parented groups are exempt from Pillar Two's Income Inclusion Rule and Undertaxed Profits Rule.
- The outcome on corporations is still open: the EU Tax Observatory's Global Tax Evasion Report 2024 puts profits shifted to tax havens at close to $1 trillion in 2022, and the UN framework convention on tax cooperation, whose negotiations are scheduled to end in 2027, may not be ratified by the main home countries of multinationals.
What happened in 1923 with four economists and a hundred-year compromise?
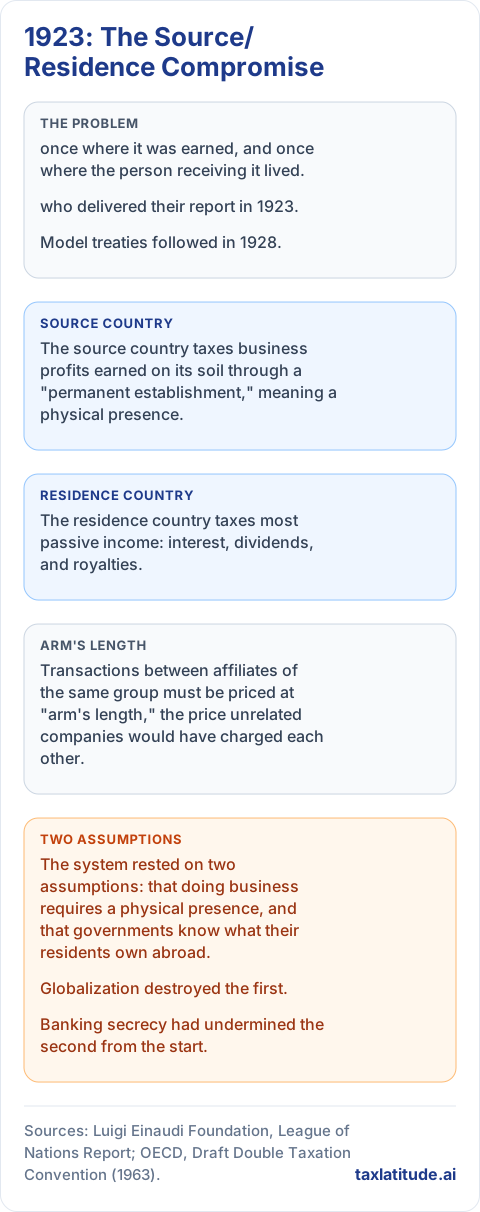
The international tax system grew out of the opposite problem from the one that preoccupies us today. In the aftermath of World War I, income taxes, still new and swollen by the war effort, threatened to hit the same profit twice: once where it was earned, and once where the person receiving it lived. The League of Nations handed the question to four economists, Bruins of the Netherlands, Einaudi of Italy, Seligman of the United States, and Stamp of Britain, who delivered their report in 1923. Model treaties followed in 1928.
The compromise that emerged still governs the world. The source country taxes business profits earned on its soil through a "permanent establishment," meaning a physical presence. The residence country taxes most passive income: interest, dividends, and royalties. Transactions between affiliates of the same group must be priced at "arm's length," the price unrelated companies would have charged each other. The OECD picked up the torch with its 1963 model treaty, the United Nations published a model more favorable to source countries in 1980, and more than 3,000 bilateral treaties now make up the web. For a closer look at what one of these agreements actually says, TaxLatitude's guide to reading a U.S. tax treaty walks through a real treaty text.
The system rested on two assumptions: that doing business requires a physical presence, and that governments know what their residents own abroad. Globalization destroyed the first. Banking secrecy had undermined the second from the start.
How was secrecy invented?
Legend has it that Switzerland created banking secrecy to protect the assets of persecuted Jews. Historians have debunked it. Article 47 of the Federal Banking Act of November 8, 1934, which made breaching bank secrecy a crime, owes a great deal to a French scandal. In the fall of 1932, police raided the Paris offices of the Basler Handelsbank and seized a list of roughly 1,000 client files, among them members of parliament, industrialists, and bishops. The affair, aired on the floor of the Chamber of Deputies, triggered massive withdrawals in Switzerland. Bern responded by giving its bankers' discretion the armor of criminal law.
The postwar years broadened the menu. The Eurodollar market took shape in London in the 1950s, and in its wake the Crown Dependencies and former British outposts, Jersey, the Cayman Islands, the Bahamas, later Singapore and Hong Kong, found their specialties. Luxembourg built its holding company industry, Liechtenstein its foundations, Delaware its anonymous shell companies. The liberalization of capital flows in the 1980s knocked down the last barrier, exchange controls. Money could now leave legally. All it needed was to arrive quietly.
What was the great race to the bottom?
Mobile capital also drew governments into a rate war. The average corporate income tax rate worldwide, above 40% in 1980, had fallen to around 23% forty years later. And the headline rate is only the surface. An economy built on intangibles lets companies park patents, trademarks, and algorithms in subsidiaries located wherever they please, then pay those subsidiaries royalties that hollow out profits in the countries where customers actually are. The arm's-length principle, designed for shiploads of wheat, is helpless against a one-of-a-kind asset that by definition has no comparable market price.
The signature structure, the "Double Irish" with its "Dutch Sandwich," let U.S. tech companies route their European profits to Bermuda while paying tax in the low single digits. Research by Thomas Tørsløv, Ludvig Wier, and Gabriel Zucman estimates that close to 40% of multinationals' foreign profits are shifted to tax havens every year. The figure matches their NBER working paper and the authors' missingprofits.world data site.
What were the first offensives, and why did they fail?
The OECD opened hostilities in 1998 with its report on harmful tax competition, followed in 2000 by a list of 35 tax havens. The European Union adopted a code of conduct on business taxation in 1997, then in 2003 a Savings Directive that created the first automatic exchange of information, promptly circumvented because it covered neither shell companies nor any income other than interest.
The momentum broke in 2001, when George W. Bush's Treasury secretary, Paul O'Neill, pulled U.S. support for the OECD project in the name of tax sovereignty. The blacklist emptied out as jurisdictions signed commitments that cost them nothing. For seven years, next to nothing happened.
Why was 2008 the tipping point?
Three events collided. In February 2008, German police raided the home of Deutsche Post chief Klaus Zumwinkel in front of television cameras: the country's intelligence service had paid a few million euros for a file stolen from LGT, the Liechtenstein bank. A rule-of-law state was buying stolen data, and the public cheered. Around the same time, IT specialist Hervé Falciani walked out of HSBC's Geneva private bank with data on tens of thousands of clients, which ended up in the hands of French tax authorities. And in the United States, banker Bradley Birkenfeld exposed the methods of UBS, which in 2009 was forced to pay $780 million and hand over names.
Then came the financial crisis. Governments that had just bailed out their banks with no hope of getting the money back had no patience left for banks that helped their revenue escape. On April 2, 2009, the G20 leaders in London declared the era of banking secrecy over.
What came next comes down to two acronyms. FATCA, in 2010: the United States requires banks worldwide to report their American clients or face a 30% withholding tax. CRS, in 2014: the OECD extends the mechanism to more than 100 jurisdictions. Luxembourg gave in during 2013, Austria right behind it. The U.S. Justice Department finished off the Swiss model: Wegelin, the country's oldest bank, closed in 2013; Credit Suisse pleaded guilty in 2014 and paid $2.6 billion; some 80 other institutions settled. Switzerland made its first automatic exchanges in 2018. One detail rarely noted: banking secrecy survives intact for Swiss residents with respect to their own tax authorities. It died only for foreigners.
What was the age of leaks?
The political pressure would not have held without a new kind of fuel: the mass data leak, worked through by consortiums of reporters. The International Consortium of Investigative Journalists published Offshore Leaks in 2013, then LuxLeaks in November 2014, revealing hundreds of tax rulings Luxembourg had granted to multinationals, just days after its longtime prime minister, Jean-Claude Juncker, took over as president of the European Commission. SwissLeaks followed in 2015, the Panama Papers in April 2016, which brought down Iceland's prime minister within 48 hours, the Paradise Papers in 2017, and the Pandora Papers in 2021.
Each wave produced its own piece of law. Panama committed to the CRS a few weeks after the revelations that bear its name, and began exchanging data in 2018. LuxLeaks gave rise to the automatic exchange of tax rulings among EU countries. The legislative calendar of tax transparency reads, to a large degree, like a calendar of scandals.
What is BEPS, and how does it go after the multinationals?
The second front opened in the fall of 2012. In London, the House of Commons Public Accounts Committee, chaired by Margaret Hodge, hauled in executives from Starbucks, Google, and Amazon, who explained on camera why billions in U.K. sales produced almost no taxable profit. The committee's findings appear in its report on HM Revenue and Customs' 2011-12 accounts. The G20 gave the OECD a mandate. The BEPS action plan, for "base erosion and profit shifting," was unveiled in July 2013, and its 15 actions were finalized in October 2015.
Four of them became minimum standards, subject to peer review. The crackdown on harmful preferential regimes led to the review of more than 300 of them; as of a February 2025 count, 126 of 332 reviewed regimes had been abolished and 8 more were being eliminated or amended. An anti-abuse clause for tax treaties shut down "treaty shopping." Country-by-country reporting requires groups with €750 million or more in revenue to give tax authorities a global breakdown of their profits, taxes, and headcount. And dispute resolution between governments was improved.
Two institutional innovations came with the substance. The Inclusive Framework, created in 2016, opened the negotiating table beyond the OECD's membership. It now has more than 140 members, though countries of the Global South question how much influence they really have. And the Multilateral Instrument, signed in Paris in June 2017, made it possible to amend more than 1,000 bilateral treaties in a single stroke, avoiding decades of renegotiation. The OECD now says the instrument covers around 2,000 bilateral treaties.
The European Union went beyond the standard: an Anti-Tax Avoidance Directive in 2016, mandatory disclosure of cross-border arrangements by advisers, public country-by-country reporting, and, starting in December 2017, a blacklist criticized for never including a member state. Above all, Margrethe Vestager's competition directorate turned EU state aid law against tax rulings. In August 2016, the Commission ordered Ireland to recover €13 billion from Apple. Annulled by the EU's General Court in 2020, the decision was definitively upheld by the Court of Justice on September 10, 2024. Ireland, which had fought not to collect the money, had in the meantime shut down the Double Irish. The resulting onshoring of intangible assets made its GDP jump 26% in 2015, a statistical artifact that Paul Krugman dubbed "leprechaun economics."
Who owns what, and what is the battle over beneficial ownership?
Exchanging account data is pointless if the account holder is a shell whose owner nobody knows. Prodded by the Financial Action Task Force, beneficial ownership registries multiplied. The United Kingdom opened its registry to the public in 2016, and the EU mandated them through its anti-money-laundering directives of 2015 and 2018.
The movement has since suffered a double setback. On November 22, 2022, the EU's Court of Justice struck down general public access to these registries as a disproportionate intrusion on privacy rights. Only those who can show a legitimate interest, journalists and NGOs included, may now consult them. In the United States, the Corporate Transparency Act, passed at the end of 2020 and in effect from early 2024, was supposed to end the anonymity of Delaware companies. In March 2025, Treasury exempted U.S. companies and their American owners, leaving little of it standing.
What is the 15% floor?
BEPS had plugged holes without tackling two fundamental questions: where to tax a digital economy with no physical presence, and how to stop the race on rates. With no agreement in sight, countries acted alone. France adopted a 3% digital services tax in 2019, Washington threatened tariffs on champagne and handbags, and a dozen countries followed Paris.
The breakthrough came from the United States. The 2017 Tax Cuts and Jobs Act had created, through its GILTI provision, the beginnings of a minimum tax on the foreign profits of U.S. companies. In April 2021, Treasury Secretary Janet Yellen proposed taking the idea global. The G7 reached a deal in London in June, and on October 8, 2021, 136 jurisdictions signed on to a two-pillar statement.
Pillar One was meant to reallocate to market countries a quarter of profits above a 10% margin, for the hundred or so groups with revenue over €20 billion. A draft multilateral convention was published in October 2023. It would have required ratification by a two-thirds vote in the U.S. Senate. It was never opened for signature and can be considered dead. The last official word is the Inclusive Framework co-chairs' January 2025 statement.
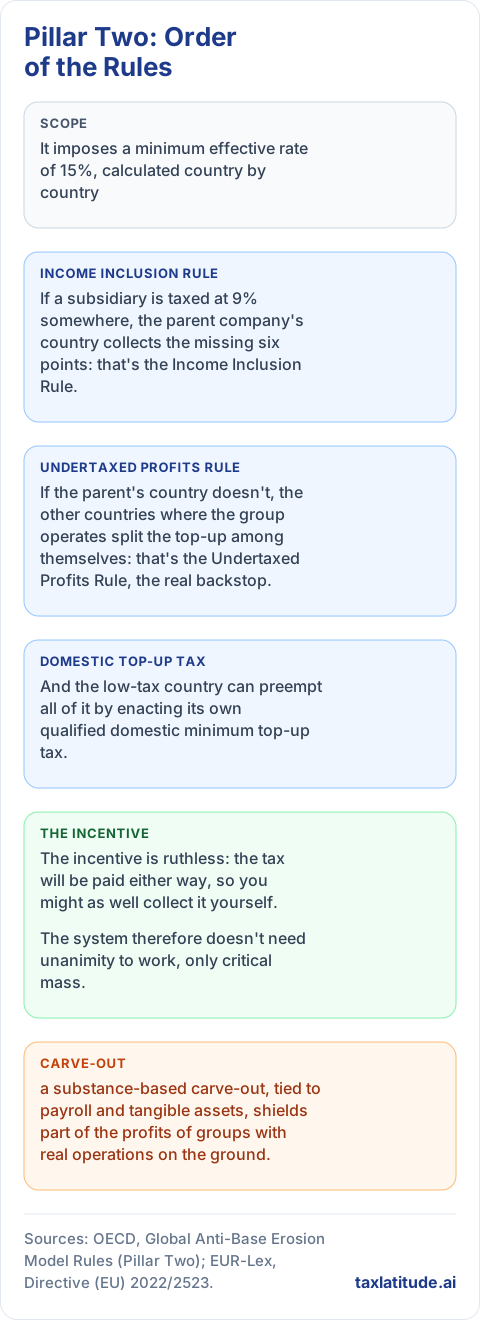
Pillar Two survived. It imposes a minimum effective rate of 15%, calculated country by country, on groups with €750 million or more in revenue. Its mechanics are the cleverest thing about it. If a subsidiary is taxed at 9% somewhere, the parent company's country collects the missing six points: that's the Income Inclusion Rule. If the parent's country doesn't, the other countries where the group operates split the top-up among themselves: that's the Undertaxed Profits Rule, the real backstop. And the low-tax country can preempt all of it by enacting its own qualified domestic minimum top-up tax. The incentive is ruthless: the tax will be paid either way, so you might as well collect it yourself. The system therefore doesn't need unanimity to work, only critical mass.
The EU adopted it through a December 2022 directive, after overcoming successive vetoes from Poland and Hungary, with rules taking effect in 2024. An initial 50 jurisdictions followed, including some unlikely ones; by mid-2026, industry trackers put the count at more than 60 countries and territories with rules in force. Ireland gave up its 12.5% rate for large groups through the Finance (No. 2) Act 2023, Swiss voters approved the reform in a June 2023 referendum, and Bermuda introduced a 15% corporate income tax in 2025. In early 2024, the OECD put the global revenue gain at between $155 billion and $192 billion a year on a projected basis. A 2026 update, released July 15, 2026 and drawing on actual first-year data, now estimates the gain at 3.2% to 5.4% of global corporate tax revenue a year and puts first-year (2024) revenue actually raised at €79 billion to €109 billion — a more modest outcome than the 2024 projection, and one that does not yet account for the side-by-side exemption described below.
The criticism comes in two forms. The rate is low, and a substance-based carve-out, tied to payroll and tangible assets, shields part of the profits of groups with real operations on the ground. More important, the rules treat certain refundable tax credits favorably, so competition on rates may simply turn into competition on subsidies. The EU Tax Observatory argues these loopholes have eaten away most of the expected yield.
What was the American retreat?
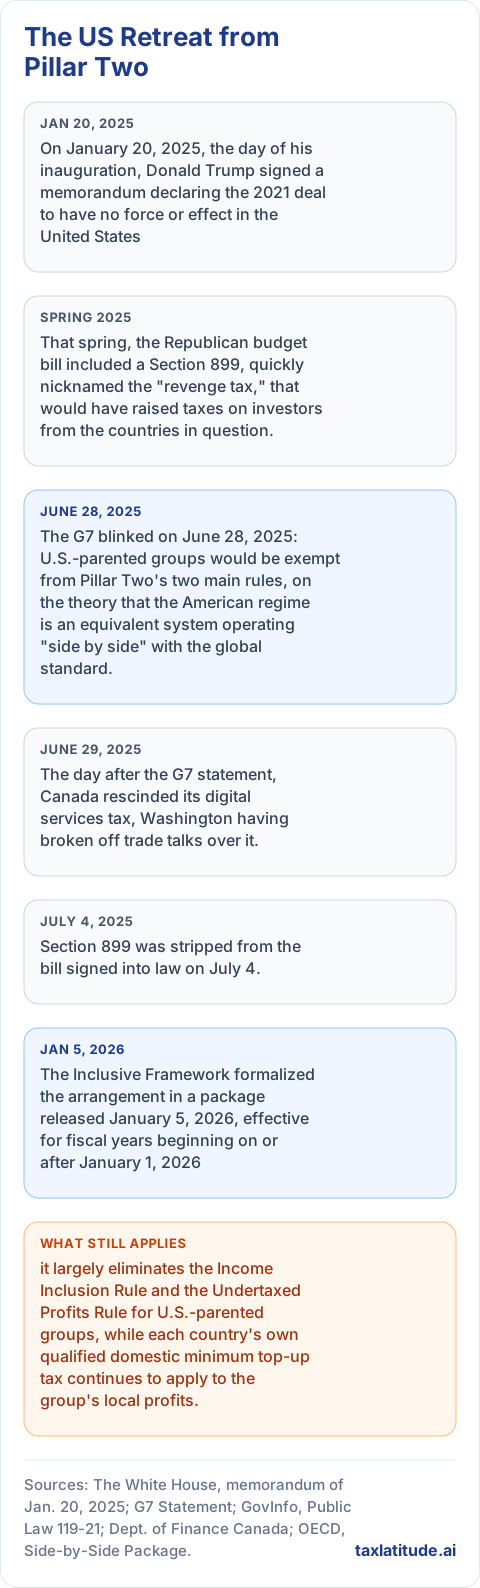
Congress never enacted Pillar Two. On January 20, 2025, the day of his inauguration, Donald Trump signed a memorandum declaring the 2021 deal to have no force or effect in the United States and ordering an inventory of possible retaliation against countries applying "extraterritorial" taxes to American companies. The memorandum was also published in the Federal Register. That spring, the Republican budget bill included a Section 899, quickly nicknamed the "revenge tax," that would have raised taxes on investors from the countries in question.
The G7 blinked on June 28, 2025: U.S.-parented groups would be exempt from Pillar Two's two main rules, on the theory that the American regime is an equivalent system operating "side by side" with the global standard. Section 899 was stripped from the bill signed into law on July 4. The day after the G7 statement, Canada rescinded its digital services tax, Washington having broken off trade talks over it. The Inclusive Framework formalized the arrangement in a package released January 5, 2026, effective for fiscal years beginning on or after January 1, 2026: it largely eliminates the Income Inclusion Rule and the Undertaxed Profits Rule for U.S.-parented groups, while each country's own qualified domestic minimum top-up tax continues to apply to the group's local profits. By October 2026, Japan and Liechtenstein had enacted it, Singapore's implementing bill had passed on October 6, 2026, and draft legislation implementing it was published in the U.K. on July 13, 2026, with similar bills moving through Germany, the Netherlands, Sweden, and France.
The episode says it all. The leverage that made FATCA possible, access to the U.S. market, is now being used to pull American champions out from under the common rule. European and Asian groups remain subject to a regime from which their main competitors are excused, and several capitals are asking how long a global standard can last without the world's largest economy.
How did the Global South change tables?
Meanwhile, the very legitimacy of the OECD, a club of rich countries writing rules for everyone, has come under attack. At the initiative of the Africa Group, the UN General Assembly voted in December 2023 to open negotiations on a framework convention on international tax cooperation, over the objections of nearly every OECD country. The resolution, 78/230, passed by 111 votes to 46 with 10 abstentions. The terms of reference were adopted in August 2024, and the negotiations began in 2025. By October 2026 they had reached their fifth of nine planned sessions, with the co-leads' first zero draft of the convention and of two early protocols — on cross-border services, and on dispute prevention and resolution — released in July 2026; a sixth session is scheduled for Nairobi from November 30 to December 11, 2026, with final texts due to go before the General Assembly by the end of 2027. The United States walked out at the organizational session in February 2025. Developing countries are pressing a long-standing demand: more rights to tax at source, particularly on services, under rules where one country means one vote. What remains to be seen is how much a convention would be worth if the main home countries of the multinationals declined to ratify it.
One last project got underway under Brazil's G20 presidency in 2024: taxing the ultra-wealthy. A report commissioned from Gabriel Zucman proposed a minimum tax of 2% of net worth on the world's roughly 3,000 billionaires, with an estimated yield of $200 billion to $250 billion. The finance ministers meeting in Rio went no further than a pledge to cooperate. Automatic exchange of information has made the idea technically conceivable. Politically, it has yet to clear a single legislature. In France, the proposal's own National Assembly passed a version of it on February 20, 2025, only for the Senate to reject it on June 12, 2025; the Assembly rejected it again, by 228 votes to 172, during the 2026 budget debate on October 31, 2025. Left-wing amendments reintroduced the same 2% levy on fortunes above €100 million into the 2027 budget bill; the National Assembly rejected them on October 16, 2026, by 70 votes to 35 — the third time in two years it has voted on it. No jurisdiction has yet enacted a billionaire wealth tax of this kind, though Brazil introduced a minimum tax of up to 10% on its own top earners' income in November 2025, and Brazil and Spain launched a joint voluntary initiative on taxing the super-rich in July 2025.
What is the scorecard: two fronts, two outcomes?
÷3 in ten years
Offshore financial wealth still equals about 10% of world GDP, but roughly three-quarters of it is now known to tax authorities — almost none was, before 2013.
~35% unchanged
About 35% of multinationals’ foreign profits were still shifted to tax havens in 2022 — roughly the same share as when the BEPS project began.
On individuals, the success is clear. The EU Tax Observatory estimates that offshore evasion has fallen by a factor of about three in ten years. Financial wealth held offshore still equals roughly 10% of world GDP, but about three-quarters of it is now known to tax authorities, compared with almost none before 2013. Blind spots remain: real estate, freeports, tax residencies of convenience, and the United States, which receives data without providing the equivalent in return.
On corporations, the verdict is harsh. The same observatory puts profits shifted to tax havens at close to $1 trillion in 2022, or about 35% of the profits multinationals book outside their home countries. That share has not fallen since BEPS was launched. Transparency has improved and the crudest structures have disappeared, but the accounting geography of profits has barely moved.
What is meant by a village without a town hall?
So "harmonization" is the wrong word. No rates have been unified and no common tax base exists, not even within the European Union, where the unanimity rule sank the consolidated tax base proposal of 2011, then the one from 2016, and now threatens their 2023 successor. What has been built is something else: an infrastructure of mutual surveillance, and a floor. Countries remain free to set their own tax policy, but they can no longer sell other governments' ignorance.
McLuhan's global village now exists in tax matters, in the sense that everyone in it can be seen by everyone else. What it lacks is a town hall. Its rules were written by the dominant power of the day, which exempts itself when they get in the way, and by a club the rest of the world rejects more and more openly. The century that four economists opened in 1923, worried that people might pay twice, is closing on the opposite question, still unresolved: how to make sure everyone pays at least once, and to whom.
Frequently asked questions
Is Swiss banking secrecy really over?
For foreigners, yes: Switzerland began automatic exchange of account information in 2018, after the U.S. Justice Department prosecuted Wegelin, extracted a $2.6 billion guilty plea from Credit Suisse and settled with some 80 other banks. Swiss residents, however, still keep banking secrecy with respect to their own tax authorities.
What is the difference between FATCA and CRS?
FATCA is a 2010 U.S. law that makes foreign banks report American account holders or face a 30% withholding tax, while CRS is the OECD's 2014 standard under which more than 100 jurisdictions exchange account data with each other automatically. The United States receives data under its own regime but does not provide the equivalent in return under CRS.
Why doesn't the global minimum tax apply to U.S. companies?
Congress never enacted Pillar Two, and after the January 20, 2025 presidential memorandum the G7 agreed on June 28, 2025 that U.S.-parented groups would be exempt from the Income Inclusion Rule and the Undertaxed Profits Rule, an arrangement the Inclusive Framework formalized in its early-2026 side-by-side package. The exemption covers those two rules, so a qualified domestic minimum top-up tax in a country where a U.S. group operates can still apply to its local profits.
Which companies have to pay the 15% global minimum tax?
Pillar Two applies to multinational groups with €750 million or more in annual revenue, which owe top-up tax wherever their effective rate in a country falls below 15%; the same €750 million threshold triggers country-by-country reporting under BEPS Action 13. Groups below that threshold are outside the rules, and a substance-based carve-out tied to payroll and tangible assets shields part of the profits of groups that are inside them.
Can anyone still look up who owns a company in the EU?
Not anymore: the Court of Justice ruled on November 22, 2022 that general public access to beneficial ownership registers was a disproportionate intrusion on privacy, so only people who can show a legitimate interest, such as journalists and NGOs, may now consult them. The United Kingdom's register, public since 2016, is outside EU law and was not affected by the ruling.
What is the UN tax convention and when will it be finished?
It is a framework convention on international tax cooperation that the UN General Assembly voted to negotiate in December 2023, at the initiative of the Africa Group, to give developing countries more rights to tax at source under one-country-one-vote rules. Negotiations began in 2025 and are scheduled to conclude in 2027, though the United States walked out and the main home countries of multinationals may decline to ratify the result.
When should you hire a professional?
The history in this guide becomes a practical question as soon as your own accounts, company, or residence sit across two or more of the regimes it describes, because the overlapping rules — and the exemptions carved out of them — do not resolve themselves.
- Accounts reported under both FATCA and CRS. A U.S. person living abroad, or a dual national with accounts in several countries, can be reported under two regimes with different definitions and thresholds, and needs someone to work out which reports go where and what each tax authority already knows.
- A business near the €750 million line. An owner or finance lead of a growing group needs advice on whether Pillar Two top-up tax, a local qualified domestic minimum top-up tax, or country-by-country reporting applies to the structure, since the thresholds are measured at group level and the safe harbours change year to year.
- A U.S.-parented group with foreign subsidiaries. The side-by-side exemption removes the Income Inclusion Rule and the Undertaxed Profits Rule but leaves domestic minimum taxes in place, so a professional is needed to model what the group still owes in each country where it operates.
- A beneficial ownership filing or access request. After the 2022 EU ruling and the March 2025 U.S. exemption, obligations to file ownership information and rights to see it differ by country, and someone setting up or acquiring an entity needs current, jurisdiction-specific advice.
- Moving assets to a reputed blind spot. Real estate, freeports, and some jurisdictions still fall outside automatic exchange, but holding assets there can trigger reporting duties, anti-avoidance rules, or criminal exposure at home, which calls for advice before any transfer.
A cross-border tax attorney fits questions of reporting exposure, beneficial ownership, and moving assets; an international tax specialist fits individuals juggling FATCA and CRS across several countries; and a corporate tax adviser with Pillar Two experience fits any group near or above the €750 million threshold.
Sources
All sources accessed October 16, 2026. Page dates are given only where the page showed one; otherwise the cell says so.
| Source | URL | Used for | Page date |
|---|---|---|---|
| Luigi Einaudi Foundation, League of Nations, Report on Double Taxation Submitted to the Financial Committee (Bruins, Einaudi, Seligman, Stamp) | https://www.luigieinaudi.it/pubblicazione/report-on-double-taxation-submitted-to-the-financial-committee/ | 1923 four-economist report | April 3, 1923 (report date) |
| UN Financing for Sustainable Development Office, Primer on double tax treaties | https://www.un.org/esa/ffd/capacity-development-tax/primer-dtt.html | More than 3,000 bilateral treaties | Not shown |
| OECD, Draft Double Taxation Convention on Income and Capital (1963) | https://www.oecd.org/en/publications/draft-double-taxation-convention-on-income-and-capital_9789264073241-en.html | 1963 OECD model treaty | 1963 (publication year) |
| United Nations, Model Double Taxation Convention between Developed and Developing Countries, 2017 Update | https://www.un.org/esa/ffd/wp-content/uploads/2018/05/MDT_2017.pdf | 1980 UN model favoring source countries | Not shown |
| Sébastien Guex, Business History Review 74(2), catalogued by Dodis | https://dodis.ch/15677 | Historians on origins of Swiss secrecy | 2000 (publication year) |
| LexFind, Bundesgesetz über die Banken und Sparkassen (Bankengesetz), SR 952.0 | https://www.lexfind.ch/tolv/251813/de | Federal Banking Act of November 8, 1934 | Not shown |
| swissinfo.ch, Banking secrecy between myth and reality (in French) | https://www.swissinfo.ch/fre/politique-suisse/le-secret-bancaire-entre-mythe-et-r%C3%A9alit%C3%A9/168226 | 1932 Paris affair and the 1934 law | February 27, 2009 |
| Tax Foundation, Corporate Tax Rates around the World, 2025 | https://taxfoundation.org/data/all/global/corporate-tax-rates-by-country-2025/ | Average corporate rate 1980 vs. today | Not recorded |
| OECD, Corporate Tax Statistics 2025: Statutory corporate income tax rates | https://www.oecd.org/en/publications/corporate-tax-statistics-2025_6a915941-en/full-report/statutory-corporate-income-tax-rates_c95f6f62.html | Official rate series (from 2000) | Not shown |
| Tørsløv, Wier and Zucman, The Missing Profits of Nations, NBER Working Paper 24701 | https://www.nber.org/papers/w24701 | Close to 40% of profits shifted | June 2018, revised April 2020 |
| Tørsløv, Wier and Zucman, missingprofits.world | https://missingprofits.world/ | Close to 40% of profits shifted | Not shown |
| Tørsløv, Wier and Zucman, The Missing Profits of Nations, Review of Economic Studies 90(3) | https://gabriel-zucman.eu/files/TWZ2023Restud.pdf | Peer-reviewed 36% figure | 2023 |
| OECD, Harmful Tax Competition: An Emerging Global Issue | https://www.oecd.org/en/publications/harmful-tax-competition_9789264162945-en.html | 1998 harmful tax competition report | Not shown |
| OECD, Towards Global Tax Co-operation | https://t4.oecd.org/tax/harmful/2090192.pdf | 2000 list of 35 tax havens | 2000 |
| EU Publications Office, ECOFIN Council conclusions and resolution on a code of conduct for business taxation | https://op.europa.eu/mt/publication-detail/-/publication/d2cdddef-e467-42d1-98c2-31b70e99641a | 1997 EU code of conduct | December 1, 1997 |
| EUR-Lex, Council Directive 2003/48/EC (Savings Directive) | https://eur-lex.europa.eu/eli/dir/2003/48/oj/eng | 2003 Savings Directive, interest only | Not shown |
| U.S. Treasury, Treasury Secretary O'Neill Statement on OECD Tax Havens (PO-366) | https://home.treasury.gov/news/press-releases/po366 | 2001 U.S. withdrawal of support | May 10, 2001 |
| NPR, German Tax-Evasion Scandal Stirs Outrage | https://www.npr.org/2008/02/28/19351580/german-tax-evasion-scandal-stirs-outrage | Zumwinkel raid and BND data purchase | February 28, 2008 |
| ICIJ, Whistleblower? Thief? Hero? Introducing the Source of the Data that Shook HSBC | https://www.icij.org/investigations/swiss-leaks/whistleblower-thief-hero-introducing-source-data-shook-hsbc/ | Falciani data reaching French authorities | February 8, 2015 |
| U.S. Department of Justice, Former UBS Banker Sentenced to 40 Months | https://www.justice.gov/archives/opa/pr/former-ubs-banker-sentenced-40-months-aiding-billionaire-american-evade-taxes | Bradley Birkenfeld | August 21, 2009 |
| U.S. Department of Justice, UBS Enters into Deferred Prosecution Agreement | https://www.justice.gov/opa/pr/2009/February/09-tax-136.html | UBS $780 million and client names | February 18, 2009 |
| G20 Research Group, London Summit – Leaders' Statement (Global Plan for Recovery and Reform) | https://g20.utoronto.ca/2009/2009communique0402.html | April 2, 2009 end of banking secrecy | April 2, 2009 |
| IRS, Summary of Key FATCA Provisions | https://www.irs.gov/node/6401 | FATCA 2010 and 30% withholding | Reviewed September 19, 2026 |
| IRS, Foreign Account Tax Compliance Act (FATCA) | https://www.irs.gov/Businesses/Corporations/Foreign-Account-Tax-Compliance-Act-FATCA | FATCA overview | Reviewed September 24, 2026 |
| OECD, Standard for Automatic Exchange of Financial Account Information in Tax Matters | https://www.oecd.org/en/publications/2014/07/standard-for-automatic-exchange-of-financial-account-information-in-tax-matters_g1g44cda.html | 2014 Common Reporting Standard | July 2014 |
| RegFollower, The Global Forum on Tax Transparency Holds 18th Plenary in India | https://regfollower.com/oecd-the-global-forum-on-tax-transparency-holds-18th-plenary-in-india/ | Jurisdiction and account counts under CRS | December 3, 2025 |
| Government of Luxembourg, FAQ on automatic exchange of information | https://gouvernement.lu/fr/actualites/toutes_actualites/communiques/2013/04-avril/10-finances.html | Luxembourg giving in during 2013 | April 10, 2013 (from URL path) |
| U.S. Attorney, Southern District of New York, Swiss Bank Pleads Guilty in Manhattan Federal Court | https://www.justice.gov/archive/usao/nys/pressreleases/January13/WegelinPleaPR.php | Wegelin guilty plea | January 3, 2013 |
| Reuters via Business Standard, Oldest private Swiss bank pleads guilty in US tax evasion case | https://www.business-standard.com/amp/article/international/oldest-private-swiss-bank-pleads-guilty-in-us-tax-evasion-case-113010300249_1.html | Wegelin closure | January 3, 2013 |
| U.S. Department of Justice, Credit Suisse Pleads Guilty | https://www.justice.gov/opa/pr/2014/May/14-ag-531.html | Credit Suisse $2.6 billion | May 19, 2014 |
| U.S. Department of Justice, Justice Department Reaches Final Resolutions Under Swiss Bank Program | https://www.justice.gov/opa/pr/justice-department-reaches-final-resolutions-under-swiss-bank-program | Some 80 Swiss banks settling | December 29, 2016 |
| Swiss Federal Council, First exchange of information on around 2 million financial accounts | https://admin.ch/gov/en/start/documentation/media-releases.msg-id-72420.html | Switzerland's first automatic exchanges in 2018 | Not recorded |
| ICIJ, Ten years exposing offshore tax havens' secrets | https://www.icij.org/investigations/offshore/ten-years-exposing-offshore-tax-havens-secrets/ | Offshore Leaks, 2013 | April 3, 2023 |
| ICIJ, About This Project: Luxembourg Leaks | https://www.icij.org/investigations/luxembourg-leaks/about-project-luxembourg-leaks/ | LuxLeaks, November 2014 | November 5, 2014 |
| ICIJ, Lux Leaks Confession: Jean-Claude Juncker Admits He Made 'Major Mistake' | https://www.icij.org/investigations/luxembourg-leaks/lux-leaks-confession-jean-claude-juncker-admits-he-made-major-mistake/ | LuxLeaks days after Juncker took office | May 7, 2019 |
| ICIJ, 100,000 Clients, $100 Billion: The Swiss Leaks Data | https://www.icij.org/investigations/swiss-leaks/100000-clients-100-billion-swiss-leaks-data/ | SwissLeaks, 2015 | February 8, 2015 |
| ICIJ, Panama Papers: About the Investigation | https://www.icij.org/investigations/panama-papers/pages/panama-papers-about-the-investigation/ | Panama Papers, April 2016 | Not shown (page returned an error) |
| ICIJ, ICIJ releases The Paradise Papers | https://www.icij.org/investigations/paradise-papers/icij-releases-paradise-papers/ | Paradise Papers, 2017 | November 5, 2017 |
| ICIJ, About the Pandora Papers | https://www.icij.org/inside-icij/2021/10/about-pandora-papers-investigation/ | Pandora Papers, 2021 | October 3, 2021 |
| NPR via GBH, Iceland's Prime Minister Steps Aside Amid Panama Papers Scandal | https://www.wgbh.org/news/2016-04-05/icelands-prime-minister-steps-aside-amid-panama-papers-scandal | Fall of Iceland's prime minister | April 5, 2016 |
| EY, Panama commits to implementing the OECD's Common Reporting Standard as of 2018 | https://taxnews.ey.com/news/2016-0724-panama-commits-to-implementing-the-oecds-common-reporting-standard-as-of-2018 | Panama's commitment to the CRS | April 20, 2016 |
| EUR-Lex, Council Directive (EU) 2015/2376 (DAC3) | https://eur-lex.europa.eu/eli/dir/2015/2376/oj/eng | Automatic exchange of tax rulings in the EU | Not shown |
| UK Parliament, Public Accounts Committee, HM Revenue and Customs: Annual Report and Accounts 2011-12 (HC 716) | https://api.parliament.uk/committees/publications/24928 | 2012 Hodge committee inquiry | December 3, 2012 |
| ITV News, Multinational bosses to face MPs over tax | https://itv.com/news/update/2012-11-12/multinational-bosses-to-face-mps-over-tax | Starbucks, Google, Amazon hearing | November 12, 2012 |
| OECD, Action Plan on Base Erosion and Profit Shifting | https://www.oecd.org/en/publications/action-plan-on-base-erosion-and-profit-shifting_9789264202719-en.html | July 2013 BEPS action plan | July 2013 (from URL path) |
| OECD, BEPS Project Explanatory Statement | https://www.oecd.org/content/dam/oecd/en/publications/reports/2016/08/beps-project-explanatory-statement_g1g6db07/9789264263437-en.pdf | 15 actions finalized October 2015 | Not shown |
| OECD, Harmful Tax Practices: Consolidated Peer Review Results on Preferential Regimes | https://www.oecd.org/content/dam/oecd/en/topics/policy-sub-issues/harmful-tax-practices/harmful-tax-practices-consolidated-peer-review-results-on-preferential-regimes.pdf | Review of more than 300 regimes | Not shown |
| KPMG, OECD update on preferential tax regimes (BEPS Action 5) | https://web.archive.org/web/20250907123058/https://kpmg.com/us/en/taxnewsflash/news/2025/02/tnf-oecd-preferential-tax-regimes-beps-action-5.html | Counts of regimes abolished or amended | February 6, 2025 |
| OECD, Preventing the Granting of Treaty Benefits in Inappropriate Circumstances, Action 6 – 2015 Final Report | https://www.oecd.org/en/publications/2015/10/preventing-the-granting-of-treaty-benefits-in-inappropriate-circumstances-action-6-2015-final-report_g1g5906e.html | Treaty anti-abuse minimum standard | October 2015 |
| OECD, Transfer Pricing Documentation and Country-by-Country Reporting, Action 13 – 2015 Final Report | https://www.oecd.org/en/publications/transfer-pricing-documentation-and-country-by-country-reporting-action-13-2015-final-report_9789264241480-en.html | Country-by-country reporting, €750 million | Not shown |
| OECD, BEPS Action 14 on More Effective Dispute Resolution – Peer Review Documents | https://www.oecd.org/content/dam/oecd/en/topics/policy-sub-issues/dispute-resolution/beps-action-14-on-more-effective-dispute-resolution-peer-review-documents.pdf | Dispute resolution minimum standard | Not shown |
| OECD, Inclusive Framework on BEPS Progress Report, July 2016–June 2017 | https://www.oecd.org/content/dam/oecd/en/publications/reports/2017/07/inclusive-framework-on-beps-progress-report-july-2016-june-2017_438b6d9f/60eb0b86-en.pdf | Inclusive Framework created in 2016 | July 2017 (from URL path) |
| OECD, Members of the OECD/G20 Inclusive Framework on BEPS | https://www.oecd.org/content/dam/oecd/en/topics/policy-issues/beps/inclusive-framework-on-beps-composition.pdf | More than 140 members | Updated December 5, 2025 |
| OECD, Signatories and Parties to the Multilateral BEPS Convention | https://www.oecd.org/content/dam/oecd/en/topics/policy-sub-issues/beps-mli/beps-mli-signatories-and-parties.pdf | Multilateral Instrument signed June 2017 | Not shown |
| OECD, Brazil signs the Multilateral BEPS Convention | https://www.oecd.org/en/about/news/announcements/2025/10/brazil-signs-the-multilateral-beps-convention-reducing-opportunities-for-tax-avoidance-by-multinational-enterprises.html | Treaties covered by the instrument | October 2025 |
| EUR-Lex, Council Directive (EU) 2016/1164 (Anti-Tax Avoidance Directive) | https://eur-lex.europa.eu/eli/dir/2016/1164/oj/eng | 2016 Anti-Tax Avoidance Directive | Not shown |
| EUR-Lex, Council Directive (EU) 2018/822 (DAC6) | https://eur-lex.europa.eu/eli/dir/2018/822/oj/eng | Mandatory disclosure by advisers | Not shown |
| EUR-Lex, Directive (EU) 2021/2101 (public country-by-country reporting) | https://eur-lex.europa.eu/eli/dir/2021/2101/oj/eng | Public country-by-country reporting | Not shown |
| Council of the EU, The EU list of non-cooperative jurisdictions for tax purposes (doc. 15429/17) | https://data.consilium.europa.eu/doc/document/ST-15429-2017-INIT/en/pdf | EU blacklist from December 2017 | December 5, 2017 |
| European Commission, State aid: Ireland gave illegal tax benefits to Apple worth up to €13 billion (IP/16/2923) | https://ec.europa.eu/commission/presscorner/api/files/document/print/en/ip_16_2923/IP_16_2923_EN.pdf | August 2016 Apple recovery order | August 30, 2016 |
| General Court of the EU, Press Release No 90/20 (Apple) | https://curia.europa.eu/jcms/jcms/p1_3116953 | 2020 annulment | July 15, 2020 |
| EUR-Lex, Case C-465/20 P, Commission v Ireland and Apple | https://eur-lex.europa.eu/eli/C/2024/6217/oj/eng | Court of Justice ruling, September 10, 2024 | September 10, 2024 (judgment date) |
| TechCentral.ie, Noonan announces end of Double Irish | https://www.techcentral.ie/noonan-announces-end-double-irish/ | Ireland shutting down the Double Irish | October 14, 2014 |
| Central Statistics Office (Ireland), Ireland's Economic Growth Figures | https://www.cso.ie/en/media/csoie/newsevents/documents/IrelandEconomicGrowthFigures.pdf | 26% GDP jump in 2015 | July 13, 2016 |
| Paul Krugman, post on X (Twitter), "Leprechaun economics" | https://twitter.com/paulkrugman/status/752841032870551552 | "Leprechaun economics" | July 12, 2016 |
| Financial Action Task Force, Beneficial Ownership | https://www.fatf-gafi.org/en/topics/beneficial-ownership.html | FATF push for ownership registries | Not shown |
| GOV.UK, 'People with Significant Control' Companies House register goes live | https://www.gov.uk/government/news/people-with-significant-control-companies-house-register-goes-live | UK public register in 2016 | June 30, 2016 |
| EUR-Lex, Directive (EU) 2015/849 (Fourth Anti-Money Laundering Directive), consolidated text | https://eur-lex.europa.eu/eli/dir/2015/849/2024-07-09 | 2015 EU registry mandate | July 9, 2024 (consolidation date) |
| EUR-Lex, Directive (EU) 2018/843 (Fifth Anti-Money Laundering Directive) | https://eur-lex.europa.eu/eli/dir/2018/843/oj/eng | 2018 EU registry mandate | Not shown |
| Court of Justice of the EU, Press Release No 188/22 (C-37/20 and C-601/20) | https://infocuria.curia.europa.eu/tabs/affair?sort=AFF_NUM-DESC&searchTerm=%2522C%252D37%252F20%2522&publishedId=C-37%2F20 | November 22, 2022 ruling on public access | November 22, 2022 |
| Federal Register (via GovInfo), FinCEN Beneficial Ownership Information Reporting Requirement Revision and Deadline Extension, 90 FR 13688 | https://www.govinfo.gov/content/pkg/FR-2025-03-26/html/2025-05199.htm | Corporate Transparency Act dates | March 26, 2025 |
| FinCEN, FinCEN Removes Beneficial Ownership Reporting Requirements for U.S. Companies and U.S. Persons | https://www.fincen.gov/news/news-releases/fincen-removes-beneficial-ownership-reporting-requirements-us-companies-and-us | March 2025 exemption | March 21, 2025 |
| French tax administration (impots.gouv.fr), English translation of Law No. 2019-759 of July 24, 2019 | https://www.impots.gouv.fr/sites/default/files/media/1_metier/5_international/french_dst_en_v2.pdf | France's 3% digital services tax | Not shown |
| USTR, Conclusion of USTR's Investigation Under Section 301 into France's Digital Services Tax | https://ustr.gov/about-us/policy-offices/press-office/press-releases/2019/december/conclusion-ustr%E2%80%99s-investigation | U.S. tariff threat | December 2, 2019 |
| Congress.gov, Public Law 115-97 (Tax Cuts and Jobs Act) | https://www.congress.gov/115/plaws/publ97/PLAW-115publ97.htm | 2017 Tax Cuts and Jobs Act | Not recorded |
| IRS, IRS and Treasury issue guidance related to global intangible low-taxed income (GILTI) | https://www.irs.gov/node/69096 | GILTI provision | June 14, 2019 |
| U.S. Treasury, Remarks by Secretary Janet L. Yellen to The Chicago Council on Global Affairs | https://home.treasury.gov/news/press-releases/jy0101 | April 2021 global minimum tax proposal | April 5, 2021 |
| U.S. Treasury, G7 Finance Ministers & Central Bank Governors Communiqué | https://home.treasury.gov/news/press-releases/jy0215 | June 2021 G7 London deal | June 5, 2021 |
| OECD, Statement on a Two-Pillar Solution to Address the Tax Challenges Arising from the Digitalisation of the Economy | https://www.oecd.org/content/dam/oecd/en/topics/policy-issues/beps/statement-on-a-two-pillar-solution-to-address-the-tax-challenges-arising-from-the-digitalisation-of-the-economy-october-2021.pdf | October 8, 2021 statement; Pillar One parameters | October 8, 2021 |
| OECD, Multilateral Convention to Implement Amount A of Pillar One | https://www.oecd.org/content/dam/oecd/en/topics/policy-issues/cross-border-and-international-tax/multilateral-convention-to-implement-amount-a-of-pillar-one.pdf | October 2023 draft convention | Not shown |
| OECD, Pillar One Update: Co-Chair Statement, Inclusive Framework on BEPS | https://www.oecd.org/content/dam/oecd/en/topics/policy-issues/beps/pillar-one-update-co-chair-statement-inclusive-framework-on-beps-january-2025.pdf | Pillar One status | January 2025 (from URL path) |
| OECD, Global Anti-Base Erosion Model Rules (Pillar Two) | https://www.oecd.org/en/publications/tax-challenges-arising-from-digitalisation-of-the-economy-global-anti-base-erosion-model-rules-pillar-two_782bac33-en.html | 15% minimum and Pillar Two mechanics | December 2021 |
| EUR-Lex, Council Directive (EU) 2022/2523 (Pillar Two Directive) | https://eur-lex.europa.eu/eli/dir/2022/2523/oj/eng | December 2022 EU adoption | Not shown |
| EY, EU Member States unanimously adopt Directive implementing Pillar Two | https://taxnews.ey.com/news/2022-1892-eu-member-states-unanimously-adopt-directive-implementing-pillar-two-global-minimum-tax-rules | Poland and Hungary vetoes | December 16, 2022 |
| Irish Statute Book, Finance (No. 2) Act 2023, section 95 | https://www.irishstatutebook.ie/2023/en/act/pub/0039/sec0095.html | Ireland implementing the minimum tax | Not shown |
| Swiss Federal Chancellery, Volksabstimmung vom 18. Juni 2023 | https://www.admin.ch/gov/de/start/dokumentation/abstimmungen/20230618.html | June 2023 Swiss referendum | June 18, 2023 (vote date) |
| Government of Bermuda, Tabling of the Corporate Income Tax Act 2023 | https://www.gov.bm/news/tabling-corporate-income-tax-act-2023 | Bermuda's 15% corporate income tax | Not shown |
| OECD, Summary of the Economic Impact Assessment of the Global Minimum Tax | https://www.oecd.org/content/dam/oecd/en/topics/policy-issues/cross-border-and-international-tax/summary-economic-impact-assessment-global-minimum-tax-january-2024.pdf | $155–192 billion revenue estimate | January 2024 |
| OECD, OECD publishes new analysis on the economic impacts of the global minimum tax | https://www.oecd.org/en/about/news/announcements/2026/07/oecd-publishes-new-analysis-on-the-economic-impacts-of-the-global-minimum-tax.html | 2026 update to revenue estimates | July 2026 (from URL path) |
| EU Tax Observatory, Global Tax Evasion Report 2024 | https://taxobservatory.world//www-site/uploads/2023/10/global_tax_evasion_report_24.pdf | Evasion and profit-shifting figures; Pillar Two loopholes | October 23, 2023 (release date) |
| The White House, The Organization for Economic Co-operation and Development (OECD) Global Tax Deal (Global Tax Deal) | https://www.whitehouse.gov/presidential-actions/2025/01/the-organization-for-economic-co-operation-and-development-oecd-global-tax-deal-global-tax-deal/ | January 20, 2025 memorandum | January 20, 2025 |
| Federal Register, memorandum of January 20, 2025, 90 FR 8483 | https://www.federalregister.gov/documents/full_text/text/2025/01/30/2025-02043.txt | Official publication of the memorandum | January 30, 2025 |
| Axios, 'Revenge tax' being yanked from 'big, beautiful bill,' Bessent says | https://www.axios.com/2025/06/26/trump-revenge-tax-budget | Section 899 and its removal | June 26, 2025 |
| G7 Research Group (University of Toronto), G7 Statement on Global Minimum Taxes | https://g7.utoronto.ca/finance/250628-tax-statement.html | June 28, 2025 side-by-side statement | June 28, 2025 |
| GovInfo, Public Law 119-21 | https://www.govinfo.gov/app/details/PLAW-119publ21 | Bill signed July 4, 2025 | July 4, 2025 (approval date) |
| Department of Finance Canada, Canada rescinds digital services tax to advance broader trade negotiations with the United States | https://www.canada.ca/en/department-finance/news/2025/06/canada-rescinds-digital-services-tax-to-advance-broader-trade-negotiations-with-the-united-states.html | Canada dropping its digital services tax | June 29, 2025 |
| OECD, Side-by-Side Package | https://www.oecd.org/content/dam/oecd/en/topics/policy-sub-issues/global-minimum-tax/side-by-side-package.pdf | January 5, 2026 formalization of the exemption | January 2026 |
| OECD, International community agrees way forward on global minimum tax package | https://www.oecd.org/en/about/news/press-releases/2025/12/international-community-agrees-way-forward-on-global-minimum-tax-package.html | Side-by-side agreement announcement | December 2025 (from URL path) |
| UN Meetings Coverage, Second Committee approves draft on international tax cooperation (GA/EF/3597) | https://press.un.org/en/2023/gaef3597.doc.htm | Africa Group initiative | Not recorded |
| UN Digital Library, General Assembly resolution 78/230 | https://digitallibrary.un.org/record/4032838 | December 2023 General Assembly vote | December 22, 2023 (adoption date) |
| UN DESA, Ad Hoc Committee: Terms of Reference for a UN Framework Convention on International Tax Cooperation | https://financing.desa.un.org/ad-hoc-committee-draft-terms-reference-united-nations-framework-convention-international-tax | August 2024 terms of reference | Not shown |
| UN DESA, Intergovernmental Negotiating Committee on the UN Framework Convention on International Tax Cooperation | https://financing.desa.un.org/unfcitc | Negotiation schedule and current status | Not shown |
| Eurodad, US walks out of tax convention | https://www.eurodad.org/us-walks-out-tax-convention | U.S. walkout | February 4, 2025 |
| Gabriel Zucman, A Blueprint for a Coordinated Minimum Effective Taxation Standard for Ultra-High-Net-Worth Individuals | https://gabriel-zucman.eu/files/report-g20.pdf | 2% billionaire minimum tax proposal | June 25, 2024 (executive summary date) |
| OECD, Statement by the OECD Secretary-General on the G20 tax declaration | https://www.oecd.org/en/about/news/press-releases/2024/07/statement-by-the-oecd-secretary-general-g20-tax-declaration.html | Rio pledge to cooperate | July 2024 (from URL path) |
| World and Japan database (University of Tokyo), Rio de Janeiro G20 Ministerial Declaration on International Tax Cooperation | https://worldjpn.net/documents/texts/G20/20240726.D3E.html | Full text of Rio declaration | July 26, 2024 (declaration date) |
| EUR-Lex, Summary: Common consolidated corporate tax base (2011 proposal) | https://eur-lex.europa.eu/EN/legal-content/summary/common-consolidated-corporate-tax-base.html | 2011 consolidated tax base proposal | Not shown |
| EUR-Lex, Procedure 2016/0336/CNS | https://eur-lex.europa.eu/procedure/EN/2016_336 | 2016 consolidated tax base proposal | Not shown |
| EUR-Lex, Procedure 2023/0321/CNS (BEFIT) | https://eur-lex.europa.eu/procedure/EN/2023_321 | 2023 successor proposal | Not shown |
| BDO, Pillar Two: Status of implementation around the world | https://www.bdo.global/en-gb/insights/tax/international-tax/pillar-two-updates-status-of-implementation-around-the-world | Mid-2026 count of more than 60 jurisdictions with rules in force | Not shown |
| Finn Accountings, UK Draft Law Implements OECD Pillar Two Side-by-Side Package for US-Parented Groups | https://www.finnaccountings.com/blog/uk-pillar-two-side-by-side-draft-legislation-july-2026 | UK draft legislation, July 13, 2026 | July 2026 |
| EY Global Tax News, UN releases draft Framework Convention on International Tax Cooperation and two early protocols | https://globaltaxnews.ey.com/news/2026-1618-un-releases-draft-framework-convention-on-international-tax-cooperation-and-two-early-protocols | July 2026 zero draft and Nairobi sixth session schedule | 2026 |
| Reporterre, 2026 budget: the Zucman tax rejected by the National Assembly (in French) | https://reporterre.net/Budget-2026-la-taxe-Zucman-rejetee-par-l-Assemblee-nationale | October 31, 2025 Assembly vote, 228-172 | October 31, 2025 |
| NosParlementaires, Zucman tax: who voted for what in the National Assembly ahead of the 2027 budget (in French) | https://nosparlementaires.fr/actualites/impot-plancher-2-ultrariches-taxe-zucman-parlement | 2027 budget bill reintroduction and October 16, 2026 votes | October 2026 |
| French National Assembly, analysis of roll-call vote No. 8859 (17th legislature) (in French) | https://www.assemblee-nationale.fr/dyn/17/scrutins/8859 | October 16, 2026 rejection of the 2% floor tax amendments, 70 votes to 35 | October 16, 2026 |
A note on scope: this article is general information, not tax or legal advice, and a history of the rules, not a guide to applying them to your own situation. Consult a qualified professional for any filing decision.