Key takeaways
- FATCA, enacted on March 18, 2010 as Title V of the HIRE Act (H.R. 2847), added Internal Revenue Code Sections 1471 through 1474, under which a foreign financial institution that does not agree to identify and report its U.S. accounts suffers a 30% withholding tax on U.S.-source payments.
- An individual must attach Form 8938 to the tax return under Section 6038D when specified foreign financial assets exceed $50,000 at year-end or $75,000 at any time (single filer living in the United States), or $200,000 and $300,000 for a single filer living abroad, with the thresholds doubled for married couples filing jointly.
- Form 8938 does not replace the FBAR (FinCEN Form 114), which is filed with FinCEN rather than the IRS whenever aggregate foreign accounts exceed $10,000 at any time in the year, so many Americans abroad file both.
- Failing to file Form 8938 costs $10,000, plus up to $50,000 more for continued failure after IRS notice under Section 6038D(d); understatements tied to undisclosed foreign assets carry a 40% accuracy penalty, and the assessment period stretches to six years under Section 6501(e).
- Most countries implement FATCA through a Model 1 intergovernmental agreement, under which banks report to their own tax authority, which forwards the data to the IRS.
- Banks that cannot obtain a U.S. taxpayer identification number for a preexisting account are protected only by temporary IRS relief in Notice 2024-78, which covers calendar years 2025 through 2027 and does not apply to new accounts; what happens after 2027 has not been announced, and whether EU data-protection law limits FATCA transfers is now before the Court of Justice of the European Union.
What are FATCA's origins, from an American oddity to a Swiss scandal?
To understand FATCA, start with an anomaly. The United States is, along with Eritrea, the only country that taxes its people based on citizenship rather than residence. The principle dates back to the Civil War-era revenue acts and was upheld by the Supreme Court in 1924 in Cook v. Tait: a U.S. citizen living in Mexico City, Paris, or Tokyo must report worldwide income to the Internal Revenue Service, no matter where they live or where the money was earned. For decades, the rule was largely theoretical. The IRS had no way of knowing what Americans were holding in a bank in Zurich or Singapore.
A first attempt at a fix, the Qualified Intermediary (QI) program, launched in 2001. It made foreign banks responsible for identifying clients who received U.S.-source income. The UBS affair would show just how easily it could be gamed, as the Justice Department's 2009 testimony to the Permanent Subcommittee on Investigations later laid out. In 2007, Bradley Birkenfeld, a private banker at UBS in Geneva, told U.S. authorities how Switzerland's largest bank courted wealthy Americans and helped them hide assets behind shell structures. Around the same time, the LGT scandal erupted in Liechtenstein after stolen client data was sold to several Western tax agencies. In July 2008, the Senate Permanent Subcommittee on Investigations, chaired by Democrat Carl Levin, released a scathing report estimating that offshore evasion cost the Treasury roughly $100 billion a year.
The rest is well known. In February 2009, UBS entered into a deferred prosecution agreement, paid $780 million, and handed over client names. A deal between Bern and Washington that August expanded the disclosure to roughly 4,450 accounts. Swiss banking secrecy had cracked. Birkenfeld went to prison, then collected a $104 million whistleblower award in 2012. But Congress drew a different lesson: you can't prosecute banks one at a time. You need a system.
How did this law hitch a ride?
The bill was introduced in October 2009 by Rep. Charles Rangel and Sen. Max Baucus, with the Obama administration's backing. It never got a debate of its own. FATCA was enacted on March 18, 2010, as Title V of the HIRE Act (Hiring Incentives to Restore Employment Act), a jobs bill for which it served as the pay-for: the Joint Committee on Taxation projected about $8.7 billion in revenue over ten years, a figure cited in the Senate Finance Committee's summary of the final bill and in TIGTA's 2022 report. A modest sum, given the upheaval that followed.
Legally, the statute added Chapter 4 to the Internal Revenue Code (Sections 1471 through 1474) and, through Section 6038D, created a new reporting requirement for individuals. It took the IRS and Treasury nearly three years to write the instruction manual: the final regulations (T.D. 9610), running several hundred pages, came out in January 2013. The effective date, originally set for early 2013, was pushed back twice, to July 1, 2014, the last time by IRS Notice 2013-43.
What is the core mechanism: the 30% withholding tax?
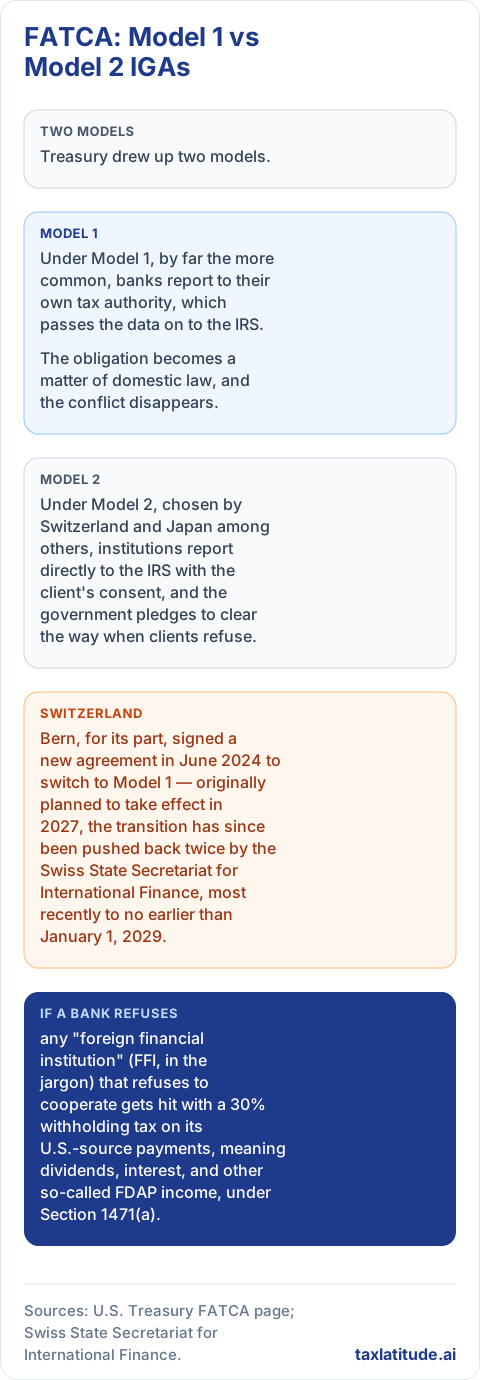
FATCA's genius, and its bluntness, comes down to one simple idea. Washington has no authority over a bank in Lyon or Kuala Lumpur. But it does control access to the world's largest financial market. So the law offers a deal: any "foreign financial institution" (FFI, in the jargon) that refuses to cooperate gets hit with a 30% withholding tax on its U.S.-source payments, meaning dividends, interest, and other so-called FDAP income, under Section 1471(a). The original statute also reached gross proceeds from sales of U.S. securities (Section 1473(1)); that piece, delayed again and again, was dropped in proposed regulations in late 2018.
The definition of a financial institution is sweeping: banks, custodians, and brokers, but also investment funds, certain life insurers, asset managers, and many trusts and holding companies, as set out in the Chapter 4 regulations. For any player of meaningful size, walking away from U.S. markets is unthinkable. The threat has almost never had to be carried out. It was enough that it existed.
To avoid the tax, an institution registers with the IRS, which issues it a 19-character identifier known as a GIIN (Global Intermediary Identification Number), published on a list that withholding agents check. Several hundred thousand entities worldwide now appear on it. The institution then commits to three things: identifying its American clients, reporting their accounts every year, and appointing a responsible officer who periodically certifies compliance, the core terms of an FFI agreement under Section 1471(b).
What does hunting for "U.S. indicia" involve?
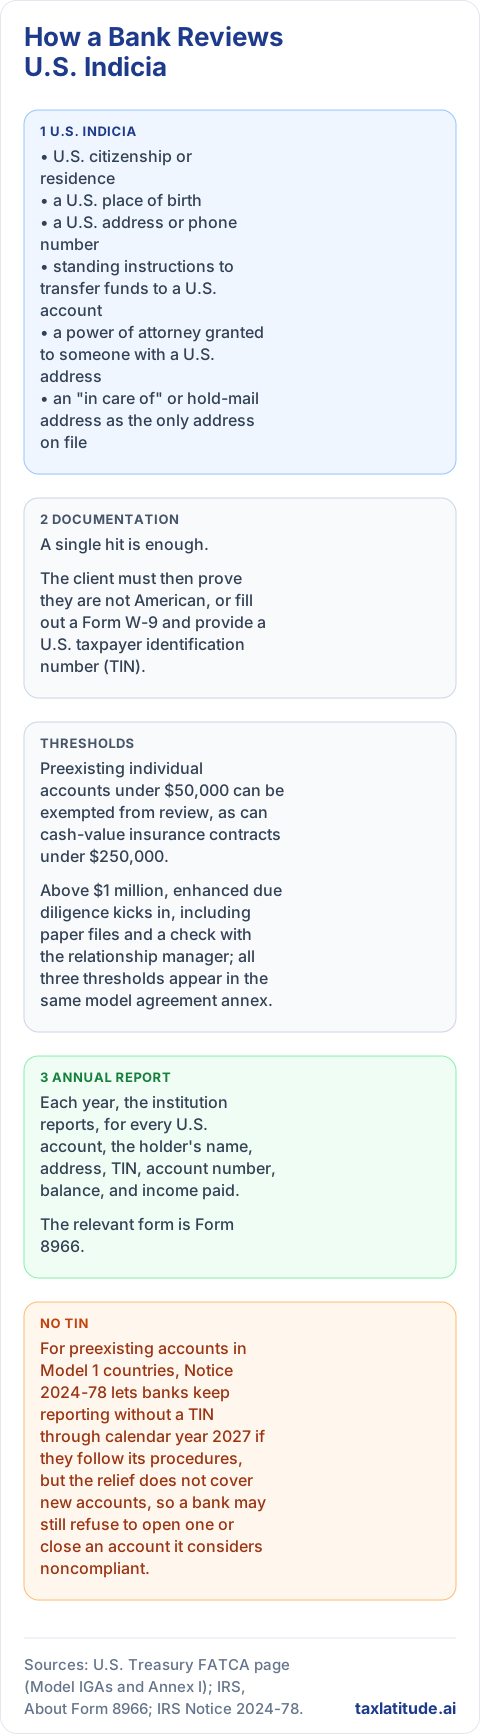
Identification runs on a checklist of indicators that banks must search for in their records, set out in Annex I of the model intergovernmental agreements: U.S. citizenship or residence, a U.S. place of birth, a U.S. address or phone number, standing instructions to transfer funds to a U.S. account, a power of attorney granted to someone with a U.S. address, or an "in care of" or hold-mail address as the only address on file. A single hit is enough. The client must then prove they are not American, or fill out a Form W-9 and provide a U.S. taxpayer identification number (TIN).
Thresholds lighten the load. Preexisting individual accounts under $50,000 can be exempted from review, as can cash-value insurance contracts under $250,000. Above $1 million, enhanced due diligence kicks in, including paper files and a check with the relationship manager; all three thresholds appear in the same model agreement annex. For entities, the law looks through the structure: a "passive" foreign company, one whose income is mostly investment income, must disclose its substantial U.S. owners, defined as more than 10% in the statute (Section 1473(2)) and generally 25% under the bilateral agreements. The point is to make sure a Panamanian shell is no longer enough to make a taxpayer vanish.
Each year, the institution reports, for every U.S. account, the holder's name, address, TIN, account number, balance, and income paid. The relevant form is Form 8966.
What is the individual side: Form 8938?
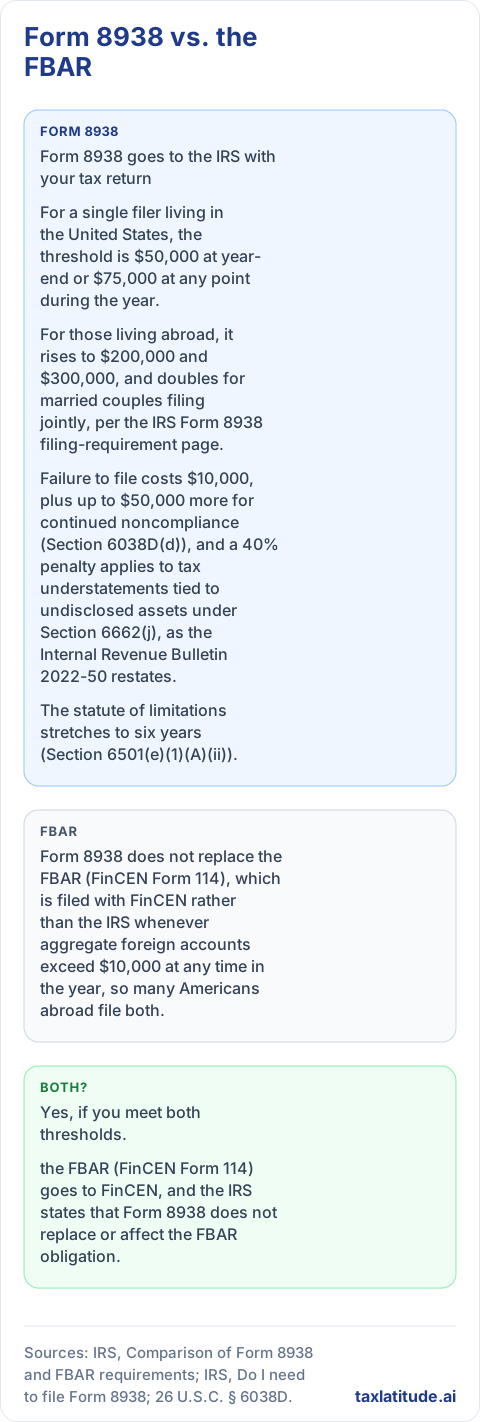
It's often forgotten that FATCA also lands directly on taxpayers. Any "U.S. person" holding foreign financial assets above certain thresholds must itemize them on Form 8938, attached to their tax return, as required by Section 6038D. For a single filer living in the United States, the threshold is $50,000 at year-end or $75,000 at any point during the year. For those living abroad, it rises to $200,000 and $300,000, and doubles for married couples filing jointly, per the IRS Form 8938 filing-requirement page. Failure to file costs $10,000, plus up to $50,000 more for continued noncompliance (Section 6038D(d)), and a 40% penalty applies to tax understatements tied to undisclosed assets under Section 6662(j), as the Internal Revenue Bulletin 2022-50 restates. The statute of limitations stretches to six years
Not sure if you've crossed the Form 8938 threshold? For Americans abroad it's $200,000 at year-end or $300,000 at any point in the year — miss it and the IRS gets six years to assess the $10,000+ penalty, not the usual three. Check your own thresholds and exposure →
(Section 6501(e)(1)(A)(ii)).This requirement sits on top of, and does not replace, the FBAR filing inherited from the Bank Secrecy Act of 1970, which is triggered at $10,000 in aggregate foreign holdings and goes not to the IRS but to FinCEN, as the IRS comparison of Form 8938 and FBAR requirements spells out. This site's full FBAR guide covers the mechanics and the 2026 penalty rules in more detail. Two forms, two agencies, two penalty regimes for largely overlapping information: tax lawyers who specialize in this area have never lacked for work. Matching what the taxpayer reports against what the bank reports is the heart of the system.
What are the legal problem and the intergovernmental workaround?
An obstacle emerged quickly. In most countries, sending client-level data straight to a foreign tax authority violates bank secrecy laws, data protection laws, or both. European banks found themselves caught between American penalties and penalties at home.
The solution was diplomatic. On February 8, 2012, France, Germany, Italy, Spain, and the United Kingdom issued a joint statement with Washington paving the way for intergovernmental agreements, or IGAs. Treasury drew up two models. Under Model 1, by far the more common, banks report to their own tax authority, which passes the data on to the IRS. The obligation becomes a matter of domestic law, and the conflict disappears. Under Model 2, chosen by Switzerland and Japan among others, institutions report directly to the IRS with the client's consent, and the government pledges to clear the way when clients refuse. Bern, for its part, signed a new agreement in June 2024 to switch to Model 1 — originally planned to take effect in 2027, the transition has since been pushed back twice by the Swiss State Secretariat for International Finance, most recently to no earlier than January 1, 2029.
The UK signed first, in September 2012. More than 110 jurisdictions followed, as the Treasury's table of FATCA agreements shows. France signed a "reciprocal" Model 1 agreement on November 14, 2013, ratified by statute in September 2014 (loi n° 2014-1098 of September 29, 2014); its tax authority made its first transmissions in 2015. India signed its own FATCA agreement, and Indian banks now report US-person accounts to the IRS under it. New Zealand's FATCA agreement with the US entered into force on July 3, 2014. South Korea's Model 1 IGA has been in force since September 8, 2016. Georgia signed its own Model 1 IGA on July 10, 2015, in force since September 18, 2015. The Philippines signed its Model 1 IGA on July 13, 2015. Malaysia's Model 1 IGA was signed July 21, 2021 and entered into force October 3, 2022.
Is reciprocity in name only?
That word "reciprocal" deserves a closer look. Under Model 1A agreements, the United States commits to sharing information on accounts held at American institutions by residents of the partner country. But the scope is far narrower: no account balances, no identification of beneficial owners behind entities, coverage limited to certain types of income. The agreements include a political commitment by Washington to pursue equivalent reciprocity, which would take an act of Congress; the text of the reciprocal model is published on Treasury's FATCA page. It never came. A French parliamentary report said as much bluntly in 2019, and the European Parliament had already adopted a resolution in July 2018 condemning the law's effects.
The paradox deepened with FATCA's own success. In 2014, the OECD adopted the Common Reporting Standard (CRS), a multilateral carbon copy of the American system, based on residence rather than citizenship and now applied by more than 100 jurisdictions, with the first exchanges in 2017. The United States never joined, arguing it already has FATCA. The result: the country that tore down everyone else's banking secrecy has become one of the few places where a nonresident can still park assets quietly, notably through trusts in South Dakota, Nevada, or Delaware. In 2022, the Tax Justice Network ranked it first on its Financial Secrecy Index.
What is the collateral damage for expats and "accidental Americans"?
Designed to catch wealthy tax cheats living in the United States, the law has mostly upended the lives of millions of ordinary Americans living overseas. To a foreign bank, an American client became a cost and a liability. Many chose to close accounts, deny mortgages, or block access to investment products, problems the European Parliament's 2018 resolution documented.
The hardest cases are the so-called accidental Americans: people born on U.S. soil while their parents happened to be posted there, who left as infants, have no ties to the country, and sometimes don't even know they hold citizenship. To FATCA, a U.S. birthplace is an indicator like any other. Boris Johnson, born in New York, was the most famous example: pursued by the IRS over the capital gain on his London home, he renounced his U.S. citizenship in 2016. In France, the Association of Accidental Americans, founded in 2017 by Fabien Lehagre, puts their number in the tens of thousands. Its legal challenge to the Franco-American agreement was rejected by the Conseil d'État, France's highest administrative court, in July 2019 (CE, July 19, 2019, n° 424216).
Getting out is expensive. Renouncing citizenship means being current on five years of tax filings (Section 877(a)(2)(C)), paying a consular fee that was raised to $2,350 in 2014 and then cut back to $450 — the level it held from 2010 to 2014 — by a State Department final rule effective April 13, 2026, after a six-year legal fight led by the Association of Accidental Americans, and, for those with a net worth above $2 million, facing an exit tax (Section 877(a)(2)(B), applied through Section 877A — see TaxLatitude's guide to the US exit tax for how that calculation works). Renunciations, which numbered a few hundred a year before 2010, topped 5,000 in 2016 and hit a record of about 6,700 in 2020.
Considering renouncing U.S. citizenship to get out of FATCA? The consular fee just dropped back to $450, but you still have to certify five years of tax compliance first, and a net worth above $2 million triggers the separate exit tax. Find out if the exit tax would apply to you →
In 2019, the IRS introduced relief procedures for certain former citizens with modest income and assets.One technical problem captures the absurdity of some of these situations. Banks are required to report a TIN that accidental Americans don't have, since they never applied for a Social Security number.
Has your bank asked you for a U.S. taxpayer ID number you don't have? The IRS's TIN relief for banks only covers 2025 through 2027 and only for existing accounts — it doesn't resolve your own filing obligation or get you a Social Security number. Sort out what you actually need to file →
Faced with the prospect of mass account closures, flagged by European banking federations, the IRS has granted a series of grace periods through notices issued in 2017 (Notice 2017-46), 2023 (Notice 2023-11), and late 2024 (Notice 2024-78), the last covering calendar years 2025 through 2027. A temporary fix that keeps getting renewed. TaxLatitude's full story of the accidental Americans covers the legal fight over this in more detail, including the case now before the EU's top court.What is the courtroom front and GDPR?
In the United States, the constitutional challenge fizzled. Crawford v. Department of the Treasury, in which Sen. Rand Paul was a plaintiff, was dismissed for lack of standing (868 F.3d 438, 6th Cir. 2017), and the Supreme Court declined to take it up in 2018 (No. 17-911). In Canada, challenges under the Charter of Rights and Freedoms failed at every level.
In Europe, the fight has shifted to data protection. The argument turns on proportionality: the automatic, bulk transfer of data on people who overwhelmingly owe no U.S. tax would violate the General Data Protection Regulation, particularly since the EU's Court of Justice has toughened its stance on data transfers to the United States. Belgium's data protection authority ruled along those lines in May 2023. Its decision was overturned on procedural grounds by the Brussels Market Court, and the authority ruled on the merits again on April 24, 2025, finding the transfers incompatible with the GDPR and giving Belgium's tax administration until April 24, 2026 to bring them into compliance (Decision 79/2025). The Brussels Market Court referred the dispute onward, and the Court of Justice of the European Union registered it on December 10, 2025 as Case C-804/25, with thirteen questions on FATCA's compatibility with the GDPR now pending before Europe's top court. No judgment has been issued yet, but a ruling against FATCA there would be the first serious breach in the structure.
An Awkward Bottom Line
That leaves the question any auditor would ask: what does it actually bring in? The answer is uncomfortable. The Treasury Inspector General for Tax Administration (TIGTA) found in 2018 that the IRS had spent nearly $380 million on FATCA without building a real enforcement program around it. Then, in 2022, that the tab had reached $574 million against directly attributable revenue of around $14 million. The data comes in, often without a usable TIN, and the agency struggles to match it to tax returns. On the private-sector side, compliance costs run into the billions of dollars globally, far beyond the $8.7 billion in ten-year revenue Congress was promised.
The law's defenders counter that its real payoff is indirect: deterrence. The voluntary disclosure programs that ran from 2009 to 2018 brought in more than $11 billion, and tens of thousands of taxpayers came clean for fear their bank would report them first. It's a fair point, but it's hard to separate FATCA's effect from that of the criminal cases against Swiss banks, from Credit Suisse's guilty plea in 2014 to the collapse of Wegelin, the country's oldest bank.
What Now?
Outright repeal, which made it into the Republican platform in 2016, has never gained real traction: no Congress wants to look like it's protecting tax cheats. The debate has moved to the root cause, citizenship-based taxation. During the 2024 campaign, Donald Trump promised to end "double taxation" of Americans abroad, and a bill to establish residence-based taxation (H.R. 10468) was introduced in the House in late 2024 by Rep. Darin LaHood. It expired, unpassed, with the end of that Congress in January 2025 — under ordinary congressional procedure, a bill that has not passed both chambers dies at the end of its two-year term and must be reintroduced from scratch. If a successor bill is reintroduced and eventually passed, FATCA would lose most of its grip on expats without going away.
Because the law's legacy goes beyond its stated purpose. FATCA proved that a power with enough financial leverage can impose its rules on the world without a multilateral treaty or anyone's prior consent. It also made the idea of automatic, global exchange of bank data first thinkable, then routine. Banking secrecy died from a revenue offset in a jobs bill that almost nobody read. The rest of that story — CRS, BEPS, the global minimum tax, and the American retreat from it — is told in the wider history of international tax cooperation.
A note on scope: this article is general information, not tax or legal advice. FATCA obligations, thresholds and penalties depend on your own facts — account values, filing status, and which forms already apply to you. Consult a qualified professional before acting on your own reporting position.
Frequently asked questions
Do I have to file Form 8938 if I already file an FBAR?
Yes, if you meet both thresholds. Form 8938 goes to the IRS with your tax return, while the FBAR (FinCEN Form 114) goes to FinCEN, and the IRS states that Form 8938 does not replace or affect the FBAR obligation. See our full Form 8938 vs. FBAR comparison, with a worked example, for the detail.
What is the Form 8938 threshold for Americans living abroad?
A single filer living abroad must file when specified foreign financial assets exceed $200,000 on the last day of the year or $300,000 at any time during the year; married couples filing jointly use double those amounts, according to the IRS Form 8938 filing-requirement page.
Why is my foreign bank asking whether I am a U.S. citizen?
Under FATCA, banks must search their records for U.S. indicia such as a U.S. place of birth, address, or phone number; a single indicator means you must either document that you are not a U.S. person or provide a Form W-9 with a U.S. taxpayer identification number.
What happens if I can't give my bank a U.S. TIN?
For preexisting accounts in Model 1 countries, Notice 2024-78 lets banks keep reporting without a TIN through calendar year 2027 if they follow its procedures, but the relief does not cover new accounts, so a bank may still refuse to open one or close an account it considers noncompliant.
What is the penalty for not filing Form 8938?
The base penalty is $10,000, with up to $50,000 more if you keep failing to file after IRS notice under Section 6038D(d), plus a 40% accuracy penalty on any tax understatement tied to undisclosed foreign assets and a six-year assessment period.
Does renouncing U.S. citizenship end FATCA reporting?
Once loss of citizenship is effective, you are no longer a U.S. person for FATCA purposes, but you must certify five years of tax compliance under Section 877(a)(2)(C), and a net worth of $2 million or more brings the exit tax into play; the IRS relief procedures for certain former citizens exist for people with modest income and assets who fell behind non-willfully.
When should you hire a professional?
FATCA links what your bank reports with what you report yourself, so any gap between the two, or any decision that cannot easily be undone, calls for a specialist.
- Accidental American getting compliant. Catching up on years of unfiled returns, FBARs, and Form 8938 involves choosing among IRS compliance programs, and the wrong choice can expose you to penalties that the right one avoids.
- Account closure over a missing TIN. When a bank threatens to close an account because you have no U.S. taxpayer identification number, a professional can obtain the number and sequence the filings so the fix does not trigger new exposure.
- Weighing renunciation. Renouncing requires certifying five years of compliance and may trigger the exit tax, and the decision is effectively irreversible, so it calls for modeling before any appointment at a consulate.
- IRS notice of a Form 8966 and Form 8938 mismatch. A letter showing that your bank reported an account you did not disclose starts a clock on penalties, and how you respond shapes whether the case stays civil.
- Entity owner with substantial-U.S.-owner disclosure. Holding companies, trusts, and investment entities can be passive foreign entities that must disclose U.S. owners above the 10% or 25% line, and classifying them correctly takes technical analysis.
A tax attorney fits anything with real penalty or enforcement exposure, such as a mismatch notice, unfiled years that may look willful, or a renunciation with exit-tax consequences, while a CPA or enrolled agent experienced with expatriate returns fits routine annual compliance on Form 8938, the FBAR, and the related filings.
Sources
All sources accessed October 16, 2026. Page dates are given only where the page showed one; otherwise the cell says so.
| Source | URL | Used for | Page date |
|---|---|---|---|
| 26 U.S.C. § 1471 | https://www.law.cornell.edu/uscode/text/26/1471 | 30% withholding; FFI agreement terms | Not shown |
| 26 U.S.C. § 1473 | https://www.law.cornell.edu/uscode/text/26/1473 | Withholdable payments; 10% substantial U.S. owner | Not shown |
| 26 U.S.C. § 1474 | https://www.law.cornell.edu/uscode/text/26/1474 | Chapter 4 span (Sections 1471–1474) | Not shown |
| 26 U.S.C. § 6038D | https://www.law.cornell.edu/uscode/text/26/6038D | Individual reporting; $10,000 and $50,000 penalties | Not shown |
| 26 U.S.C. § 6501 | https://www.law.cornell.edu/uscode/text/26/6501 | Six-year assessment period | Not shown |
| 26 U.S.C. § 877 | https://www.law.cornell.edu/uscode/text/26/877 | Five-year certification; $2 million net worth test | Not shown |
| 26 CFR § 1.1471-1 | https://www.law.cornell.edu/cfr/text/26/1.1471-1 | Chapter 4 definitions, including financial institutions | Not shown |
| H.R. 2847, 111th Congress | https://www.congress.gov/bill/111th-congress/house-bill/2847 | HIRE Act bill record | Not recorded |
| Public Law 111-147 (HIRE Act) | https://www.govinfo.gov/content/pkg/PLAW-111publ147/html/PLAW-111publ147.htm | Enactment on March 18, 2010 | Not shown |
| Senate Finance Committee, Baucus release on final HIRE Act passage | https://finance.senate.gov/chairmans-news/baucus-hails-final-passage-of-job-creation-legislation | $8.7 billion ten-year revenue estimate | Not recorded |
| House Ways and Means Democrats, HIRE Act summary (PDF) | https://democrats-waysandmeans.house.gov/sites/evo-subsites/democrats-waysandmeans.house.gov/files/media/pdf/111/HR2847_HireAct.pdf | 2009 Rangel–Baucus FATCA bill | Not shown |
| Cook v. Tait, 265 U.S. 47 (1924) | https://www.govinfo.gov/app/details/USREPORTS-265/USREPORTS-265-47 | Citizenship-based taxation upheld | May 5, 1924 (decision date) |
| Crawford v. U.S. Dept. of the Treasury, 868 F.3d 438 (6th Cir. 2017) | https://www.leagle.com/decision/infco20170818139 | Dismissal for lack of standing | August 18, 2017 (decision date) |
| Crawford cert. petition, Supreme Court No. 17-911 | https://www.supremecourt.gov/DocketPDF/17/17-911/24702/20171221104513422_Crawford%20v%20US%20Dept%20Treasury%20cert%20ptn%20-%20final.pdf | Supreme Court petition | December 2017 |
| Stikeman Elliott via Mondaq, "U.S. Supreme Court Refuses To Hear Challenge To FATCA" | https://mondaq.com/unitedstates/tax-authorities/718484/us-supreme-court-refuses-to-hear-challenge-to-fatca | Cert denial date; 2016 Republican platform (secondary) | July 24, 2018 |
| TIGTA Report 2018-30-040 | https://www.oversight.gov/sites/default/files/oig-reports/201830040fr.pdf | Nearly $380 million spent | July 5, 2018 |
| TIGTA Report 2022-30-019 | https://www.tigta.gov/sites/default/files/reports/2025-08/202230019fr.pdf | $574 million cost; $14 million revenue; $8.7 billion JCT estimate | April 7, 2022 |
| IRS Notice 2024-78 | https://irs.gov/pub/irs-drop/n-24-78.pdf | TIN relief for 2025–2027 | Not shown |
| IRS Notice 2023-11 | https://irs.gov/pub/irs-drop/n-23-11.pdf | TIN relief for 2022–2024 | Not shown |
| IRS Notice 2017-46 | https://www.irs.gov/pub/irs-drop/n-17-46.pdf | First TIN relief notice | Not recorded |
| IRS Notice 2013-43 | https://www.irs.gov/pub/irs-drop/n-13-43.pdf | Effective date moved to July 1, 2014 | Not shown |
| T.D. 9610, 78 Fed. Reg. 5874 | https://govinfo.gov/link/fr/78/5985 | January 2013 final regulations | January 28, 2013 |
| REG-132881-17, 83 Fed. Reg. 64757 | https://www.govinfo.gov/content/pkg/FR-2018-12-18/html/2018-27290.htm | Gross-proceeds withholding dropped | December 18, 2018 |
| IRS, "Do I need to file Form 8938" | https://www.irs.gov/node/4675 | Form 8938 thresholds | Not shown |
| IRS, Comparison of Form 8938 and FBAR requirements | https://www.irs.gov/businesses/comparison-of-form-8938-and-fbar-requirements | FBAR vs. Form 8938; FinCEN filing | Not shown |
| Internal Revenue Bulletin 2022-50 | https://www.irs.gov/irb/2022-50_IRB | 40% penalty under Section 6662(j) | Not recorded |
| IRS, About Form 8966 | https://www.irs.gov/form8966 | Institutional FATCA reporting form | Not shown |
| IRS, GIIN Composition (PDF) | https://www.irs.gov/pub/fatca/giin_composition.pdf | 19-character GIIN | Not shown |
| FinCEN, Report of Foreign Bank and Financial Accounts | https://www.fincen.gov/report-foreign-bank-and-financial-accounts | FBAR under the Bank Secrecy Act | Not recorded |
| U.S. Treasury, Foreign Account Tax Compliance Act page | https://home.treasury.gov/policy-issues/tax-policy/foreign-account-tax-compliance-act | Model IGAs and Annex I; table of agreements | Not shown |
| UK Government, Joint Statement on an Intergovernmental Approach to FATCA | https://www.gov.uk/government/news/joint-statement-regarding-an-intergovernmental-approach-to-improving-international-tax-compliance-and-implementing-fatca | February 8, 2012 joint statement | February 8, 2012 |
| Swiss Federal Council press release on new FATCA agreement | https://admin.ch/gov/en/start/documentation/media-releases.msg-id-101674.html | June 2024 Model 1 agreement; 2027 plan | June 27, 2024 |
| Swiss State Secretariat for International Finance, FATCA agreement page | https://www.sif.admin.ch/en/fatca-agreement | Delayed entry into force (now 2029) | Not shown |
| KPMG TaxNewsFlash, Switzerland Model 1 transition delayed until 2029 | https://kpmg.com/us/en/taxnewsflash/news/2026/07/tnf-switzerland-model-1-fatca-iga-transition-delayed-again-until-2029.html | 2029 transition date (secondary) | July 23, 2026 |
| BOFiP-Impôts, Accord FATCA France–États-Unis | https://bofip.impots.gouv.fr/bofip/10240-PGP | November 14, 2013 signing; loi n° 2014-1098 | Not recorded |
| Assemblée nationale, written question 7365 and answer | https://www.assemblee-nationale.fr/dyn/15/questions/QANR5L15QE7365.pdf | Annual France–U.S. exchanges | Not recorded |
| European Parliament Legislative Observatory, 2018/2646(RSP) | https://oeil.europarl.europa.eu/oeil/en/document-summary?id=1544912 | July 2018 resolution on FATCA | July 5, 2018 (text adopted) |
| OECD, first automatic CRS exchanges | https://web.archive.org/web/20231005001320/https://www.oecd.org/tax/automatic-exchange/news/first-automatic-crs-exchanges-between-49-jurisdictions-to-take-place-over-2000-bilateral-exchange-relationships-in-place.htm | CRS approved 2014; first exchanges 2017; 100+ jurisdictions | September 14, 2017 |
| Tax Justice Network, Financial Secrecy Index 2022 (Taxcast) | https://taxjustice.net/2022/05/18/the-financial-secrecy-index-2022-in-the-tax-justice-network-podcast-the-taxcast/ | United States ranked first in 2022 | May 18, 2022 |
| Senate PSI staff report, Tax Haven Banks and U.S. Tax Compliance | https://www.hsgac.senate.gov/imo/media/doc/071708PSIReport.pdf | $100 billion annual loss estimate; UBS and LGT | July 17, 2008 |
| U.S. DOJ, Statement of John DiCicco to the PSI | https://www.justice.gov/file/453276/dl | UBS and the Qualified Intermediary agreement | Not shown |
| U.S. DOJ, UBS deferred prosecution agreement release | https://www.justice.gov/opa/pr/2009/February/09-tax-136.html | February 2009 DPA; $780 million | Not shown |
| U.S. DOJ, results of UBS settlement | https://www.justice.gov/archives/opa/pr/justice-department-irs-announce-results-ubs-settlement-unprecedented-response-voluntary-tax | August 2009 U.S.–Swiss–UBS agreement | Updated February 5, 2025 |
| swissinfo.ch, "Details of 4,450 UBS accounts to be passed to US" | https://www.swissinfo.ch/eng/details-of-4-450-ubs-accounts-to-be-passed-to-us/684242 | 4,450 accounts (secondary) | August 19, 2009 |
| The Washington Times (AP), IRS pays $104 million to whistleblower | https://m.washingtontimes.com/news/2012/sep/11/irs-pays-104-million-whistleblower/ | Birkenfeld award (secondary) | September 11, 2012 |
| IRS news release on end of OVDP | https://www.irs.gov/node/56206 | $11.1 billion from voluntary disclosure, 2009–2018 | Not shown |
| U.S. DOJ, Credit Suisse guilty plea release | https://www.justice.gov/opa/pr/2014/May/14-ag-531.html | 2014 Credit Suisse plea | Not shown |
| U.S. Attorney SDNY, Wegelin guilty plea release | https://www.justice.gov/usao-sdny/pr/swiss-bank-pleads-guilty-manhattan-federal-court-conspiracy-evade-taxes | Wegelin, Switzerland's oldest bank | Not shown |
| IRS IR-2019-151, relief procedures for certain former citizens | https://www.irs.gov/node/71076 | 2019 relief for former citizens | September 6, 2019 |
| Federal Register 2026-04931, CLN fee final rule | https://www.federalregister.gov/d/2026-04931 | 2014 fee increase to $2,350; 2026 fee cut to $450 | Not recorded |
| Federal Register, Quarterly Publication of Individuals Who Have Chosen To Expatriate, quarter ending December 31, 2016 | https://www.federalregister.gov/d/2017-02699 | Renunciation count for 2016 (sum of the four 2016 quarterly lists) | Accessed October 28, 2026 |
| Federal Register, Quarterly Publication of Individuals Who Have Chosen To Expatriate, quarter ending December 31, 2020 | https://www.federalregister.gov/d/2021-02337 | Renunciation count for 2020 (sum of the four 2020 quarterly lists) | Accessed October 28, 2026 |
| CNN Money, Boris Johnson renounces U.S. citizenship | https://web.archive.org/web/20170209115637/http://money.cnn.com/2017/02/09/news/boris-johnson-us-citizenship/ | Johnson renunciation and IRS tax bill (secondary) | February 9, 2017 |
| actu-juridique.fr, "The CJEU is asked to rule on whether FATCA complies with the GDPR" (in French) | https://www.actu-juridique.fr/fiscalite/fiscal-finances/la-cjue-est-saisie-sur-la-conformite-de-la-fatca-au-rgpd/ | AAA founded 2017; Conseil d'État n° 424216; Market Court annulment (secondary) | Not recorded |
| French Senate, debate of May 15, 2018 on accidental Americans | https://www.senat.fr/seances/s201805/s20180515/s20180515007.html | Conflicting AAA founding date (2015) | May 15, 2018 |
| Thorsteinssons, Federal Court rejects Charter challenge of FATCA provisions | https://www.thor.ca/?p=4910 | Canadian Charter challenge (secondary) | Not recorded |
| Belgian Data Protection Authority, 2023 prohibition release | https://www.dataprotectionauthority.be/citizen/belgian-dpa-prohibits-the-transfer-of-tax-data-of-belgian-accidental-americans-to-the-usa | May 2023 ruling | Not recorded |
| Belgian Data Protection Authority, Decision 79/2025 (PDF) | https://www.gegevensbeschermingsautoriteit.be/publications/beslissing-ten-gronde-nr.-79-2025.pdf | 2025 decision on the merits | Not recorded |
| Brussels Times, court order on accidental Americans annulled | https://www.brusselstimes.com/848617/accidental-americans-court-order-for-belgium-to-stop-sharing-tax-data-with-us-annulled | CJEU February 2022 judgment reference (secondary) | Not recorded |
| EU Law Live, Belgian FATCA data transfers referred to the Court of Justice | https://eulawlive.com/oj-belgian-fatca-data-transfers-referred-to-the-court-of-justice/ | Case C-804/25, pending CJEU referral (secondary) | Not recorded |
| H.R. 10468 (118th Congress), Residence-Based Taxation for Americans Abroad Act | https://www.govinfo.gov/app/details/BILLS-118hr10468ih | LaHood bill introduced December 18, 2024 | December 18, 2024 (last action) |