Key takeaways
- The United States does not take part in the Common Reporting Standard: the OECD Global Forum's status of commitments lists it only in a footnote stating that it has exchanged information under FATCA since 2015, while more than 120 other jurisdictions exchange under the CRS.
- Under Treasury Decision 9584 (April 2012) and Article 2 of the Model 1A agreements, the IRS sends a partner country only the name, address, foreign tax ID if on file, account number, deposit interest, U.S.-source dividends and other U.S.-source income of its residents — never the account balance, gross sales proceeds, or the people behind a company or trust.
- Even that data goes only to the roughly 50 jurisdictions on the IRS's automatic-exchange list, most recently restated in Rev. Proc. 2024-42; countries holding a Model 1B or Model 2 agreement send data to the IRS and receive nothing back.
- Joining the CRS would need two things that have never happened: Senate consent to the 2010 protocol to the Convention on Mutual Administrative Assistance in Tax Matters (signed by the United States in May 2010), and a law from Congress authorizing balance and beneficial-owner reporting, which Treasury requested in Obama-era budgets and the Biden administration renewed.
- A trust administered in Sioux Falls that gives one substantial power to a foreign protector fails the control test in Treas. Reg. § 301.7701-7 and is foreign for U.S. tax, yet for CRS purposes it sits in a non-participating jurisdiction and is a reporting institution nowhere.
- The scale of the problem is genuinely unknown: the Casi, Spengel and Stage study shows deposits moving into the United States after the CRS took effect, but nobody can measure how much foreign money held in the United States goes undeclared at home, because the data that would show it is not exchanged.
What is the footnote about the US and CRS?
The OECD's list of jurisdictions committed to the Common Reporting Standard does not include the United States. In its place is a footnote, more or less unchanged since 2014. It says that the United States has been carrying out automatic exchanges under FATCA since 2015, that it has entered into intergovernmental agreements to do so, and that the reciprocal ones among them acknowledge the need for Washington to achieve equivalent levels of exchange, with a political commitment to adopt regulations and support the necessary legislation.
The whole story is in that footnote: a political commitment, made more than a decade ago, that depends on a law Congress has never passed.
What is the old policy of attracting the world's savings?
The asymmetry did not begin with the CRS. It extends an old and fully deliberate tax policy choice. Since the 1920s, interest paid by U.S. banks to nonresident foreign depositors has been exempt from U.S. tax; the exemption now sits in 26 U.S.C. § 871(i). In 1984, Congress added the portfolio interest exemption, now 26 U.S.C. § 871(h), which eliminated withholding on most bonds held by foreigners, with an explicit goal: to finance the federal deficit with the rest of the world's savings. The IRS's own Statistics of Income review of foreign recipients of U.S. income for 1984 ties the Deficit Reduction Act of 1984 to foreign financing of a growing deficit. Nonresidents' capital gains on securities go untaxed as well. Only dividends bear withholding, at 30% or less depending on the treaty, under 26 U.S.C. § 1441.
A foreigner who puts money in the United States therefore owes, for the most part, no tax there. That leaves the question of whether their home country will hear about it. For a long time, the answer was no. Since 1997, U.S. banks have reported to the IRS the interest paid to residents of Canada, and only Canada; the 2002 proposed regulations describe the rules then in force as covering Canadian residents alone. In January 2001, in its final days, the Clinton administration proposed extending that reporting to all foreign depositors, in proposed regulations published on January 17, 2001 and recounted in the same 2002 Federal Register notice. The banking associations of Florida and Texas, whose members have for decades held the rainy-day savings of Latin America's well-to-do, went on the attack. The Bush administration cut the proposal back to 16 countries in 2002, then let it sit, as both the August 2002 proposed regulations and Blum's account show.
It was the Obama administration that dug it up, out of necessity: to get foreign governments to carry FATCA's water, it had to offer them something. A regulation issued in April 2012, Treasury Decision 9584, required U.S. banks to report, starting in 2013, interest paid to any nonresident individual. The Florida and Texas bankers sued. Their challenge was rejected by the district court in 2014, then by the U.S. Court of Appeals for the D.C. Circuit in 2015, in an opinion written by Judge Brett Kavanaugh that disposed of it on procedural grounds without reaching the merits. The Supreme Court declined to hear the case in 2016, after the Solicitor General's petition-stage response in No. 15-969.
What does Washington actually give?
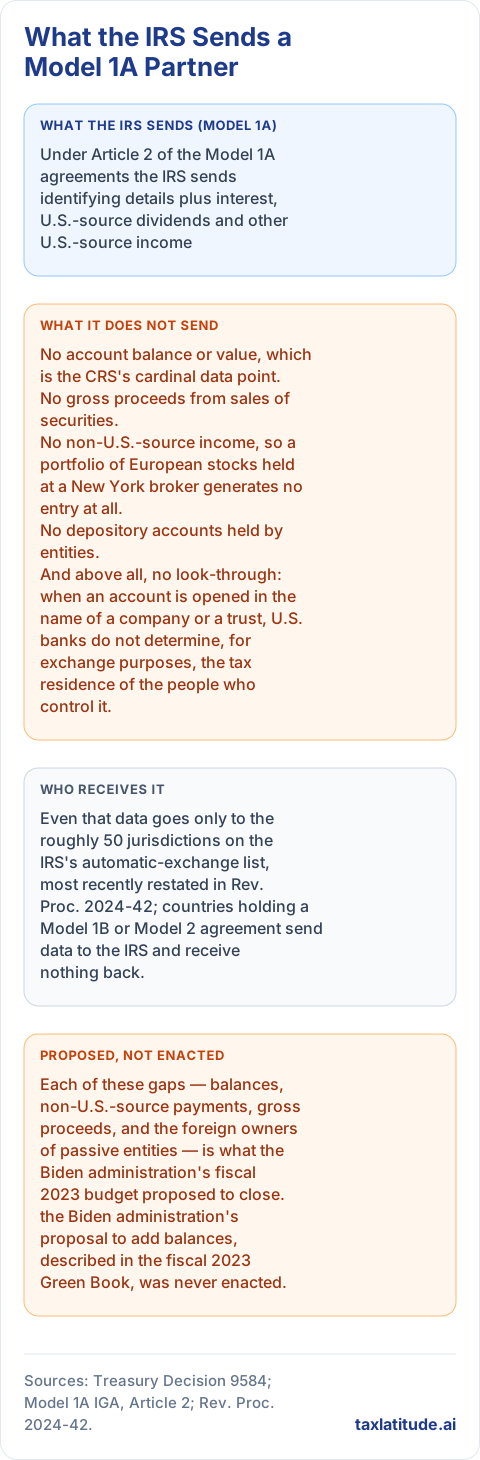
That 2012 regulation remains, to this day, the foundation of what the United States sends abroad. The content is set by Article 2 of the Model 1A intergovernmental agreements. For a resident of the partner country, the IRS provides the name, address, foreign tax ID number if the bank has it on file, the account number, and three categories of amounts: interest paid on depository accounts, U.S.-source dividends, and other U.S.-source income credited to the account.
The list of what is missing is more instructive. No account balance or value, which is the CRS's cardinal data point; the Congressional Research Service lists account balances among the items full reciprocity would require. No gross proceeds from sales of securities. No non-U.S.-source income, so a portfolio of European stocks held at a New York broker generates no entry at all. No depository accounts held by entities. And above all, no look-through: when an account is opened in the name of a company or a trust, U.S. banks do not determine, for exchange purposes, the tax residence of the people who control it. Each of these gaps — balances, non-U.S.-source payments, gross proceeds, and the foreign owners of passive entities — is what the Biden administration's fiscal 2023 budget proposed to close. Putting a Delaware LLC or a British Virgin Islands company between yourself and your Miami account is enough to fall out of scope. That is exactly the flaw that wrecked the EU's Savings Directive in 2005, and the one the CRS was designed to close.
And that assumes the exchange happens at all. The IRS sends data only to countries with which a legal instrument is in place and whose confidentiality safeguards and data use it has vetted; the IRS's FATCA guidance for governments describes the data-safeguards review that reciprocal Model 1A partners must complete. The list, published by revenue procedure and updated periodically, runs to roughly 50 jurisdictions, fewer than half of those that have signed a FATCA agreement; the current version is Rev. Proc. 2024-42, which added Costa Rica and Thailand to the automatic-exchange list. The rest, holding a Model 1B or Model 2 agreement, give and get nothing back; the nonreciprocal model, as the Journal of Accountancy reported when Treasury released it, does not require the United States to provide any information on U.S. accounts.
Why won't Washington join?
The official explanation fits in one sentence: the United States has FATCA, the original, and has no need for the copy. It masks three more concrete obstacles.
The first involves treaties. Multilateral exchange under the CRS rests on the Convention on Mutual Administrative Assistance in Tax Matters, as amended by its 2010 protocol. The United States is a party to the original convention, which it ratified in 1991, according to Treasury's technical explanation of the protocol. It signed the protocol in May 2010, as Treasury announced at the time. The Senate has never given its consent: the Foreign Relations Committee approved it several times, including in Executive Report 114-8 on Treaty Document 112-5, but Sen. Rand Paul, opposed on principle to sharing tax data with foreign governments, blocked every international tax instrument for nearly a decade. The Global Forum's 2018 peer review noted that no signed exchange agreement requiring U.S. ratification, including the 2010 protocol, had been ratified since July 2010. Several bilateral protocols finally went through in July 2019. Not that one.
The second is legislative. Nothing would prevent bilateral agreements built on existing treaties. But to send balances and beneficial owners abroad, U.S. banks would first have to be required to collect them, to gather self-certifications of residence, to look through entities. Treasury takes the position that it needs authority from Congress for that; the reciprocal model agreement itself, as the Journal of Accountancy summarized, commits Washington only to pursue regulations and support legislation. It asked for it in every Obama administration budget proposal from 2013 on, and the Biden administration carried the proposal forward in its own. It has never come to a vote.
The third is political. The coalition of opponents is motley and effective: Florida and Texas banks fearing the flight of Latin American deposits, the trust industry of the Western states, and conservative groups like the Center for Freedom and Prosperity that defend tax competition and the right to financial privacy. They also have an argument that carries real weight: the CRS means handing financial data to authoritarian or corrupt regimes, where it can be used for extortion, kidnapping, or persecution of dissidents. For many Venezuelan or Mexican families, the Miami account is not tax fraud. It is insurance. The argument is sincere for some and convenient for many.
Why does no one make the US join?
The CRS was imposed on tax havens by threat: G20 gray lists, the EU blacklist, defensive measures. None of those weapons has been pointed at Washington.
The OECD, whose largest funder is the United States and whose standard is a carbon copy of the American law, sticks to its footnote. The Global Forum reviews the United States on exchange on request, where it is rated largely compliant in its 2018 peer review, but not on automatic exchange, since it never committed to it. The European Union built its blacklist criteria in such a way that a network of bilateral automatic exchange agreements with every member state is sufficient: the FATCA agreements do the job, however thin their reciprocal content. The European Parliament denounced the double standard in its July 2018 resolution, which regretted the lack of reciprocity in the agreements member states had signed, and groups like Oxfam and the Tax Justice Network repeat the point at every revision of the list. No European government has seen fit to open that front, least of all in the current trade climate.
The underlying reason is the one that explains all of FATCA: leverage. A Swiss bank cannot do without the U.S. market. The U.S. market can do without Switzerland's approval.
What is South Dakota's "foreign" trust?
An industry has flourished on this legal terrain. Its capital is Sioux Falls, population 200,000.
South Dakota abolished the rule against perpetuities in 1983, so trusts there can last forever. It has no income tax, no capital gains tax, and no estate or inheritance tax. Its statutes, rewritten almost every year by a task force on which industry professionals sit, allow self-settled asset protection trusts, seal court proceedings involving trusts, and permit "directed" trusts that split the roles of trustee, investment adviser, and protector. Assets administered by the state's trust companies went from a few tens of billions of dollars in 2010 to $293.5 billion in 2018 (South Dakota Division of Banking), more than $607 billion in 2021, and $815 billion at the end of 2024, up 22% from $680 billion a year earlier (South Dakota Public Broadcasting). Nevada, Wyoming, Alaska, Delaware, and New Hampshire are engaged in the same arms race.
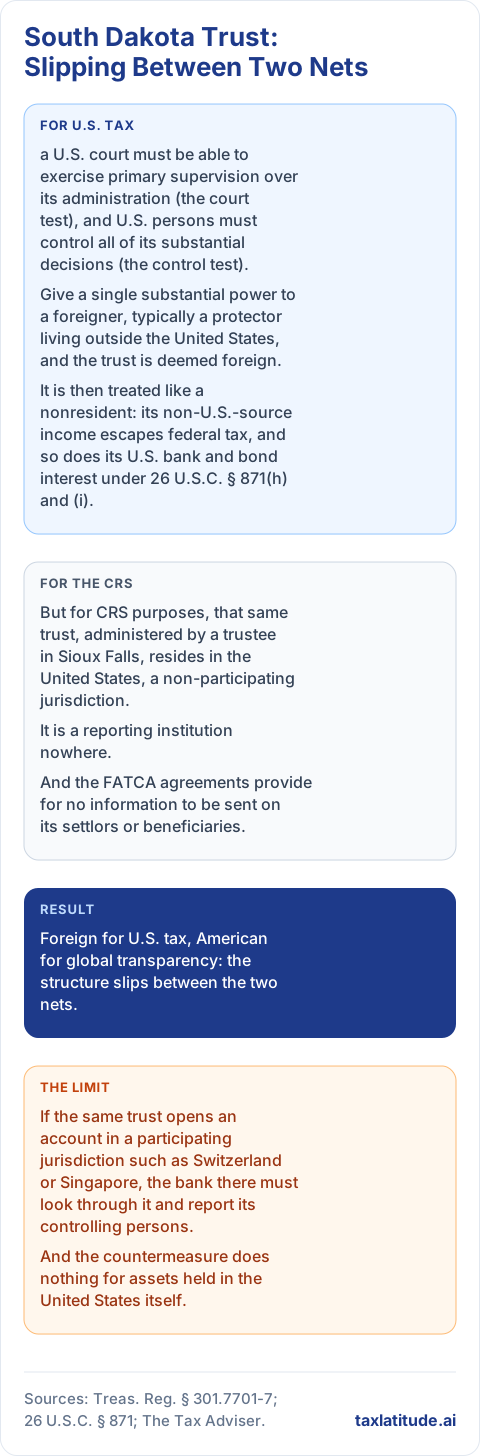
The flagship product for international clients turns on a subtlety of the Internal Revenue Code. A trust is a "U.S." trust for tax purposes only if it passes two tests set out in Treas. Reg. § 301.7701-7: a U.S. court must be able to exercise primary supervision over its administration (the court test), and U.S. persons must control all of its substantial decisions (the control test). Give a single substantial power to a foreigner, typically a protector living outside the United States, and the trust is deemed foreign. It is then treated like a nonresident: its non-U.S.-source income escapes federal tax, and so does its U.S. bank and bond interest under 26 U.S.C. § 871(h) and (i).
But for CRS purposes, that same trust, administered by a trustee in Sioux Falls, resides in the United States, a non-participating jurisdiction. It is a reporting institution nowhere. And the FATCA agreements provide for no information to be sent on its settlors or beneficiaries. Foreign for U.S. tax, American for global transparency: the structure slips between the two nets.
Are you the settlor or a beneficiary of a South Dakota or Nevada trust with a foreign protector? A trust that's "foreign" for U.S. tax purposes under the Treas. Reg. §301.7701-7 control test usually triggers its own Form 3520/3520-A reporting for the U.S. persons connected to it. Check your own filing obligations →
Practitioners generally add a foreign blocker company beneath the trust to shield the assets from the U.S. estate tax, which hits nonresidents' U.S.-situs property above $60,000, the threshold that corresponds to the $13,000 unified credit in 26 U.S.C. § 2102(b).The industry made no secret of it. As early as January 2016, a Bloomberg investigation described Rothschild opening a trust company in Reno, Nevada, Trident Trust moving dozens of accounts from Switzerland and the Caymans to Sioux Falls, and a draft presentation by a Rothschild executive calling the United States the biggest tax haven in the world, a line dropped from the final version. The Pandora Papers, in 2021, identified 206 U.S. trusts tied to foreign fortunes from 41 countries, 81 of them in South Dakota alone, some set up by people accused in their home countries of corruption or human rights abuses.
The standard does include a countermeasure: an investment entity from a non-participating jurisdiction that opens an account in Geneva or Singapore must be looked through and its controlling persons reported, as The Tax Adviser explained when the first participating-jurisdiction lists appeared. But that works only if the country in question doesn't classify the United States as a participating jurisdiction, which several did in the early years on the grounds that they had a FATCA agreement, before the Global Forum pushed for corrections. And the countermeasure does nothing for assets held in the United States itself.
What is the anonymous company, literally?
The system's second pillar is companies. In most U.S. states, you can form an LLC in an hour without telling anyone who owns it. The Financial Action Task Force said as much in its 2016 evaluation, rating the United States non-compliant with its recommendation on transparency of legal persons, a rating its 2024 follow-up report confirms as the starting point.
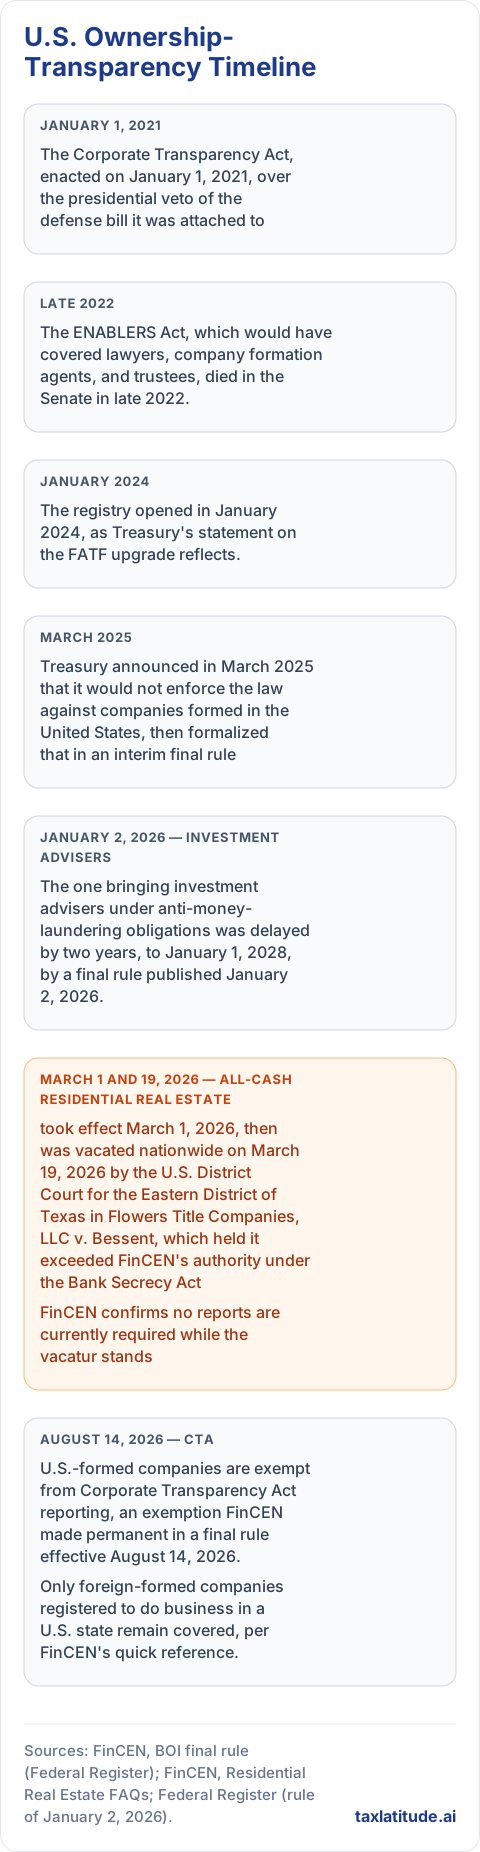
Progress came under pressure from the Panama Papers. Since 2017, foreign-owned single-member LLCs have had to obtain a tax ID number and file an annual information return with the IRS, under Treasury Decision 9796. Since 2018, banks have had to identify the beneficial owners of their legal-entity customers above a 25% threshold, but that information, collected for anti-money-laundering purposes, feeds no tax exchange. The Corporate Transparency Act, enacted on January 1, 2021, over the presidential veto of the defense bill it was attached to, was supposed to finish the job with a federal registry kept by FinCEN, confidential but available to law enforcement and, through treaty channels, to foreign counterparts. The FATF took note and upgraded the U.S. rating in 2024, moving Recommendation 24 from non-compliant to largely compliant in its seventh follow-up report.
The registry opened in January 2024, as Treasury's statement on the FATF upgrade reflects. After a year of trench warfare in the courts, Treasury announced in March 2025 that it would not enforce the law against companies formed in the United States, then formalized that in an interim final rule, which FinCEN made permanent in a final rule effective August 14, 2026: U.S.-formed reporting companies and their U.S.-person owners are permanently exempt, foreign reporting companies no longer have to report their U.S.-person beneficial owners, and FinCEN announced it would delete the domestic ownership data already on file. Only foreign-formed companies registered to do business in a U.S. state remain covered, per FinCEN's quick reference. The Delaware LLC owned by a nonresident, which is to say precisely the vehicle the law was aimed at, is exempt.
The same retreat has hit the neighboring projects. The FinCEN rule extending nationwide the reporting of all-cash residential real estate purchases by companies, successor to the geographic targeting orders launched in Manhattan and Miami in 2016, took effect March 1, 2026, then was vacated nationwide on March 19, 2026 by the U.S. District Court for the Eastern District of Texas in Flowers Title Companies, LLC v. Bessent, which held it exceeded FinCEN's authority under the Bank Secrecy Act; FinCEN confirms no reports are currently required while the vacatur stands (FinCEN, Residential Real Estate FAQs; Gibson Dunn). The one bringing investment advisers under anti-money-laundering obligations was delayed by two years, to January 1, 2028, by a final rule published January 2, 2026. The ENABLERS Act, which would have covered lawyers, company formation agents, and trustees, died in the Senate in late 2022.
What do the flows say?
The effect can be measured. In their 2020 study of the CRS's impact, published in the Journal of Public Economics, Elisa Casi, Christoph Spengel, and Barbara Stage found that cross-border deposits fell in traditional offshore centers after the standard took effect and rose in only one major financial center: the United States. The Tax Justice Network ranked the country second on its Financial Secrecy Index in 2018 and 2020, then first in 2022, with the worst score ever recorded, according to the Tax Justice Network's 2022 announcement and its press release, a rank it has held since: the 2025 ranking again places the United States first.
Caution is in order on the scale, however. Most of the trillions of dollars foreigners hold in the United States are there for reasons that have nothing to do with tax: deep markets, the dollar's status, legal certainty. Nobody knows what fraction goes undeclared back home, precisely because the information that would tell us isn't exchanged.
What is the American defense?
It would be unfair to reduce Washington's position to cynicism. Its defenders point out that the United States answers information requests, including group requests, from its treaty partners, and that its treaty network is one of the most extensive in the world; the Global Forum counted more than 2,600 requests received over 2014–2016 and called the United States a reliable partner. That the Qualified Intermediary regime and withholding tax reporting already document a large share of nonresidents' U.S. income. That the Justice Department has done more than anyone against banks complicit in tax fraud, with investigative tools and penalties unmatched in Europe. And that the IRS's confidentiality requirements for recipient countries are no pretext: Washington suspended its exchanges with Russia in 2022.
All of that is true, and none of it answers the objection. Exchange on request assumes the foreign tax authority already knows what it is looking for, which was precisely the defect of the pre-2009 system, the one the United States itself found unacceptable when its own taxpayers were at issue.
Is crypto one opening?
Only one area breaks the pattern. In November 2023, the United States co-signed a statement by some 50 jurisdictions pledging to implement the OECD's Crypto-Asset Reporting Framework, the CRS's cousin. The 2021 Infrastructure Investment and Jobs Act had already created a broker reporting requirement for platforms, effective for 2025 transactions, as the IRS's digital assets page confirms. The White House working group on digital assets recommended in 2025 that implementation of the OECD framework be studied, and the OECD Global Forum's CARF commitments list now records the United States as committed to first exchanges by 2029, one of four jurisdictions in that cohort, with Argentina, Azerbaijan, and Mexico (the first wave exchanges in 2027, a second wave including Canada, Switzerland, and the UAE in 2028); Treasury's proposed CARF rules reached the White House Office of Information and Regulatory Affairs for review in November 2025 (Decrypt). At the same time, in the spring of 2025, Congress repealed the extension of those requirements to decentralized finance, through a Congressional Review Act resolution, H.J.Res. 25, signed on April 10, 2025.
The logic is plain. The platforms are global, American taxpayers are all over them, and the IRS needs the foreign data. Where Washington has an interest in receiving, it agrees to give.
What are the lever and the hole?
The consequences go beyond the American case. Every financial center told to do more, whether Dubai, Singapore, or Panama, has a ready-made comeback: why us and not Delaware? The standard's legitimacy takes a hit at the very moment countries of the Global South are contesting, at the United Nations, the OECD's right to write rules for everyone.
And the first victims aren't European. France and Germany get some data and can ask for more. The countries of Latin America and Africa, whose elites have traditionally kept their fortunes in Florida or New York, mostly have non-reciprocal agreements or no agreement at all. They hand the IRS the accounts of Americans living in their countries and receive nothing on their own nationals.
The CRS rests on a simple idea: no country can sell other countries' residents their own tax authority's ignorance anymore. It holds for more than 120 jurisdictions. It does not hold for the world's leading financial center, which grasped the value of that information before anyone else, to the point of demanding it from the entire planet, and drew the logical conclusion: what is worth so much to receive is also worth something to withhold — a gap that gets exploited.
Frequently asked questions
Does my U.S. bank report my account to my home country?
Your U.S. bank reports deposit interest it pays you to the IRS under Treasury Decision 9584, but the IRS passes it on only if your country is on the automatic-exchange list in Rev. Proc. 2024-42; residents of countries with a Model 1B or Model 2 agreement, or none, are not reported home at all.
Does the IRS send my account balance to my country's tax authority?
No. Under Article 2 of the Model 1A agreements the IRS sends identifying details plus interest, U.S.-source dividends and other U.S.-source income, but no balance, no gross sale proceeds and no non-U.S.-source income; the Biden administration's proposal to add balances, described in the fiscal 2023 Green Book, was never enacted.
Is a South Dakota trust reported under the Common Reporting Standard?
Not for assets held in the United States: a trust administered in Sioux Falls sits in a non-participating jurisdiction and is a reporting institution nowhere, even if a foreign protector makes it a foreign trust for U.S. tax under Treas. Reg. § 301.7701-7. If the same trust opens an account in a participating jurisdiction such as Switzerland or Singapore, the bank there must look through it and report its controlling persons.
Does a Delaware LLC owned by a nonresident have to report its owners to FinCEN?
No. U.S.-formed companies are exempt from Corporate Transparency Act reporting, an exemption FinCEN made permanent in a final rule effective August 14, 2026. A foreign-owned single-member LLC still has to obtain a tax ID and file an annual information return with the IRS under Treasury Decision 9796, and its U.S. bank still identifies owners above 25% for anti-money-laundering purposes — but none of that feeds a tax exchange with the owner's home country.
Why doesn't the United States participate in the Common Reporting Standard?
Officially because FATCA already exists, but in practice because the Senate has never approved the 2010 protocol to the Convention on Mutual Administrative Assistance, Congress has never authorized banks to collect balances and look through entities for foreign account holders, and a coalition of Florida and Texas banks, Western trust companies and privacy advocates opposes both.
When will the United States exchange crypto account data under CARF?
The OECD Global Forum's commitments list records the United States as committed to first exchanges by 2029, two years after the 2027 early movers, in the last cohort with Argentina, Azerbaijan, and Mexico. U.S. brokers already report customer sales to the IRS on Form 1099-DA for transactions from 2025, per the IRS, while decentralized platforms were removed from broker reporting by H.J.Res. 25.
When should you hire a professional?
Because the asymmetry turns on how a specific account, entity or trust is classified in two or more countries at once — and on rules that changed as recently as 2026 — general reading can explain the system but cannot tell you what is reported about you.
- Foreign national with a U.S. bank or brokerage account. What actually reaches your home country depends on whether it has a Model 1A agreement on the current IRS exchange list and on how the account is titled, which a cross-border adviser can map against your own country's disclosure obligations.
- Settlor or beneficiary of a South Dakota or Nevada trust. A single protector power can flip the trust between U.S. and foreign status for tax, while its treatment under the CRS depends on where its accounts sit and how each country classifies the United States, so the structure needs review by a trusts and estates specialist familiar with both regimes.
- Nonresident owner of a U.S. LLC. The 2026 final rule removed Corporate Transparency Act filing for U.S.-formed companies, but Form 5472 duties, bank due diligence, and possible foreign-registration filings remain, and the penalties for a missed Form 5472 are steep.
- U.S. citizen or green card holder with foreign accounts. The one-way flow described here works against you, not for you: your foreign banks report you to the IRS under FATCA, and you have your own filing obligations, so an international tax adviser should confirm your FBAR and Form 8938 position — TaxLatitude's FBAR guide for Americans abroad covers both.
- Crypto holder on a foreign exchange. Exchanges in CARF jurisdictions begin collecting data for 2027 or 2028 exchanges while the U.S. timeline runs to 2029, so what your home country learns, and when, depends on where both you and the platform are resident.
- Family in a country with only a non-reciprocal FATCA agreement. Your government sends data to the IRS and receives nothing on your U.S. holdings, but it can still ask for information on request under a treaty, so a cross-border tax attorney can assess your exposure under your own country's rules rather than relying on the absence of automatic exchange.
For trust structures, a trusts and estates specialist with cross-border experience is the right starting point; for company and account reporting, a cross-border tax attorney; and for individual filing obligations in more than one country, an international tax adviser.
Sources
All sources accessed October 16, 2026. Page dates are given only where the page showed one; otherwise the cell says so.
| Source | URL | Used for | Page date |
|---|---|---|---|
| OECD Global Forum, Status of commitments for the automatic exchange of financial account information | https://www.oecd.org/tax/transparency/documents/AEOI-commitments.pdf | CRS jurisdiction list and U.S. footnote | Not shown |
| Legal Information Institute, 26 U.S.C. § 871 | https://www.law.cornell.edu/uscode/text/26/871 | Bank deposit interest and portfolio interest exemptions | Not shown |
| Legal Information Institute, 26 U.S.C. § 1441 | https://www.law.cornell.edu/uscode/text/26/1441 | Withholding on dividends paid to nonresidents | Not shown |
| IRS Statistics of Income, Foreign Recipients of U.S. Income and Tax Withheld, 1984 | https://www.irs.gov/pub/irs-soi/84forreusintw.pdf | Deficit Reduction Act of 1984 and foreign deficit financing | Not shown |
| Federal Register, Guidance on Reporting of Deposit Interest Paid to Nonresident Aliens (REG-133254-02) | https://www.govinfo.gov/content/pkg/FR-2002-08-02/pdf/02-19348.pdf | Canada-only reporting, January 2001 proposal, 2002 narrowing | August 2, 2002 |
| Cynthia Blum, "Sharing Bank Deposit Information With Other Countries," Florida Tax Review | https://journals.upress.ufl.edu/ftr/article/view/420 | Banking and Center for Freedom and Prosperity opposition; 16-country proposal | Not shown |
| Federal Register, Treasury Decision 9584, Guidance on Reporting Interest Paid to Nonresident Aliens | https://www.govinfo.gov/content/pkg/FR-2012-04-19/pdf/2012-9520.pdf | April 2012 deposit-interest reporting regulation | April 19, 2012 |
| U.S. Court of Appeals for the D.C. Circuit, Florida Bankers Association v. U.S. Department of the Treasury, No. 14-5036 | https://media.cadc.uscourts.gov/opinions/docs/2015/08/14-5036-1567856.pdf | Kavanaugh opinion dismissing the challenge on procedural grounds | August 14, 2015 |
| NFIB Legal Center and Cato Institute, amicus brief in No. 15-969 | https://cato.org/sites/cato.org/files/wp-content/uploads/florida_bankers_cert-stage.pdf | Citation of the 2014 district court opinion (secondary) | Not shown |
| U.S. Department of Justice, Office of the Solicitor General, Florida Bankers Assoc. v. Department of Treasury brief | https://www.justice.gov/osg/brief/florida-bankers-assoc-v-department-treasury | Supreme Court petition stage, 2015 Term | Updated June 1, 2016 |
| Tax Notes, reprint of Treasury Model 1A IGA (Reciprocal, Preexisting TIEA or DTC) | https://taxnotes.com/lr/resolve//f8h5 | Article 2 content of what the IRS sends (secondary) | November 4, 2013 |
| Congressional Research Service, The Foreign Account Tax Compliance Act (FATCA), IF12166 | https://www.everycrsreport.com/files/2022-07-15_IF12166_22bf33c7407c7926a335dc7a72f460d8f46980de.html | Account balances missing from U.S. reciprocity | July 15, 2022 |
| EY Tax News, Treasury Green Book fiscal 2023 digital asset and reporting proposals | https://taxnews.ey.com/news/2022-0540 | Biden proposal to add balances, non-U.S.-source payments, gross proceeds, passive-entity owners (secondary) | April 4, 2022 |
| IRS, FATCA information for governments | https://www.irs.gov/node/9616 | Data-safeguards review for reciprocal Model 1A partners | Not shown |
| IRS, Internal Revenue Bulletin 2024-52 (Rev. Proc. 2024-42) | https://www.irs.gov/pub/irs-irbs/irb24-52.pdf | Current list of jurisdictions receiving deposit-interest data | December 23, 2024 |
| Journal of Accountancy, Treasury releases model intergovernmental agreement for FATCA | https://www.journalofaccountancy.com/news/2012/jul/20126126/ | Reciprocal commitment to pursue regulations and legislation; nonreciprocal model | Not shown |
| OECD, Convention on Mutual Administrative Assistance in Tax Matters | https://www.oecd.org/en/topics/convention-on-mutual-administrative-assistance-in-tax-matters.html | Convention and 2010 protocol as the CRS legal basis | Last updated September 2023 |
| U.S. Department of the Treasury, Technical Explanation of the Protocol Amending the Convention | https://home.treasury.gov/system/files/131/Treaty-OECD-Protocol-TE-1-16-2014.pdf | U.S. ratification of the original convention in 1991 | January 16, 2014 |
| U.S. Department of the Treasury, press release TG-726 | https://home.treasury.gov/news/press-releases/tg726 | U.S. signature of the 2010 protocol | Not shown |
| U.S. Senate, Treaty Document 112-5 | https://www.govinfo.gov/content/pkg/CDOC-112tdoc5/html/CDOC-112tdoc5.htm | Protocol transmitted to the Senate | Not shown |
| U.S. Senate Committee on Foreign Relations, Executive Report 114-8 | https://www.webharvest.gov/congress114th/20170112013302/http://beta.congress.gov/114/crpt/erpt8/CRPT-114erpt8.pdf | Committee approval of the protocol | Not shown |
| OECD Global Forum, Peer Review Report on the Exchange of Information on Request: United States 2018 (Second Round) | https://www.oecd.org/en/publications/global-forum-on-transparency-and-exchange-of-information-for-tax-purposes-united-states-2018-second-round_9789264302853-en.html | Largely compliant rating; unratified protocol; request volumes | July 16, 2018 |
| PwC, US Senate approves four treaty protocols | https://thesuite.pwc.com/media/10278/pwc-gs-us-treaty-protocols.pdf | July 2019 bilateral protocols and Sen. Paul's hold (secondary) | July 18, 2019 |
| European Parliament, Legislative Observatory, resolution 2018/2646(RSP) on the adverse effects of FATCA | https://oeil.europarl.europa.eu/oeil/en/document-summary?id=1544912 | July 2018 resolution on lack of reciprocity | July 5, 2018 |
| Legal Information Institute, 26 C.F.R. § 301.7701-7 | https://www.law.cornell.edu/cfr/text/26/301.7701-7 | Court test and control test for U.S. trusts | Not shown |
| Legal Information Institute, 26 U.S.C. § 2102 | https://www.law.cornell.edu/uscode/text/26/2102 | $13,000 unified credit behind the $60,000 nonresident estate tax threshold | Not shown |
| South Dakota Division of Banking, Division Update presentation (November 2018 meeting) | https://dlr.sd.gov/banking/meeting_documents/agenda_112618_division_update_presentation.pdf | Trust company assets of $293.5 billion in 2018 | Not shown |
| KELOLAND, South Dakota added five trust companies in 2023 | https://digital-release.keloland.com/?p=1775912 | Trust assets above $607 billion in 2021 (secondary) | Not shown |
| South Dakota Public Broadcasting, Assets in South Dakota trusts top $800 billion | https://www.sdpb.org/politics/2025-05-28/assets-in-south-dakota-trusts-top-800-billion | 2024 trust assets of $815 billion; annual trust task force (secondary) | Not shown |
| KXLF, Biggest tax haven in U.S.? South Dakota, says Pandora Papers investigation | https://www.kxlf.com/national-news/biggest-tax-haven-in-u-s-south-dakota-says-pandora-papers-investigation | 1983 abolition of the rule against perpetuities; 81 South Dakota trusts (secondary) | Not shown |
| The Tax Adviser, CRS impact on financial services institutions | https://www.thetaxadviser.com/issues/2016/mar/crs-impact-on-financial-services-institutions/ | United States as non-participating jurisdiction; look-through rule (secondary) | Not shown |
| Bloomberg Businessweek, The World's Favorite New Tax Haven Is the United States | https://www.bloomberg.com/news/articles/2016-01-27/the-world-s-favorite-new-tax-haven-is-the-united-states | Rothschild in Reno, Trident Trust moves, draft presentation | Not shown |
| ICIJ, Pandora Papers investigation of U.S. trusts | https://icij.org/?p=20069 | 206 U.S. trusts linked to foreign fortunes | Not shown |
| FATF, Mutual Evaluation of the United States (2016) | https://www.fatf-gafi.org/en/publications/Mutualevaluations/Mer-united-states-2016.html | Non-compliant rating on transparency of legal persons | Not recorded |
| FATF, United States: 7th Enhanced Follow-up Report and Technical Compliance Re-Rating | https://www.fatf-gafi.org/content/dam/fatf-gafi/fur/USA-FUR-2024.pdf | 2024 upgrade of Recommendation 24 to largely compliant | March 26, 2024 |
| Tax Notes, Treasury Decision 9796 | https://taxnotes.com/lr/resolve/td9796/d0cf | Reporting by foreign-owned single-member LLCs | Effective December 13, 2016 |
| Covington & Burling, FinCEN Releases Final Rule on Beneficial Ownership | https://www.cov.com/-/media/files/corporate/publications/2016/05/fincen_releases_final_rule_on_beneficial_ownership_and_risk_based_customer_due_diligence.pdf | Bank identification of 25% beneficial owners from 2018 (secondary) | May 10, 2016 |
| Cohen & Gresser, Pulling Back the Curtain: Congress Establishes a Beneficial Ownership Registry | https://www.cohengresser.com/app/uploads/2021/01/Pulling-Back-the-Curtain-Congress-Establishes-a-Beneficial-Ownership-Registry-for-U.S.-and-Foreign-Businesses.pdf | Corporate Transparency Act enactment over veto (secondary) | January 4, 2021 |
| U.S. Department of the Treasury, press release JY2208 | https://home.treasury.gov/news/press-releases/jy2208 | FATF upgrade; registry reporting from 2024 | Not shown |
| FinCEN, Beneficial Ownership Information Reporting | https://www.fincen.gov/boi | March 2025 interim final rule exempting U.S.-formed companies | Not shown |
| FinCEN, BOI quick reference | https://www.fincen.gov/boi/quick-reference | Only foreign-formed registered companies remain covered | Not shown |
| Federal Register, Beneficial Ownership Information Reporting Requirement Revision (final rule) | https://www.federalregister.gov/documents/2026/08/14/2026-16576/beneficial-ownership-information-reporting-requirement-revision | Permanent exemption for U.S.-formed companies (freshness flag) | August 14, 2026 |
| FinCEN, press release on Geographic Targeting Orders in Manhattan and Miami | https://web.archive.org/web/20250729152901/https://www.fincen.gov/sites/default/files/shared/20160113.pdf | 2016 all-cash real estate targeting orders | January 13, 2016 |
| FinCEN, Residential Real Estate Frequently Asked Questions | https://www.fincen.gov/rre-faqs | Vacatur of the residential real estate rule (freshness flag) | Not shown |
| Gibson Dunn, FinCEN's Residential Real Estate Reporting Rule Vacated Nationwide | https://www.gibsondunn.com/fincen-residential-real-estate-reporting-rule-vacated-nationwide/ | March 19, 2026 vacatur details (secondary) | Not shown |
| Federal Register, Delaying the Effective Date of the AML/CFT Program and SAR Requirements for Registered Investment Advisers | https://www.federalregister.gov/documents/2026/01/02/2025-24184/delaying-the-effective-date-of-the-anti-money-launderingcountering-the-financing-of-terrorism | Investment adviser rule delayed to January 1, 2028 | January 2, 2026 |
| National Association of Bond Lawyers, House Clears Updated NDAA with FDTA | https://www.nabl.org/blogs/house-clears-updated-ndaa-with-fdta/ | ENABLERS Act left out of the final 2022 defense bill (secondary) | Not shown |
| Casi, Spengel and Stage, Cross-border tax evasion after the common reporting standard: Game over?, Journal of Public Economics 190 (2020) | https://doi.org/10.1016/j.jpubeco.2020.104240 | Deposit shifts into the United States after the CRS | Not recorded |
| Tax Justice Network, Financial Secrecy Index 2022 announcement | https://taxjustice.net/?p=13725 | United States first in 2022 | Not shown |
| Tax Justice Network, Financial Secrecy Index 2022 press release (hosted by Oxfam Novib) | https://assets.oxfamnovib.nl/downloads/EMBARGOED-Press-release-Financial-Secrecy-Index-2022-002.pdf | Worst rating recorded since the index began in 2009 | Not shown |
| Tax Justice Network, Indexes and tools (Financial Secrecy Index 2025 ranking) | https://taxjustice.net/indexes-tools/ | United States still first in 2025 | Not shown |
| Malay Mail (Reuters), US suspends tax information exchange with Russian authorities | https://www.malaymail.com/amp/news/money---international/2022/04/06/us-suspends-tax-information-exchange-with-russian-authorities/2051791 | 2022 suspension of exchanges with Russia (secondary) | April 6, 2022 |
| U.S. Department of the Treasury, Collective Engagement to Implement the Crypto-Asset Reporting Framework (JY1895) | https://home.treasury.gov/news/press-releases/jy1895 | November 2023 joint statement on CARF | Not shown |
| IRS, Digital assets | https://www.irs.gov/filing/digital-assets | IIJA broker reporting on Form 1099-DA from 2025 transactions | Not shown |
| The Tax Adviser, White House makes recommendations on digital asset transactions | https://www.thetaxadviser.com/issues/2026/jan/white-house-makes-recommendations-on-digital-asset-transactions/ | 2025 working group recommendation on CARF (secondary) | Not shown |
| OECD Global Forum, Jurisdictions committed to implement the Crypto-Asset Reporting Framework | https://www.oecd.org/content/dam/oecd/en/networks/global-forum-tax-transparency/commitments-carf.pdf | United States and three other jurisdictions committed to first exchanges by 2029 (list updated September 14, 2026) | Not shown |
| Decrypt, White House reviews proposed IRS rule to tax Americans' foreign crypto accounts | https://decrypt.co/348926/white-house-reviews-proposed-irs-rule-tax-americans-foreign-crypto | Proposed CARF rules sent for White House review (secondary) | Not shown |
| Congress.gov, H.J.Res. 25 (119th Congress) | https://www.congress.gov/bill/119th-congress/house-joint-resolution/25 | Repeal of the DeFi broker reporting rule | Not recorded |
| Wilson Sonsini, President Trump Revokes Regulations Applicable for Front-End Service Providers | https://www.wsgr.com/en/insights/president-trump-revokes-regulations-applicable-for-front-end-service-providers-facilitating-digital-asset-and-cryptocurrency-transactions.html | April 10, 2025 signing of the repeal (secondary) | April 15, 2025 |
A note on scope: this article is general information, not tax or legal advice. Whether the CRS or FATCA applies to a given account depends on your own facts and on each country’s domestic rules. Consult a qualified professional before acting on your own reporting position.