Key takeaways
- Moving abroad does not remove a US citizen from the federal estate tax. The 2026 exclusion is $15,000,000 per person, taxed at 40% above that, on worldwide assets wherever you live or die — the only real exit is renouncing citizenship.
- The unlimited marital deduction disappears the moment your spouse isn't a US citizen. The main fix is a qualified domestic trust (QDOT), which only defers the tax; during life, a separate $194,000 annual exclusion (2026) applies instead of the regular $19,000.
- The US has an estate tax treaty with only 15 countries. Spain, Portugal, Mexico and nearly every country in Latin America and Asia except Japan have none, leaving only a narrow unilateral foreign death tax credit that doesn't cover US-situs assets taxed by your country of residence.
- Civil law countries can override a US will through forced heirship, regardless of what the will says. France reserves half the estate for one child, two-thirds for two, three-quarters for three or more; the EU Succession Regulation lets you choose US state law instead, but that only changes who inherits, never who taxes.
- A standard US revocable living trust can backfire badly abroad. France taxes undistributed trust assets at 60% at the settlor's death and fines unreported trusts a flat €20,000 — an American with a US trust needs local advice before relying on it.
- Renouncing citizenship doesn't solve the problem if your children stay American — it shifts it to them. Under §2801, gifts and bequests from a "covered expatriate" to a US citizen or resident are taxed at 40%, paid by the recipient, not the person who renounced.
Plenty of Americans retire to Portugal, Mexico, or Italy assuming that leaving the United States means leaving the estate tax behind. It doesn't. The United States taxes its citizens' estates wherever they live and die, and moving abroad usually adds a second set of rules rather than replacing the first. Your new country may tax your estate, your heirs, or the house you buy there, and it will have its own ideas about who inherits.
The choice of country still matters. It decides whether a second inheritance tax applies, whether a treaty or credit prevents overlap, which law governs your will, and whether your American planning tools work locally or backfire. This guide covers those questions for U.S. citizens and green card holders, including couples where one spouse isn't American.
Why doesn't moving get you out of the U.S. estate tax?
The federal estate tax applies to the estate of every U.S. citizen and every U.S. resident. For a citizen, the Form 706 instructions say the gross estate includes all property in which the decedent had an interest, including property outside the United States. A brokerage account in Lisbon, a farmhouse in Umbria, and a pension in Sydney all count. Your passport, not your address, is what puts you in scope.
Green card holders are in a different position. For estate and gift tax purposes, a "resident" is someone domiciled in the United States at death, meaning they lived there with no definite present intention of leaving (Treas. Reg. § 20.0-1(b)(1)). The regulation never mentions green cards. A green card holder who has genuinely moved abroad for good may be treated as a nonresident noncitizen, with the far lower exemption described below; one still domiciled in the United States is taxed like a citizen. Domicile turns on the facts, so get advice on which side of the line you fall.
The only way a U.S. citizen leaves the federal estate tax system is by renouncing citizenship, and that carries its own costs (see "Renouncing citizenship" below).
The U.S. system in brief
What is the unified tax on gifts and estates?
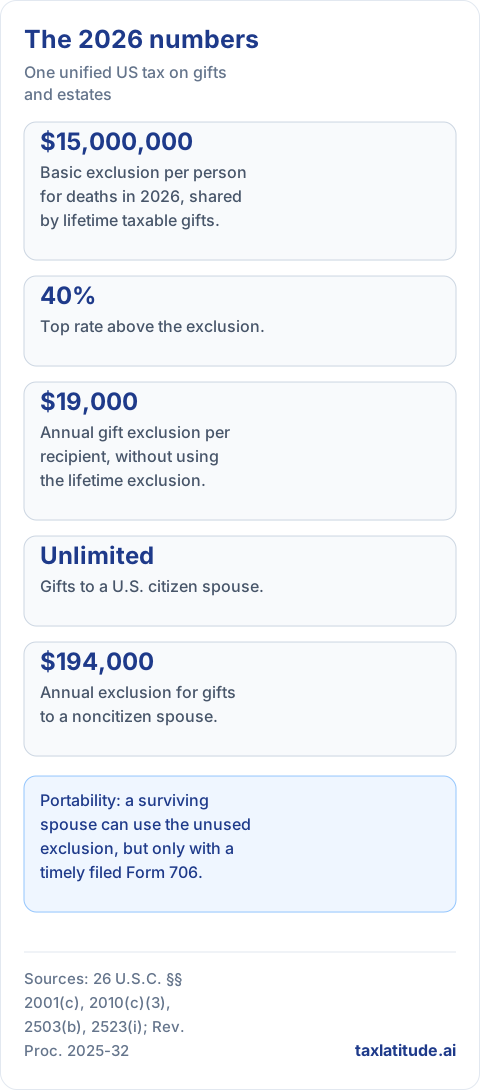
The United States taxes lifetime gifts and transfers at death under a single, unified system. For deaths in 2026, the basic exclusion amount is $15,000,000 per person (26 U.S.C. § 2010(c)(3), as amended by Public Law 119-21 of July 4, 2025; Rev. Proc. 2025-32). The amount is indexed for inflation after 2026. Taxable gifts you make during life use up the same exclusion. Above it, the top rate is 40 percent (§ 2001(c)).
An estate must file Form 706 for a 2026 death if the gross estate, plus adjusted taxable gifts and any specific exemption, exceeds $15,000,000. A surviving spouse can also inherit the deceased spouse's unused exclusion (portability), which requires a timely filed Form 706 even when no tax is due.
What is the annual gift exclusion?
Separately, you can give up to $19,000 per recipient in 2026 without using any of your lifetime exclusion or filing a gift tax return (§ 2503(b); Rev. Proc. 2025-32). Gifts to a U.S. citizen spouse are unlimited.
What is the basis trade-off between a gift and an inheritance?
Inherited assets take a new basis equal to fair market value at death (§ 1014(a)), wiping out the built-in gain. Gifted assets keep the donor's basis (§ 1015). For estates well below $15 million, giving away appreciated assets during life saves no estate tax and costs the recipient the step-up. The surviving spouse's half of community property, including community property under foreign law, also gets a new basis (§ 1014(b)(6)).
What happens when your spouse is not a U.S. citizen?
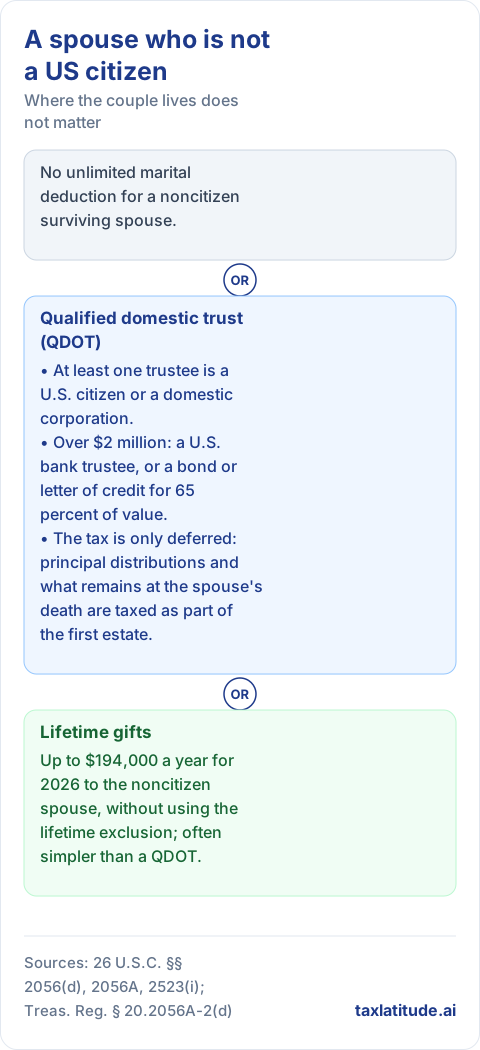
The unlimited marital deduction, which lets a citizen leave everything to a spouse tax-free, does not apply when the surviving spouse is not a U.S. citizen (§ 2056(d)(1)). It doesn't matter where the couple lives.
The main exception is a qualified domestic trust (QDOT) (§ 2056(d)(2)(A); § 2056A). Assets left to a QDOT qualify for the marital deduction, but the tax is only deferred:
- At least one trustee must be a U.S. citizen or a domestic corporation, and no distribution other than income can be made unless that trustee has the right to withhold the deferred estate tax (§ 2056A(a)(1)).
- QDOTs over $2 million need a U.S. bank trustee or a bond or letter of credit for 65 percent of value (Treas. Reg. § 20.2056A-2(d)).
- Distributions of principal during the surviving spouse's life, and whatever remains at the spouse's death, are taxed as if they were part of the first spouse's estate (§ 2056A(b)(1)). Income distributions and hardship distributions are exempt (§ 2056A(b)(3)).
- If the surviving spouse becomes a U.S. citizen before the estate tax return is filed, and was a U.S. resident at all times after the death, the restriction is lifted (§ 2056(d)(4)). Later citizenship can also turn off the QDOT tax going forward (§ 2056A(b)(12)).
Spouse not a US citizen, and wondering if a QDOT is worth setting up? A QDOT only defers the estate tax, not removes it, and above $2 million it needs a US bank trustee or a bond for 65% of value. Ask TaxLatitude to weigh a QDOT against the $194,000 annual-gift alternative →
Jointly held property is treated differently too. The usual rule that includes only half of spousal joint property in the first estate does not apply when the survivor is a noncitizen (§ 2056(d)(1)(B)), so the property can be included in full unless the surviving spouse can show what they contributed.
During life, gifts to a noncitizen spouse don't qualify for the unlimited marital deduction. Instead, a special annual exclusion applies: $194,000 for 2026 (§ 2523(i); Rev. Proc. 2025-32). Over a decade or two, that allowance can move substantial assets into the noncitizen spouse's name without using any lifetime exclusion, which is often simpler than a QDOT.
What happens when the foreign spouse owns U.S. assets?
A spouse who is neither a U.S. citizen nor domiciled in the United States is subject to a much harsher regime on U.S. property. The estate of a nonresident noncitizen gets a unified credit of only $13,000 (§ 2102(b)(1)), which shelters about $60,000 of U.S.-situs assets. Above that threshold, a Form 706-NA is required.
U.S.-situs property includes U.S. real estate and stock in U.S. corporations (§ 2104(a)), while life insurance, many U.S. bank deposits, and portfolio-interest debt are carved out (§ 2105). A foreign spouse with a U.S. brokerage account full of U.S. stocks therefore has real exposure. A treaty can soften it, for example with a prorated share of the citizen-level credit (§ 2102(b)(3)(A)). Portability isn't available for a nonresident noncitizen's estate (Treas. Reg. § 20.2010-2(a)(5)).
The gift tax is different: a nonresident noncitizen pays it only on property situated in the United States (§ 2511(a)), and gifts of intangibles such as stock are exempt (§ 2501(a)(2)).
How do you report what you receive from abroad?
A U.S. person who receives more than $100,000 in a year in gifts or bequests from a nonresident noncitizen or a foreign estate must report them on Form 3520; for gifts from foreign corporations or partnerships, the 2026 threshold is $20,573 (§ 6039F; Rev. Proc. 2025-32). No tax is due, but the penalty for not filing is 5 percent per month, up to 25 percent (§ 6039F(c)) — see our Form 3520 penalty guide for a worked example and the routes to fix a missed filing.
Two tax systems at once
How do foreign countries decide who to tax?
A second country's rules may target you, your heirs, or your property. Countries use three main tests, often together:
- The deceased's residence. The country where you live taxes your worldwide estate. This is the most common test.
- The heir's residence. Some countries tax what their residents receive, wherever the deceased lived. Germany taxes the whole transfer if either the deceased or the heir lives there (ErbStG § 2). Spain taxes residents on everything they inherit, wherever it is (Ley 29/1987, art. 6). France taxes heirs who have lived there for at least six of the past ten years and live there when they inherit (CGI art. 750 ter). If your children live in one of these countries, your own address doesn't change the answer.
- The asset's location. Real estate is almost always taxed where it sits.
Some countries keep a hold after you leave. Since April 6, 2025, someone U.K. resident for 10 of the past 20 tax years stays within U.K. inheritance tax on worldwide assets for 3 to 10 years after departure. Germany extends its rule to German nationals for five years after they move abroad, and the Netherlands treats Dutch nationals as resident for ten years after emigrating (Successiewet art. 3). These tails matter if you, your spouse, or your heirs have ties to those countries.
What are the U.S. estate and gift tax treaties?
The United States has estate tax treaties with only 15 countries, according to the IRS's official list: Australia, Austria, Canada, Denmark, Finland, France, Germany, Greece, Ireland, Italy, Japan, the Netherlands, South Africa, Switzerland, and the United Kingdom. The provisions for Canada sit in Article XXIX B of the U.S.-Canada income tax treaty and cover estate taxes, not gift taxes. They include a prorated unified credit for Canadian residents and credits for death taxes in each direction.
These treaties allocate taxing rights by asset, break ties when both countries claim you as a domiciliary, and require each country to credit the other's tax. The U.S.-Germany treaty, for example, has a tie-breaker added in 1998 that can treat a citizen of one country who has lived in the other for less than ten years as domiciled in the country of citizenship.
A country not on that list has no estate tax treaty with the United States, however good its income tax treaty. That includes Spain, Portugal, Mexico, and every country in Latin America and Asia except Japan. See How to Read a U.S. Tax Treaty.
What is the foreign death tax credit, and what is its gap?
Without a treaty, the United States gives a unilateral credit for foreign estate, inheritance, or succession taxes (§ 2014). It's narrower than it looks. It applies only to foreign tax paid on property situated in the country that imposed the tax and included in the U.S. gross estate. It's also limited to the lesser of the foreign tax on that property and the share of U.S. tax attributable to it.
Suppose you live in a country with an inheritance tax and no treaty, and it taxes your U.S. brokerage account because you lived there. The account is situated in the United States, so § 2014 gives no credit, and both countries can tax it in full. A treaty usually closes that gap. For most Americans abroad, whose estates fall below $15 million, the U.S. tax is zero anyway, and the real cost is whatever the host country charges.
Civil law: who inherits, not just who pays
What is forced heirship?
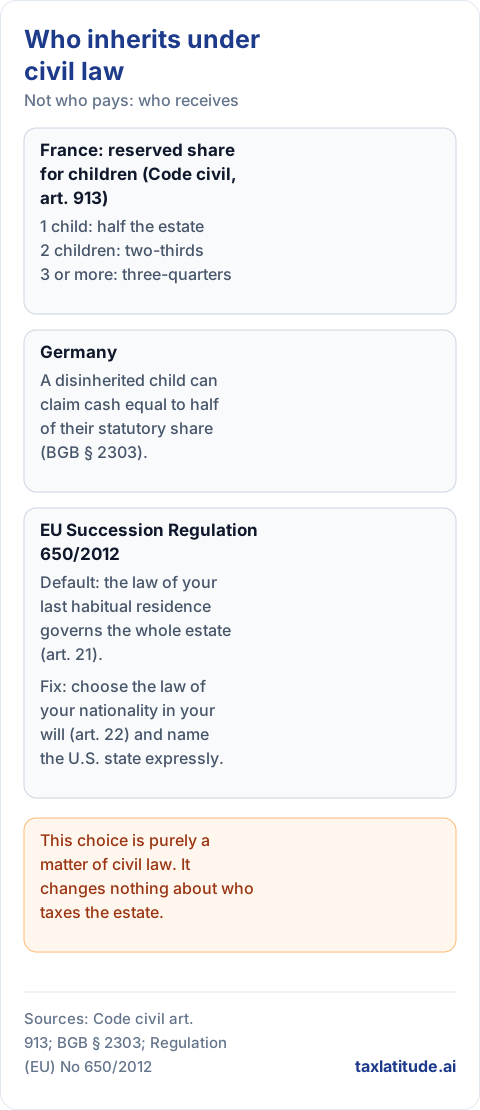
Most U.S. states give you nearly complete freedom to leave your property to whomever you choose, subject to a spouse's rights. Civil law countries reserve a share for children. In France, the reserved share is half the estate for one child, two-thirds for two, and three-quarters for three or more (Code civil, art. 913). In Germany, a disinherited child can claim cash equal to half of their statutory share (BGB § 2303). A blended family, a second spouse, or a planned charitable gift can run straight into these rules.
What is the EU Succession Regulation and choice of law?
For Americans living in the European Union, the key text is Regulation (EU) No 650/2012, which applies to deaths on or after August 17, 2015, in every member state except Denmark and Ireland. Its default rule is that the law of your last habitual residence governs your entire estate (art. 21). It applies even if that law is a non-EU one (art. 20). An American living in Spain or France therefore has, by default, an estate governed by Spanish or French succession law, forced heirship included.
The regulation also offers the fix: in a will, you may choose the law of your nationality (art. 22). Because the United States has no single succession law, a reference to "U.S. law" points to the law of the state with which you had the closest connection (art. 36(2)(b)). The safest wording names that state expressly. This choice is purely a matter of civil law. It changes nothing about who taxes the estate.
France has added a twist. Since November 1, 2021, when the governing foreign law gives children no reserved share, children can claim a compensatory amount out of property located in France, provided the deceased or one of the children is an EU national or habitual resident (Code civil art. 913, third paragraph, added by Loi n° 2021-1109). An American in France who chooses the law of a U.S. state to disinherit a child should expect that child to have a claim against the French assets.
What happens with wills in more than one country?
Many Americans abroad have a U.S. will for U.S. assets and a local will for local property. That works only if each is drafted with the other in mind: a standard U.S. will that "revokes all prior wills" can wipe out the local one, and vice versa. The United States has joined neither the 1961 Hague Convention on the form of wills nor the 1973 Washington Convention on international wills (signed, never ratified). Have the two wills drafted together, each limited expressly to its own assets.
What happens to U.S. trusts in civil law countries?
The revocable living trust, standard U.S. planning to avoid probate, is a foreign object in many civil law countries. The 1985 Hague Trusts Convention, which the United States signed but never ratified, counts Italy, Switzerland, the Netherlands, the United Kingdom, Canada, and Australia among its parties; France signed but never ratified.
France is the clearest example. A trust with a French-resident settlor or beneficiary, or French assets, must be reported; undistributed trust assets can be taxed at the settlor's death at 60 percent, and failing to report carries a flat €20,000 penalty (CGI art. 792-0 bis and art. 1736 IV bis). An American in France with a revocable trust from home needs a French adviser and may be better off unwinding it.
Still holding a US revocable living trust after moving to France? The 60% tax on undistributed assets and the flat €20,000 reporting penalty apply whether or not you knew about them. Ask TaxLatitude what unwinding or keeping the trust would actually cost →
Your marital property regime also decides what falls into each estate, and moving can change how it's recognized. Have it reviewed in your new country.
What should you check for each destination?
For each country, the questions are the same: does it add a second inheritance tax, is there a U.S. estate tax treaty, and what civil law point matters most.
The table below covers all 36 countries this site has a guide for, as a quick reference. The narrative below goes deeper on the countries that come up most for Americans weighing where to live.
| Country | Inheritance/estate tax? | Top rate | Notable allowance / threshold | Note for a US citizen heir or decedent | Source |
|---|---|---|---|---|---|
| Australia | No (state and federal death duties ended around 1979) | N/A | N/A | No inheritance, estate or gift tax, but special CGT rules apply to assets passing from a deceased estate and to superannuation death benefits — watch CGT event K3 (gain triggered when an asset passes to a non-resident beneficiary). US–Australia estate & gift treaty exists but has little practical effect. | source |
| Brazil | Yes – set by each state (ITCMD) | Up to 8% (Senate Resolution 9/1992 cap), same cap for all heirs; São Paulo still applies a single 4% rate | No national allowance; each state sets its own | Constitutional Amendment 132/2023 made progressive ITCMD rates constitutionally mandatory; Complementary Law 227/2026 (Jan 2026) regulates how states must apply this, including taxation of assets held abroad. A proposal to raise the 8% cap has not been approved. No US treaty. | source source |
| Cambodia | No | N/A (PwC lists inheritance and gift tax as NA) | N/A | Property transfers by inheritance to direct relatives are exempt from the 4% real estate registration tax that otherwise applies to transfers. | source |
| Canada | No (federal estate tax abolished in 1972) | N/A – instead, a deemed disposition at fair market value at death can trigger capital gains tax, unless property passes to a spouse/common-law partner | Spouse rollover; provincial probate fees vary by province | US–Canada treaty Art. XXIX B coordinates Canadian tax at death with US estate tax. | source |
| China (PRC) | No | N/A | N/A | None. An inheritance tax has been discussed under the 'common prosperity' agenda; nothing enacted. | source |
| Colombia | No dedicated tax – inheritances taxed as 'occasional gains' | 15% (general occasional-gains rate, all heirs) | Art. 307 Tax Code: first 13,000 UVT of the deceased's home; 6,500 UVT of other real estate; 3,250 UVT per heir. UVT 2026 = COP 52,374 (DIAN Res. 000238/2025) | The 2022 reform (Law 2277) cut the per-heir exemption from 3,490 to 3,250 UVT. No US treaty. | source |
| Costa Rica | No | N/A (no inheritance tax, no gift tax) | N/A | None. | source |
| France | Yes | Children/parents: 5%–45% (45% above €1,805,677); siblings: 35%/45%; relatives up to 4th degree: 55%; others: 60% | Spouse/PACS partner exempt. Allowances: child or parent €100,000; sibling €15,932; nephew/niece €7,967; others €1,594; +€159,325 for a qualifying disabled heir | US–France estate & gift treaty. Domestic law (Art. 750 ter CGI): an heir resident in France ≥6 of the last 10 years is taxed on worldwide assets received; the treaty can change the outcome. | source source |
| Georgia (country) | No dedicated tax | N/A (PwC lists inheritance tax as NA) | Exempt from income tax: inheritances to 1st/2nd-level heirs; 3rd/4th-level heirs exempt up to GEL 150,000, taxed at 20% above that | Above the threshold, the inheritance counts as taxable income. These details come from secondary guides (EY, Mondaq), not an official Georgian source — no primary document was found. | source |
| Germany | Yes | Class I (spouse, children, grandchildren): 7%–30%; Class II (siblings, nieces/nephews, in-laws): 15%–43%; Class III (others): 30% up to €13,000,000, 50% above | Spouse €500,000; children €400,000; grandchildren €200,000; others in Class I €100,000; Classes II/III €20,000 (§16 ErbStG). Extra pension allowance up to €256,000 (spouse) and €52,000 (child) | US–Germany estate & gift treaty. Germany taxes worldwide transfers if either party lives in Germany or is a German national abroad for no more than 5 years. | source source |
| Ghana | No separate tax | Gifts added to taxable income: 25% (non-residents), marginal rate up to 35% (residents), or elected flat 25% | N/A | PwC does not say whether inheritances count as 'gifts' — genuinely unconfirmed, not just unresearched. | source |
| Hong Kong | No (abolished 2006) | N/A | N/A | Abolished for deaths on/after Feb 11, 2006. A nominal HK$100 duty applied only to estates valued above HK$7.5 million, for deaths between Jul 15, 2005 and Feb 10, 2006. | source |
| India | No (abolished 1985) | N/A | N/A | Estate duty abolished for deaths on/after Mar 16, 1985. | source |
| Indonesia | No | N/A | N/A | None. | source |
| Ireland | Yes (Capital Acquisitions Tax) | 33% (all groups) | For gifts/inheritances on/after Oct 7, 2026: Group A €420,000 (mainly children); Group B €44,000 (siblings, nieces/nephews, grandchildren); Group C €22,000 (others). Spouse/civil partner exempt | US–Ireland estate treaty. Non-Irish-domiciled people only count as resident for CAT after 5 consecutive years of residence. New thresholds announced in Budget 2027 (Oct 6, 2026); require the Finance Act 2026 to pass. | source |
| Israel | No (abolished Apr 1, 1981) | N/A | N/A | No inheritance tax, but assets acquired by inheritance carry over the deceased's cost basis, so a later sale by the heir can trigger capital gains tax of roughly 20%–45%, similar in effect to Australia's CGT event K3. | source |
| Italy | Yes (abolished 2001, reintroduced 2006) | 4% spouse/direct line above €1,000,000 each; 6% siblings above €100,000; 6% other relatives up to 4th degree (no allowance); 8% everyone else | €1,500,000 for a severely disabled heir. Real estate also bears 2% mortgage tax + 1% cadastral tax | US–Italy estate treaty. Since 2025 heirs self-assess and pay the tax (D.Lgs. 139/2024). | source |
| Japan | Yes | 10%–55% (55% above ¥600,000,000), applied to each statutory heir's legal share | Basic exemption ¥30,000,000 + ¥6,000,000 per statutory heir; spouse owes nothing up to the larger of ¥160,000,000 or their legal share | US–Japan estate & gift treaty. Foreign nationals on work-type ('Table 1') visas living in Japan <10 of the last 15 years are taxed only on Japanese assets. | source |
| Malaysia | No (abolished Nov 1, 1991) | N/A | N/A | None. | source |
| Mexico | No dedicated tax | Inheritances received are exempt from income tax regardless of the heir's residency (Art. 93-XXII, Ley del ISR) | Gifts from non-close family exempt up to 3× annual UMA (MXN 128,384) | The exemption covers the inheritance itself. A later sale of inherited Mexican real estate or shares by a non-resident heir is a separate transaction, taxed under Mexico's ordinary non-resident capital-gains withholding rules — not a tax on the inheritance. | source |
| Netherlands | Yes | 2026: partner/children 10%, 20% above €158,669; grandchildren 18%/36%; others (incl. parents, siblings) 30%/40% | 2026 exemptions: partner €828,035; children/grandchildren €26,230; parents €62,110; others €2,769 | US–Netherlands estate treaty. Dutch nationals count as residents for 10 years after emigrating; no inheritance tax when the deceased was a non-resident. | source source |
| New Zealand | No | N/A | N/A | Estate duty abolished for deaths on/after Dec 17, 1992; gift duty abolished from Oct 1, 2011. | source source |
| Panama | No | N/A | N/A | None. | source |
| Philippines | Yes (estate tax) | Flat 6% on the net estate (deaths from Jan 1, 2018) | Standard deduction ₱5,000,000 (citizens/residents), ₱500,000 (non-resident aliens); family home up to ₱10,000,000 (citizens/residents only) | Non-resident aliens: only Philippine property, and intangibles may be exempt under reciprocity. A resident alien (incl. a US citizen living there) is taxed on worldwide assets. | source |
| Portugal | No inheritance tax (abolished 2004); 10% stamp duty instead | 10% stamp duty on inheritances/gifts to non-exempt heirs | Spouse/de facto partner, descendants and ascendants fully exempt (Código do Imposto do Selo, art. 6º, al. e) | Stamp duty applies only to assets located in Portugal. | source |
| Russia | No (abolished, not applied since Jan 1, 2006) | N/A – inheritances exempt from personal income tax, except royalty/patent-type payments to heirs (13%–22%) | N/A | From 2026, people designated 'foreign agents' lose the inheritance exemption, and gifts to them are taxed at a flat 30% regardless of family relationship. | source |
| Seychelles | No | N/A | N/A | The Revenue Commission's own list of taxes it administers includes no inheritance, estate or gift tax; the Succession Act 1977 is the underlying legal basis cited by local practitioners. | source |
| Singapore | No (abolished Feb 15, 2008) | N/A | N/A | None. | source |
| South Korea | Yes (taxed on the whole estate) | 10%–50% (50% above ₩3,000,000,000) | ₩200,000,000 basic deduction; resident estates may take a ₩500,000,000 lump-sum deduction instead if larger; spouse deduction ₩500,000,000–3,000,000,000 | No US treaty. Non-resident decedent: only Korean assets taxed, but only the basic deduction applies. A bill to cut the top rate to 40% (threshold to ₩1bn) was rejected by the National Assembly in 2024 and remains under debate — watch for changes. | source source |
| Spain | Yes – varies by region | State scale 7.65%–34% × multiplier 1.0–2.4 (kinship + heir's existing wealth), then regional credits (up to 99%). Theoretical state maximum 81.6% (distant, already-wealthy heir) | State allowances (Art. 20 LISD): Group I (under 21) €15,956.87 + €3,990.72 per year under 21, max €47,858.59; Group II €15,956.87; Group III €7,993.46; Group IV none | No US treaty. Non-residents taxed on Spanish assets; they can apply the rules of the region where the assets are located. | source |
| Switzerland | Varies by canton (no federal tax) | Unrelated heirs, base rate: Neuchâtel 45%, Solothurn 36%, Jura and Ticino 35%, Geneva 26%, Basel-Stadt 18% — but Basel-Stadt adds a surtax of up to +175% of the calculated tax for estates above CHF 3,000,000, pushing its real maximum to roughly 49.5%, likely the highest of any canton | Schwyz and Obwalden levy no inheritance tax; spouses exempt everywhere; descendants exempt almost everywhere (exceptions: Appenzell I.Rh., Neuchâtel, Vaud) | US–Switzerland estate treaty. A federal 50% inheritance tax initiative on estates above CHF 50 million was rejected by 78.3% of voters on Nov 30, 2025. | source |
| Taiwan | Yes (estate tax) | 10%; 15% above NT$56,210,000; 20% above NT$112,420,000 (on the estate) | NT$13,330,000 exemption; spouse deduction NT$5,530,000; NT$560,000 per descendant | No US treaty. Non-domiciled foreigners taxed only on Taiwan property under the Estate and Gift Tax Act. | source |
| Thailand | Yes (introduced Feb 1, 2016) | 10% general; 5% for ascendants/descendants | Only the portion above THB 100,000,000 from each deceased person is taxed; spouse exempt | Foreigners domiciled in Thailand under immigration law are fully liable; other foreigners are taxed only on Thai assets. | source |
| UAE | No | N/A | N/A | None. | source |
| UK | Yes | 40% above the combined threshold | £325,000 nil-rate band, frozen until April 2031, plus £175,000 residence nil-rate band (home to direct descendants), frozen until April 2030 | US–UK estate & gift treaty. Since Apr 6, 2025, worldwide assets are in scope after 10 of the last 20 years of UK residence (a 3–10 year tail applies after leaving). Spouse exemption capped at £325,000 if the spouse isn't a long-term UK resident. | source |
| Ukraine | No dedicated tax – taxed as personal income | 0% from resident close family (spouse, child, parent, sibling, grandparent, grandchild); 5% other residents; 18% if deceased or heir is non-resident | N/A | A non-resident US heir pays 18% plus a military levy, raised from 1.5% to 5% effective Dec 1, 2024 (Law No. 4015-IX). | source |
Western Europe
Portugal has no inheritance tax as such. Gratuitous transfers are subject to a 10 percent stamp duty, plus 0.8 percent on real estate, with the spouse or de facto partner, descendants, and ascendants exempt (Código do Imposto do Selo, item 1.2 and art. 6). For an American leaving assets to a spouse or children, that's close to zero. There is no U.S. estate tax treaty. Portugal is an EU country, so the Succession Regulation and its choice of law apply. See our Portugal guide.
Italy taxes inheritances lightly: 4 percent above €1,000,000 per heir for a spouse or direct descendants, 6 percent above €100,000 for siblings, 6 percent for other relatives up to the fourth degree, and 8 percent for others (D.Lgs. 346/1990, art. 7, as rewritten by D.Lgs. 139/2024). Italy has a U.S. estate tax treaty and is a party to the Hague Trusts Convention. New residents can elect a flat tax on foreign income, which costs €300,000 a year for people who move to Italy from January 1, 2026 (Law 199/2025). While the election is in force, the Agenzia delle Entrate states that Italian inheritance and gift tax applies only to property located in Italy (Circular 17/E of 2017). See our Italy guide.
Spain has a national inheritance tax with regional variations that can be large, from near-total relief for close family in some regions to heavy tax in others. Spain taxes residents on everything they inherit (Ley 29/1987, art. 6). Since Ley 26/2014, and Ley 11/2021 for residents outside the EU, nonresidents can also apply regional rules. Spain has no U.S. estate tax treaty, which makes the § 2014 gap described above a real risk for larger estates. See our Spain guide.
France is among the most expensive destinations for estate purposes. Each child receives a €100,000 allowance per parent. The top rate in direct line is 45 percent, and transfers between unrelated people are taxed at 60 percent (CGI art. 777 and 779). French life insurance can pass €152,500 per beneficiary outside the inheritance tax on premiums paid before age 70, with tax at 20 percent and then 31.25 percent above that (CGI art. 990 I). There is a U.S. estate tax treaty, plus forced heirship, the 2021 compensatory claim, and the trust rules above. See our France guide.
Germany taxes the whole transfer if either the deceased or the heir lives there. A child's allowance is €400,000 and a spouse's €500,000 (ErbStG § 16). Rates run from 7 to 30 percent for close family and up to 50 percent for unrelated heirs (§ 19). There is a U.S. estate tax treaty with the ten-year domicile tie-breaker mentioned above. See our Germany guide.
The United Kingdom is covered by a U.S. estate tax treaty in force since November 11, 1979. Its long-term residence rule matters for Americans who have spent ten years or more there, since the tail can follow you for up to a decade after you leave. See our UK guide.
Ireland taxes inheritances at 33 percent under its capital acquisitions tax. For transfers from October 7, 2026, a child's tax-free threshold from a parent is €420,000. Someone not domiciled in Ireland counts as resident for this tax only after five consecutive tax years of residence. There is a U.S. estate tax treaty, but the EU Succession Regulation does not apply in Ireland. See our Ireland guide.
The Netherlands has a U.S. estate tax treaty and is a party to the Hague Trusts Convention. Watch the ten-year rule for Dutch nationals, which matters if your spouse is Dutch. See our Netherlands guide.
Switzerland has no federal inheritance tax. The cantons decide. Every canton exempts the surviving spouse, and most exempt descendants. Schwyz and Obwalden levy no inheritance or gift tax at all. Voters rejected a proposed 50 percent federal tax on estates above CHF 50 million on November 30, 2025, with 78.3 percent voting no. Switzerland has a U.S. estate tax treaty and is a party to the Hague Trusts Convention. See our Switzerland guide.
The Americas
Canada has no estate tax as such. Instead, it treats a person as having sold their capital property at fair market value immediately before death, taxing the built-in gain on the final return, with deferral for property passing to a Canadian-resident spouse (Income Tax Act s. 70(5)). The U.S.-Canada treaty provides credits each way, though the U.S. credit for the Canadian gains tax at death is limited, so an American dying in Canada with a large estate can face both taxes. See our Canada guide.
Mexico has no federal inheritance tax, and inheritances and legacies are exempt from Mexican income tax (Ley del ISR, art. 93, XXII). There is no U.S. estate tax treaty. See our Mexico guide.
Brazil has a state-level inheritance and gift tax, the ITCMD. Its maximum rate has been capped at 8 percent by a Senate resolution, and a 2023 constitutional amendment (EC 132/2023) made it mandatorily progressive. There is no U.S. estate tax treaty. See our Brazil guide.
Costa Rica and Panama are popular retirement destinations. Neither has a U.S. estate tax treaty. Ask a local lawyer how local transfer taxes, registration costs and succession rules apply to property you hold there. See our Costa Rica guide and Panama guide.
Asia-Pacific
Japan is the most expensive destination on this list. Its inheritance tax reaches 55 percent on the largest shares. Heirs living in Japan, and certain Japanese nationals abroad, are generally taxed on worldwide assets. There is a U.S. estate tax treaty. See our Japan guide.
South Korea taxes inheritances at up to 50 percent. There is no U.S. estate tax treaty. See our South Korea guide.
Singapore abolished estate duty for deaths on or after February 15, 2008, and Hong Kong from February 11, 2006. With no local tax, the lack of a treaty matters little. See our Singapore guide and Hong Kong guide.
Australia has no inheritance or estate taxes, according to its tax office. Death generally doesn't trigger capital gains tax, except when assets pass to a foreign-resident beneficiary or a tax-exempt body, which matters if your heirs live outside Australia. A U.S. estate tax treaty exists. See our Australia guide.
The Middle East
The United Arab Emirates does not levy income tax on individuals, and the government’s official tax portal lists VAT, excise tax, corporate tax and customs duties but no inheritance tax. Here the main issue for an American is civil, not fiscal. Federal Decree-Law No. 41 of 2022 on civil personal status for non-Muslims, in force since February 1, 2023, lets non-Muslims apply their home country's law, and without a will gives half the estate to the spouse and half to the children in equal shares. The DIFC Courts register wills for non-Muslims aged 18 and over with assets in the UAE. There is no U.S. estate tax treaty. See our UAE guide.
Israel has no U.S. estate tax treaty, so check with a local adviser how Israeli rules would treat your estate and your heirs. See our Israel guide.
Does your last U.S. state still matter?
Often the most valuable move happens before you leave: making sure your last state no longer treats you as domiciled. In 2026, twelve states and the District of Columbia levy their own estate tax: Connecticut, Hawaii, Illinois, Maine, Maryland, Massachusetts, Minnesota, New York, Oregon, Rhode Island, Vermont, and Washington. Five states levy an inheritance tax on heirs: Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania. Maryland levies both.
The thresholds are far below the federal exclusion. Oregon requires a return for gross estates of $1,000,000 or more, and Massachusetts above $2,000,000. Washington's exclusion is $3,000,000 for deaths on or after July 1, 2026, when its top rate fell from 35 to 20 percent. New York's $7,350,000 exclusion disappears entirely once the taxable estate exceeds 105 percent of it.
Someone who moves to Portugal but keeps a Boston house, license, and voter registration may still be domiciled in Massachusetts, which, like Oregon, also taxes nonresidents' in-state real estate and tangible property. See State Taxes After Moving Abroad for how to cut domicile cleanly.
Is renouncing citizenship the only real exit, and what does it cost?
Giving up U.S. citizenship is the one step that removes you from the federal estate tax on worldwide assets. As estate planning, it's rarely the answer.
In a final rule published on March 13, 2026, and effective 30 days later, the State Department lowered the renunciation fee from $2,350 to $450. If you're a "covered expatriate," you pay an exit tax on unrealized gains as if you had sold your worldwide assets the day before expatriating (§ 877A). You are covered if you meet any one of three tests: net worth of $2 million or more; average annual net income tax over the prior five years above $211,000 for 2026; or failure to certify five years of U.S. tax compliance (§ 877(a)(2); Rev. Proc. 2025-32). Gains above an exclusion of $910,000 for 2026 are taxed. Long-term green card holders who give up their status are subject to the same regime. For the full mechanics, see our U.S. exit tax guide, or estimate your own exposure with our exit tax tool.
The bigger estate planning problem comes later. Gifts and bequests from a covered expatriate to a U.S. citizen or resident are taxed under § 2801 at the highest estate tax rate, 40 percent, to the extent they exceed the annual exclusion amount ($19,000 for 2026), less any foreign gift or estate tax paid on the transfer. The tax is paid by the American recipient, not the expatriate. Final regulations (T.D. 10027, published January 14, 2025) apply to gifts and bequests received on or after January 1, 2025, and recipients report on Form 708.
If your children stay American, renouncing doesn't remove the tax. It shifts it to them, with almost no exemption. Our worked example of a renunciation from Italy runs the numbers on both the exit tax and § 2801. Renunciation can make sense when the heirs aren't American and the estate is very large, but it's a life decision with tax consequences, not the reverse.
Common mistakes
- Leaving everything to a noncitizen spouse with no QDOT or lifetime gifting plan.
- Ignoring the foreign spouse's U.S. stocks, taxable above about $60,000.
- Forgetting where the heirs live. A child in Germany, Spain, or France can owe tax whatever your address.
- Keeping a revocable living trust without local advice.
- Letting one will revoke the other.
- Relying on the § 2014 credit in a non-treaty country for U.S.-situs assets.
- Keeping ties to a U.S. state with an estate tax.
- Missing Form 3520 on a foreign inheritance above $100,000.
- Treating renunciation as estate planning when your heirs are American.
Before you go
- Map where your assets are, where your heirs live, and everyone's citizenships.
- Check the IRS treaty list for your new country and your heirs' countries.
- Learn whether the new country taxes estates, heirs, or both.
- With a noncitizen spouse, plan for the $194,000 annual exclusion, a QDOT, or both.
- In the EU, choose the governing law in your will, naming the U.S. state.
- Coordinate U.S. and local wills.
- Have a local adviser review any U.S. trust.
- Cut domicile in your last state.
- Review beneficiary designations (see U.S. Retirement Accounts Abroad).
- Keep records supporting your residence (see Dual Tax Residency).
- Revisit the plan whenever you move, marry, or the law changes.
So, where should you move?
For an American, no country changes the federal estate tax. The useful question is which country adds the least on top of it and lets your U.S. plan work as written.
On tax alone, the strongest choices are countries with no inheritance tax, or one that spares close family: Portugal, Singapore, Hong Kong, Australia, Mexico, and, depending on the canton, Switzerland. A U.S. estate tax treaty matters more in countries that do tax, such as France, Germany, Japan, and Italy, where it reduces the risk of paying twice. The riskiest combination is a country with a meaningful inheritance tax and no treaty, such as Spain or South Korea, especially for estates large enough to owe U.S. tax.
Tax is only half of it. Civil law can override your U.S. will, local rules can penalize your trust, and your children's address can matter as much as yours. A country with no estate tax solves one problem; choosing the governing law, aligning your wills, planning for a noncitizen spouse, and cutting state domicile solve the rest. That's why moving is almost never enough.
A note on scope: this article provides general information for U.S. citizens and green card holders and is not tax or legal advice. Tax and succession rules change, and their application depends on your facts. Consult a qualified U.S. tax adviser and a lawyer in each country involved before acting.
FAQ: estate planning for Americans abroad
Does moving abroad remove me from the US estate tax?
No. The federal estate tax applies to every US citizen's worldwide estate regardless of where they live or die — a brokerage account in Lisbon or a farmhouse in Umbria counts the same as US property. The only way a citizen fully exits the system is by renouncing citizenship, which carries its own costs.
What is the US estate tax exclusion for 2026?
$15,000,000 per person, with a top rate of 40 percent above that amount. Lifetime taxable gifts use up the same exclusion, and a surviving spouse can inherit any unused portion of a deceased spouse's exclusion by filing a timely Form 706, even when no tax is due.
Does the unlimited marital deduction apply if my spouse isn't a US citizen?
No. Leaving everything tax-free to a spouse only works for a US citizen spouse. For a noncitizen spouse, the main option is a qualified domestic trust (QDOT), which defers the tax rather than removing it and comes with its own trustee and distribution requirements. During life, gifts to a noncitizen spouse instead get a special annual exclusion, $194,000 for 2026, separate from the regular $19,000 annual gift exclusion.
Does the United States have an estate tax treaty with every country?
No, only 15: Australia, Austria, Canada, Denmark, Finland, France, Germany, Greece, Ireland, Italy, Japan, the Netherlands, South Africa, Switzerland and the United Kingdom. Spain, Portugal, Mexico and nearly every other country in Latin America and Asia have no US estate tax treaty, however good their income tax treaty is, which leaves only a narrower unilateral foreign death tax credit to prevent double taxation.
Can a foreign country force my children to inherit against my wishes, even with a US will?
Yes, in civil law countries with forced heirship. France reserves half the estate for one child, two-thirds for two, and three-quarters for three or more, regardless of what a will says. In the EU, the Succession Regulation lets you choose the law of your US state in your will instead of your country of residence, but that choice only changes who inherits, not which country taxes the estate, and France has added a compensatory claim for EU-connected children even when a foreign law is chosen.
Does renouncing US citizenship solve the estate tax problem if my children are American?
No, it generally shifts the tax rather than removing it. Gifts and bequests from a "covered expatriate" to a US citizen or resident are taxed under §2801 at the highest estate tax rate, 40 percent, and that tax is paid by the American recipient, not the person who renounced. Renunciation can still make sense for a very large estate when the heirs are not American, but it rarely helps when they are.
Sources
Primary sources (accessed October 29, 2026)
United States
- 26 U.S.C. § 2001 (estate tax rates)
- 26 U.S.C. § 2010 (unified credit, basic exclusion amount)
- 26 U.S.C. § 2014 (credit for foreign death taxes)
- 26 U.S.C. § 2056 (marital deduction)
- 26 U.S.C. § 2056A (qualified domestic trust)
- 26 U.S.C. § 2102 (credits for nonresident noncitizens)
- 26 U.S.C. § 2104 (property within the United States)
- 26 U.S.C. § 2105 (property without the United States)
- 26 U.S.C. § 2501 (gift tax)
- 26 U.S.C. § 2503 (annual exclusion)
- 26 U.S.C. § 2511 (transfers in general)
- 26 U.S.C. § 2523 (gifts to spouse)
- 26 U.S.C. § 2801 (gifts and bequests from expatriates)
- 26 U.S.C. § 877 (expatriation)
- 26 U.S.C. § 877A (exit tax)
- 26 U.S.C. § 1014 (basis of inherited property)
- 26 U.S.C. § 1015 (basis of gifted property)
- 26 U.S.C. § 6039F (reporting of foreign gifts)
- Treas. Reg. § 20.0-1 (definition of resident)
- Treas. Reg. § 20.2010-2 (portability)
- Treas. Reg. § 20.2056A-2 (QDOT requirements)
- Treas. Reg. § 28.6071-1 (Form 708 due date and applicability)
- IRS, Rev. Proc. 2025-32 (2026 inflation adjustments)
- IRS, Instructions for Form 706
- IRS, Instructions for Form 706-NA
- IRS, Some nonresidents with U.S. assets must file estate tax returns
- IRS, Estate & gift tax treaties (international)
- IRS, Internal Revenue Manual 4.25.4 (estate tax treaties)
- IRS, Instructions for Form 708
- IRS, Instructions for Form 3520
- Federal Register, T.D. 10027, final regulations under § 2801 (January 14, 2025)
- Federal Register, Department of State, fee for certificate of loss of nationality (March 13, 2026)
- U.S. Treasury, Technical Explanation of the 1998 U.S.-Germany estate and gift tax protocol
- U.S. Senate, Executive Report 104-9 on the U.S.-Canada protocol
- Oregon Department of Revenue, Estate transfer tax
- Massachusetts Department of Revenue, Estate tax guide
- Washington Department of Revenue, Estate tax tables
- Washington State Legislature, Final bill report ESB 6347 (2026)
- New York Department of Taxation and Finance, Estate tax
- Comptroller of Maryland, Form MET-1 (2026)
- Maryland Register of Wills, Inheritance and estate taxes
European Union and international
- Regulation (EU) No 650/2012 (EU Succession Regulation)
- HCCH, status table, 1961 Convention on the form of testamentary dispositions
- HCCH, status table, 1985 Convention on the law applicable to trusts
- UNIDROIT, status of the 1973 Convention on international wills
Other countries
- France, Service-Public, Réserve héréditaire
- France, Loi n° 2021-1109 of August 24, 2021
- France, impots.gouv.fr, Calcul et paiement des droits
- France, BOFiP, territoriality of transfer taxes (BOI-ENR-DMTG-10-10-30)
- France, BOFiP, trusts (BOI-ENR-DMTG-30)
- France, BOFiP, trust reporting penalties (BOI-CF-INF-20-10-50)
- France, BOFiP, life insurance levy (BOI-TCAS-AUT-60)
- Germany, ErbStG § 2
- Germany, ErbStG § 16
- Germany, ErbStG § 19
- Germany, BGB § 2303
- Spain, Ley 29/1987 (consolidated text, BOE)
- Spain, Agencia Tributaria, nonresidents and inheritance tax FAQ
- Italy, D.Lgs. 139/2024 (Normattiva)
- Italy, Law 199/2025 (Normattiva)
- Italy, Agenzia delle Entrate, optional regime for new residents and rules and guidance, including Circular 17/E of 2017
- Portugal, Tabela Geral do Imposto do Selo
- Portugal, Código do Imposto do Selo, art. 6
- United Kingdom, HMRC Inheritance Tax Manual IHTM47020
- United Kingdom, Inheritance tax double taxation relief
- Ireland, Revenue, CAT thresholds
- Ireland, Revenue, CAT notes for guidance, Part 3
- Netherlands, Successiewet 1956
- Netherlands, Belastingdienst, inheritance abroad
- Switzerland, ESTV, inheritance and gift taxes (PDF)
- Switzerland, Federal Department of Finance, JUSO initiative
- Canada, Income Tax Act s. 70
- Canada, CRA, capital gains on death
- Canada, Department of Finance, Canada-U.S. tax convention (consolidated)
- Mexico, SAT, Ley del ISR art. 93
- Brazil, Constitutional Amendment 132/2023
- Brazil, Federal Senate, ITCMD 8 percent cap
- Japan, National Tax Agency, inheritance tax rates
- Japan, National Tax Agency, inheritance tax (English)
- South Korea, Inheritance and Gift Tax Act (law.go.kr)
- Singapore, IRAS, Estate duty
- Hong Kong, Inland Revenue Department, Estate duty
- Australia, ATO, If you are a beneficiary of a deceased estate
- UAE government portal, Taxation
- UAE, Federal Decree-Law No. 41 of 2022
- UAE, DIFC Courts, Wills FAQ
A note on method: the US figures in this article were checked against the Internal Revenue Code and Revenue Procedure 2025-32, the treaty rules against the treaty texts, and the civil law rules against the French Code civil, the German BGB and Regulation (EU) No 650/2012. Where only a secondary source was available, the text labels it; where no official source settles a question, the text says so. Paraphrases are ours, so check the cited text before you rely on it.