Research date: November 3, 2026. Every rate, threshold and treaty status below is stated "as of" that date unless a different date is given. Ghana changed its personal income tax bands on September 1, 2026, and its VAT law on January 1, 2026, so check for later changes before you rely on any number here.
Key takeaways
- You still file a US return. The US taxes citizens and green card holders on worldwide income no matter where they live. Moving to Accra or Kumasi changes how you file, not whether you file.
- There is no US–Ghana income tax treaty. Ghana is not on the IRS list of treaty countries, and PwC's own list agrees (IRS; PwC); the United States is not on the Ghana Revenue Authority's list of Ghana's double tax agreements either (Ghana Revenue Authority). The only income tax agreement we found between the two countries is a narrow 2001 exchange of notes that exempts income from international shipping and aircraft operations (UN Treaty Series; Texas A&M Libraries catalogue, secondary). It does nothing for individuals.
- There is no totalization agreement. The US has 31 Social Security agreements in force, and none is with an African country (SSA). A 1973 US–Ghana exchange of notes is catalogued under "social security" (Monthly Catalog of US Government Publications, secondary), but it is not a totalization agreement (see the social security section below).
- Ghana has no FATCA intergovernmental agreement. Ghana does not appear on Treasury's list of FATCA agreements (US Treasury), so Ghanaian banks that comply do so by registering directly with the IRS.
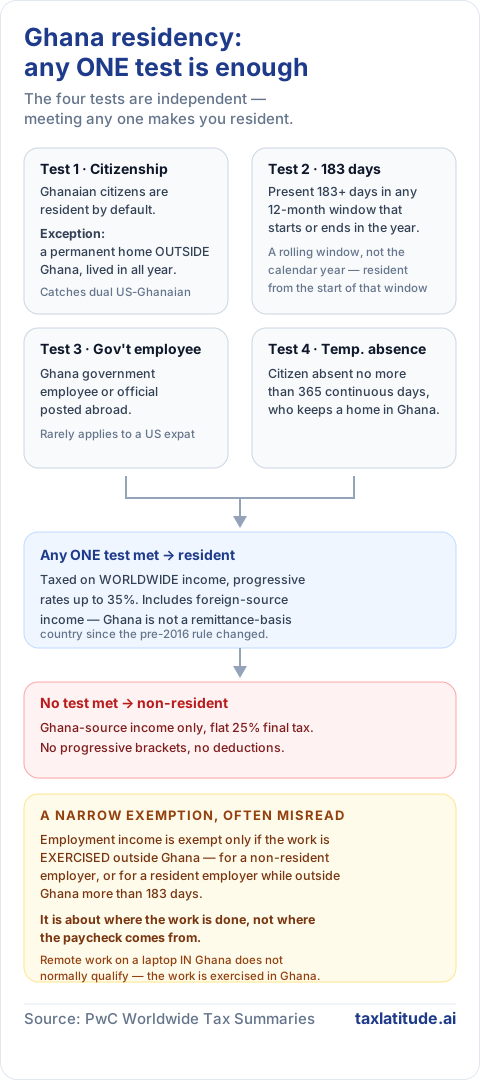
- Ghana taxes its residents on worldwide income. You become resident if you are in Ghana for 183 days or more in any 12-month period that starts or ends in the year (PwC). Ghanaian citizens, including Americans who took Ghanaian citizenship, are resident unless they keep a permanent home abroad and live there all year (PwC).
- New Ghana rates from September 1, 2026. The Income Tax (Amendment) Act, 2026 (Act 1178) raised the tax-free band to GHS 7,056 a year (GHS 588 a month). The top rate stays at 35% on income above GHS 600,000 a year (Ghana Revenue Authority).
- Ghana's rates are high enough that the Foreign Tax Credit often beats the Foreign Earned Income Exclusion for people on a Ghanaian payroll. Self-employed Americans owe US self-employment tax whichever they choose, because neither the exclusion nor the credit reduces it (IRS / Greenback, secondary).
- Foreigners cannot own freehold land in Ghana. A non-citizen can hold a lease of no more than 50 years at any one time (MyJoyOnline, secondary).
Do Americans living in Ghana still file US taxes?
Yes. US citizens and resident aliens report worldwide income on Form 1040 whether they live in the United States or abroad (IRS). Living in Ghana gives you some relief tools and some extra time, but the filing duty stays.
When the return is due. If your tax home and your home are both outside the United States on the regular April due date, you get an automatic two-month extension to June 15 (IRS). You attach a statement saying which condition you meet. You can push the filing date to October 15 by filing Form 4868 (IRS). The extension is for filing only: interest runs on any unpaid tax from the April date.
Separate reports for foreign accounts. If your Ghanaian (and other non-US) financial accounts together exceed $10,000 at any point in the year, you file an FBAR (FinCEN Form 114) with FinCEN. It is due April 15 with an automatic extension to October 15 (FinCEN). Section 7 covers the other forms.
The main 2026 numbers you will use:
| Item | Tax year 2025 | Tax year 2026 | Source |
|---|---|---|---|
| Foreign Earned Income Exclusion, per qualifying person | $130,000 | $132,900 | (IRS; IRS Newswire) |
| FBAR threshold (aggregate, at any time in the year) | $10,000 | $10,000 | (FinCEN) |
| Form 8938, single filer living abroad | >$200,000 at year end or >$300,000 at any time | same | (Greenback Expat Tax Services, secondary) |
| Form 8938, married filing jointly, living abroad | >$400,000 at year end or >$600,000 at any time | same | (Greenback Expat Tax Services, secondary) |
If you have fallen behind. Americans abroad who did not file because they did not know they had to can often use the IRS Streamlined Foreign Offshore Procedures. Practitioners describe the core package as three years of returns, six years of FBARs and a signed certification that the failure was non-willful, with no penalty for eligible filers who meet the non-residency test (Taxes for Expats, secondary). Read the IRS's own program page before you file, and get help if there is any question about willfulness.
When does Ghana treat you as a tax resident, and what does it tax?
What is the governing law?
Ghana's income tax law is the Income Tax Act, 2015 (Act 896), as amended. It is still the current law. The most recent amendment as of the research date is the Income Tax (Amendment) Act, 2026 (Act 1178), which was assented to on August 26, 2026 (3News, secondary)and which the Ghana Revenue Authority (GRA) implemented from September 1, 2026 (Ghana Revenue Authority). Act 1178 changed the First Schedule (individual rates) and the Second Schedule (the presumptive tax threshold) (3News, secondary). Earlier recent amendments include Act 1094 (2023), Act 1111 (2023) and Act 1129 (2025) (KPMG Ghana; 3News, secondary; EY).
What are the residence tests?
You are resident in Ghana for a year if any one of these applies (PwC):
- You are a Ghanaian citizen, unless you have a permanent home outside Ghana and live in it for the whole year.
- You are present in Ghana for 183 days or more in any 12-month period that starts or ends during the year.
- You are an employee or official of the Government of Ghana posted abroad during the year.
- You are a citizen temporarily absent for no more than 365 continuous days who keeps a permanent home in Ghana.
Two practical points:
- Resident for part of the year means resident for the whole year. PwC's summary says a person resident at any time in a year is treated as resident for that year (PwC). A secondary Ghanaian source adds that someone who becomes resident under the 183-day rule is treated as resident from the start of the relevant 183-day period (TaxLawGH, secondary).
- Dual citizens are caught by test 1. Ghana has granted citizenship to hundreds of members of the African diaspora, most of them Black Americans; 524 people received it at a single ceremony in November 2024 (theGrio / AP, secondary). If you are one of them and you live in Ghana, test 1 makes you resident regardless of day counts.
What does Ghana tax?
Residents are taxed on worldwide income. PwC states this directly, and foreign-source income is taxable (PwC). The GRA publicly confirmed in April 2024 that resident individuals are taxed on foreign income under Act 896 (Ghana Revenue Authority). This is a change from the pre-2016 law (Act 592), which taxed a resident's foreign income only when it was brought into Ghana (Ghanaian Times, secondary). Ghana is not a remittance-basis country today.
One exemption to know. Employment income is exempt if a resident exercises the employment outside Ghana and either works for a non-resident employer, or works for a resident employer and is outside Ghana for more than 183 days (PwC). This exemption is about work done outside Ghana. Our reading is that it would not normally cover an American working remotely from a laptop in Ghana, because that work is exercised in Ghana.
Non-residents are taxed only on Ghana-source income, at a flat 25% (PwC).
What are the resident income tax rates?
From September 1, 2026, under Act 1178 (Ghana Revenue Authority; PwC):
| Annual chargeable income (GHS) | Rate |
|---|---|
| First 7,056 | 0% |
| Next 960 | 5% |
| Next 1,200 | 10% |
| Next 34,800 | 17.5% |
| Next 192,000 | 25% |
| Next 363,984 | 30% |
| Above 600,000 | 35% |
The monthly PAYE version starts with GHS 588 tax-free and reaches 35% above GHS 50,000 a month (Ghana Revenue Authority).
January to August 2026 payroll used the previous Act 1111 bands, which had a tax-free band of GHS 5,880 a year (GHS 490 a month) (Firmus Advisory, secondary). No GRA guidance addresses how the two scales combine in the annual assessment for 2026, so expect your 2026 Ghana return to need care.
Illustration (our arithmetic, Act 1178 annual scale applied to a full year, before reliefs):
| Annual chargeable income | Ghana tax | Average rate |
|---|---|---|
| GHS 60,000 | GHS 10,254 | 17.1% |
| GHS 120,000 | GHS 25,254 | 21.0% |
| GHS 300,000 | GHS 73,453 | 24.5% |
| GHS 800,000 | GHS 233,453 | 29.2% |
Other income types
- Dividends: 8% final withholding tax for residents and non-residents (PwC).
- Interest: interest paid to individuals by a resident financial institution is exempt, and so is interest on Ghana government bonds and treasury bills (PwC).
- Rent: GRA's rent tax is 8% for residential premises and 15% for commercial premises (Ghana Revenue Authority). It is due within 30 days of receiving the rent (The Ghana Report, secondary, quoting GRA).
- Gifts: included in income at your marginal rate, or you may elect a flat 25% on gifts not connected with business or employment (PwC).
- Capital gains: see the Ghana-specific rules section below.
How do you file in Ghana?
Ghana's tax year is the calendar year. The annual return is due within four months after year end, which is April 30 (PwC). For individuals, your Ghana Card PIN is your Taxpayer Identification Number, and GRA says expatriates should obtain a non-citizen Ghana Card to carry out tax transactions (Ghana Revenue Authority). Individuals who are not eligible for a Ghana Card, such as some non-residents, are issued a GRA TIN instead (GRA, via OECD).
Is there a US-Ghana tax treaty?
No. As of November 3, 2026:
- Ghana is not in the IRS's Table 3 list of tax treaties (updated through September 26, 2025) (IRS).
- PwC's US summary, last reviewed September 4, 2026, lists 67 US treaty partners. Ghana is not one of them (PwC).
- GRA's published status table of Ghana's double taxation agreements (June 2023 version, the latest we found) does not include the United States, either as in force or under negotiation (Ghana Revenue Authority).
What is the shipping and aircraft agreement (2001)?
What does exist is an exchange of notes between the United States and Ghana that exempts certain income from the international operation of ships and aircraft from income tax, on a reciprocal basis. The notes were exchanged at Accra on April 24 and November 12, 2001. The agreement is registered with the UN as No. 51038 (UN Treaty Series)and published by the State Department as TIAS 13171 (Texas A&M Libraries catalogue, secondary).
Correction to a common assumption: this shipping and aircraft agreement dates from 2001, not 1973. The separate 1973 instrument is catalogued under a different subject (see the social security section below).
The 2001 agreement is not a general income tax treaty. Its registered title and description cover only income from the international operation of ships and aircraft (UN Treaty Series). Nothing in that description touches employment income, pensions, dividends or residence, so it does nothing for an individual American living in Ghana.
What does having no treaty mean for you?
- No tie-breaker. If both countries consider you a taxpayer, nothing settles which one has the first right to tax. In practice the US gives a credit for Ghana tax, and Ghana gives a credit for foreign tax on foreign income (see the double-taxation section below).
- No reduced withholding rates. Ghana's domestic withholding rates apply to you in full.
- No treaty pension rules. How each country taxes pensions, including SSNIT payouts and US retirement accounts, follows each country's own domestic law.
- No treaty competent-authority process. IRS guidance (2013 edition of Publication 54) notes that the US competent authority cannot take requests involving countries without a tax treaty (IRS).
How do you avoid paying tax twice?
You have two main US tools and one Ghanaian one.
Foreign Earned Income Exclusion (FEIE), Form 2555
- Excludes up to $132,900 of foreign earned income for 2026 ($130,000 for 2025) (IRS; IRS Newswire). Each spouse who qualifies can claim it.
- You need a foreign tax home and either the bona fide residence test or the physical presence test (330 full days in a foreign country or countries during a 12-month period) (IRS).
- You only get the exclusion if you file a return and claim it (IRS).
- It covers earned income only: wages and self-employment income for work done abroad. It does not cover dividends, interest, rent or capital gains.
- It does not reduce self-employment tax (IRS / Greenback, secondary).
Foreign Tax Credit (FTC), Form 1116
- Gives a dollar-for-dollar credit for qualifying foreign income taxes. The credit cannot exceed your US tax multiplied by the share of your taxable income that comes from foreign sources (IRS).
- Ghana's top resident rate is 35% (PwC). The 25% band starts at GHS 44,016 of annual chargeable income and the 30% band at GHS 236,016 (our arithmetic from (Ghana Revenue Authority)). For many people on a Ghanaian payroll, Ghana tax will be at or above the US tax on the same wages, so the FTC can bring the US bill on that income to zero and leave excess credits to carry forward.
- Watch the gross-basis taxes. Some Ghanaian taxes are charged on gross amounts, not net income: the 8% final rent tax (Ghana Revenue Authority)and the 3% presumptive tax on business turnover (Ghana-specific rules) (Ghana Revenue Authority). Whether a gross-basis tax counts as a creditable "income tax" under US rules is a technical question. The IRS has offered relief from the strictest parts of the 2022 creditability regulations "until further notice" (Notice 2023-80, extending Notice 2023-55) (KPMG Flash Alert, secondary). Ask your preparer to check each Ghanaian tax before you rely on a credit for it.
FEIE or FTC?
| Your situation | Usually worth testing first |
|---|---|
| Salaried on a Ghanaian payroll, Ghana PAYE deducted | FTC |
| Remote worker for a US employer, under 183 days in Ghana (non-resident) but outside the US 330+ days in total, no Ghana tax paid | FEIE |
| Remote worker in Ghana 183+ days (so Ghana-resident) | Run both; Ghana tax on the salary may make the FTC better |
| Self-employed or freelance | Either for income tax; you still owe US self-employment tax (IRS / Greenback, secondary) |
| Investment-heavy income (dividends, rent, gains) | FTC; the FEIE does not apply to unearned income |
Model both before you commit. Switching between them from year to year has consequences, so ask your preparer before changing methods.
What is Ghana's own foreign tax credit?
If you are resident in Ghana and paying US tax on US-source income (a US rental, say, or US dividends), Ghana gives a credit for foreign tax under section 112 of Act 896. A secondary Ghanaian source describes it as calculated by year and separately for foreign employment, business and investment income, capped at your average Ghana rate on that foreign income, and requiring a certificate or receipt from the foreign tax authority (TaxLawGH, secondary). Keep your IRS account transcripts and 1099s for this purpose.
Social security: is there a totalization agreement with Ghana?
No. As of November 3, 2026, SSA lists 31 totalization agreements in force: Australia, Austria, Belgium, Brazil, Canada, Chile, the Czech Republic, Denmark, Finland, France, Germany, Greece, Hungary, Iceland, Ireland, Italy, Japan, South Korea, Luxembourg, the Netherlands, Norway, Poland, Portugal, Romania (effective September 1, 2026), the Slovak Republic, Slovenia, Spain, Sweden, Switzerland, the United Kingdom and Uruguay (SSA). None is in Africa, and Ghana is not listed (SSA).
What is the 1973 US–Ghana instrument, and what is it not?
There is a 1973 US–Ghana exchange of notes. The US Government's own catalogue lists it as Treaties and Other International Acts Series (TIAS) No. 7734, titled "Social security, agreement between United States and Ghana," effected by notes dated at Accra May 16, September 10 and October 30, 1973, and in force from October 30, 1973 (Monthly Catalog of US Government Publications, secondary).
The text of TIAS 7734 itself proved unavailable, so its exact subject beyond the catalogue title cannot be stated. What we can confirm from primary sources:
- It is not the shipping and aircraft tax agreement. That agreement is TIAS 13171 and dates from 2001 (UN Treaty Series; Texas A&M Libraries catalogue, secondary).
- It cannot be a totalization agreement. The US legal authority for totalization agreements, section 233 of the Social Security Act, was enacted in the 1977 amendments (SSA Social Security Bulletin). The first US agreement, with Italy, was signed in 1973 but could not take effect until that law passed (SSA Social Security Bulletin). A 1973 exchange of notes with Ghana had no such authority behind it.
- SSA does not treat it as one. Ghana is absent from SSA's list of agreements (SSA). SSA has explained that some diplomatic notes are informally called "social security agreements," but unlike section 233 agreements they bind the US to nothing and are not technically international agreements (SSA Social Security Bulletin).
- It does not unlock benefit payments either. SSA's operations manual lists Ghana as meeting neither the "social insurance" exception nor the "treaty" exception to the rule that stops paying benefits to non-citizens who stay outside the US for long periods (SSA POMS RS 02610.015).
Whatever its exact content, SSA does not treat the 1973 note as an agreement that prevents double contributions, combines US and Ghanaian work credits, or supports a certificate of coverage. Treat Ghana as a no-totalization country.
What does this mean in practice?
Self-employed Americans in Ghana owe US self-employment tax (15.3% on net earnings up to the Social Security wage base, then the Medicare part) whether they use the FEIE or the FTC (IRS / Greenback, secondary). With no agreement, nothing exempts them.
Self-employed and paying into Ghana's SSNIT pension? With no totalization agreement between the US and Ghana, you can owe the 5.5% employee SSNIT contribution and the full 15.3% US self-employment tax on the same earnings — neither the FEIE nor the credit reduces the US side. Check your real contribution burden →
Employees of a Ghanaian employer generally fall under Ghana's mandatory pension scheme. Under the National Pensions Act, 2008 (Act 766), the contribution is 18.5% of basic salary: 5.5% from the employee and 13% from the employer (SSNIT; PwC). For 2026, SSNIT raised the maximum insurable earnings to GHS 69,000 a month, with a maximum monthly Tier 1 contribution of GHS 9,315, which is 13.5% of GHS 69,000, the Tier 1 share (SSNIT; PwC).
Expatriate exemption. Expatriates must contribute unless exempt (PwC). KPMG reported in 2018 that the regulator allows an exemption for expatriates on contracts of no more than 36 months who can prove they contribute to a scheme at home (KPMG Flash Alert). The regulator's 2017 guidelines for registering expatriate workers apply where Ghana has no reciprocal social security agreement with the worker's country (NPRA). If you are still covered by US Social Security, for example through a US employer's payroll, ask your Ghanaian employer about applying for this exemption.
Getting SSNIT money out when you leave. SSNIT pays an emigration benefit, as a lump sum, to non-Ghanaian members who leave Ghana permanently (SSNIT).
Receiving US Social Security in Ghana. Ghana is not on the Treasury restricted-country list in SSA's regulations, which as of the research date names only Cuba and North Korea (20 CFR 404.460). Use SSA's Payments Abroad Screening Tool to confirm your own case.
Which US forms apply to accounts and assets in Ghana?
| Form | When a Ghana resident typically needs it | Source |
|---|---|---|
| Form 1040 | Every year your income meets the filing threshold | (IRS) |
| Form 2555 | To claim the FEIE (or housing exclusion/deduction) | (IRS) |
| Form 1116 | To claim the Foreign Tax Credit for Ghana tax | (IRS) |
| Schedule SE | Net self-employment earnings of $400 or more | (IRS / Greenback, secondary) |
| FinCEN 114 (FBAR) | Non-US accounts together exceed $10,000 at any time in the year | (FinCEN) |
| Form 8938 | Specified foreign financial assets above $200,000 at year end / $300,000 at any time (single, living abroad); $400,000 / $600,000 (joint) | (Greenback Expat Tax Services, secondary) |
| Form 8621 | You hold a Ghanaian mutual fund, unit trust or similar pooled fund that is a PFIC | (IRS) |
| Form 5471 | You own 10% or more of, or are an officer or director of, certain Ghanaian companies | (IRS) |
| Form 3520 | You receive gifts or bequests totaling more than $100,000 in a year from a nonresident alien individual or foreign estate (a lower threshold applies to gifts from foreign companies or partnerships) | (IRS) |
Notes specific to Ghana:
- Ghanaian banks may report you. Because Ghana has no FATCA IGA (US Treasury), Ghanaian banks that want to avoid FATCA withholding register directly with the IRS. By July 2015, 55 Ghanaian financial institutions had registered (Graphic Online, secondary, older figure). Expect your Ghanaian bank to ask whether you are a US person.
- Ghanaian collective investment schemes. A Ghanaian mutual fund or unit trust is likely to be a PFIC under US rules, and a separate Form 8621 is generally required for each PFIC (IRS; see our Form 8621 guide). PFIC taxation is harsh. Holding long-term investments in US-domiciled funds avoids the problem.
Holding a Ghanaian mutual fund or unit trust? These are likely PFICs under US rules, with a separate Form 8621 required for each one and punitive default taxation if you don't elect out. Find out if your Ghanaian fund is a PFIC →
- Tier 2 and Tier 3 pension accounts. Tier 2 is a mandatory occupational scheme and Tier 3 is voluntary, with contributions paid to approved fund managers (PwC). How the US treats them (as a foreign trust, a PFIC holding, or something else) has no Ghana-specific IRS guidance that we found. Get advice before you report them.
- Mobile money wallets. No IRS or FinCEN guidance addresses whether a Ghanaian mobile money wallet is a "financial account" for FBAR purposes. The cautious approach is to include significant balances. Discuss it with your preparer.
- Your Ghanaian company. If you incorporate a Ghanaian company, Form 5471 is a separate return for each foreign corporation, and late or inaccurate filing can bring penalties and reduce your foreign tax credit (IRS). Practitioners report a $10,000 penalty per form per year (Greenback Expat Tax Services, secondary).
Incorporating a Ghanaian company? Practitioners report a $10,000 penalty per Form 5471 per year for late or inaccurate filing — and a missed filing can also reduce your foreign tax credit. Check your filing obligation before you incorporate →
- Sending money from the US to Ghana. Since January 1, 2026, a 1% US excise tax applies to remittances that the sender funds with cash, a money order, a cashier's check or a similar physical instrument (KPMG, secondary). Transfers funded from a bank account or by card are not caught by that rule. The tax turns on how the transfer is funded, not on the sender's citizenship or residence (Greenback Expat Tax Services, secondary).
Ghana-specific rules that need their own section
We checked each mechanism in the brief. Here is what exists and what does not, as of November 3, 2026.
8a. Capital gains: taxed as income, with a 25% election (confirmed)
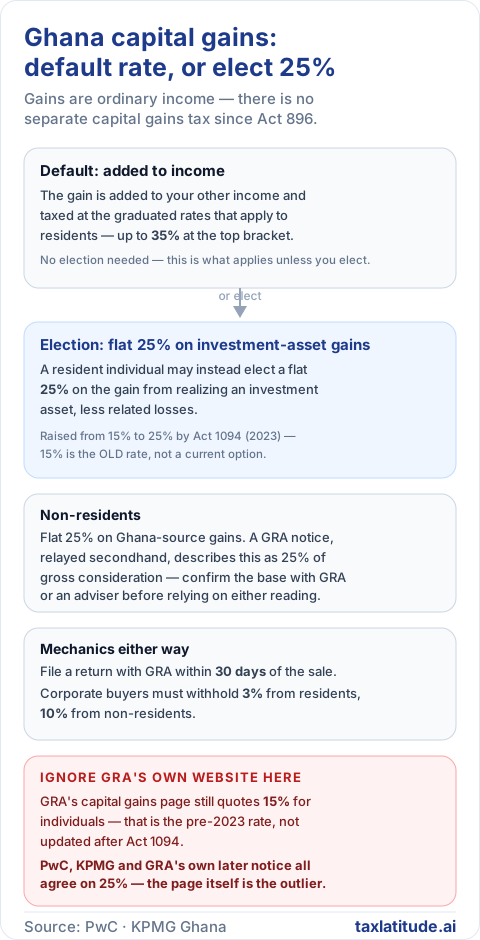
Ghana no longer has a separate capital gains tax. Gains on realising assets are part of income under Act 896 (PwC; EY Worldwide Personal Tax Guide).
- Default: a resident individual's gain is added to income and taxed at the graduated rates, up to 35% (PwC).
- Election: a resident individual may instead elect to pay 25% on the gain from realising an investment asset, less related losses (PwC). Act 1094 raised this elective rate from 15% to 25% in 2023 (KPMG Ghana).
- Non-residents are taxed on gains at 25% (PwC). A GRA notice, as relayed by a secondary source, describes this as a final 25% tax on the gross consideration (Regfollower, secondary). The two descriptions differ, so a non-resident seller should confirm the base with GRA or an adviser.
- Return within 30 days. Since Act 1094, anyone who realises an asset or liability must file a return with GRA within 30 days (KPMG Ghana; Regfollower, secondary).
- Withholding by buyers. Persons other than individuals who pay for investment or capital assets must withhold 3% from residents and 10% from non-residents (KPMG Ghana).
- Your main home. GRA's notice lists land and buildings "other than your primary residence" among the assets that attract the tax, relaying a primary GRA notice (Regfollower, secondary).
A warning about GRA's own website. GRA's capital gains page still describes a 15% rate for individuals (Ghana Revenue Authority). That reflects the law before Act 1094. PwC (PwC), KPMG (KPMG Ghana)and GRA's own later notice (Regfollower, secondary)all give 25%.
US side: you report the same gain on your US return. Ghana tax paid on it can generally be credited on Form 1116, subject to the US source and limitation rules (IRS). Because your US basis is in dollars and your Ghana basis is in cedis, currency movements can make the US gain larger or smaller than the Ghana gain. Keep purchase records with dates.
8b. Presumptive (turnover) tax for small businesses (confirmed, changed September 2026)
From September 1, 2026, individuals whose annual business turnover is more than GHS 20,000 and no more than GHS 750,000 pay a presumptive tax of 3% of annual turnover (Ghana Revenue Authority). A secondary source says the previous ceiling was GHS 500,000 (Firmus Advisory, secondary). An older EY guide describes the modified basis as available to individuals whose business income comes only from Ghanaian sources, though from an older edition (EY Worldwide Personal Tax Guide).
This matters if you run a small shop, guesthouse or service business. Note the US credit question in the double-taxation section above: a tax on turnover is not a tax on net income.
8c. Controlled foreign company (CFC) rules: none
PwC's Ghana summary, last reviewed October 27, 2026, says Ghana's tax laws contain no express CFC provisions (PwC). Ghana does have transfer pricing and thin capitalisation rules (PwC). (The US CFC regime still applies to you if you control a foreign company. See Form 5471 above.)
8d. Minimum tax for individuals: none found
No alternative minimum tax for individuals turned up in GRA, PwC, KPMG or EY materials. The nearest things are the presumptive turnover tax (8b) and the Growth and Sustainability Levy, which KPMG describes as a levy on companies by sector (on profit before tax or gross production) (KPMG Ghana). The levy's Amendment Act, 2025 (Act 1131) extended it through the 2028 year of assessment (Growth and Sustainability Levy (Amendment) Act 2025).
8e. Exit realisation when you stop being resident (reported by a secondary source only)
See the Leaving Ghana section below.
8f. Recent reforms you will notice (2025–2026)
| Change | Effective | What it means | Source |
|---|---|---|---|
| E-Levy (1% on electronic transfers, including mobile money) abolished | April 2, 2025 | No more E-Levy on MoMo or bank transfers | (EY) |
| 10% withholding on lottery and betting winnings abolished | April 2, 2025 | — | (Graphic Online, secondary) |
| VAT Act, 2025 (Act 1151) replaces Act 870 | January 1, 2026 | Standard VAT stays 15%; 1% COVID-19 levy abolished; effective combined rate about 20% with NHIL and GETFund; flat-rate scheme abolished; goods registration threshold up to GHS 750,000 | (EY; Ghana Revenue Authority) |
| Income Tax (Amendment) Act, 2026 (Act 1178) | September 1, 2026 | New personal bands; presumptive tax ceiling raised to GHS 750,000 | (Ghana Revenue Authority) |
| SSNIT maximum insurable earnings raised to GHS 69,000 | January 1, 2026 | Higher Tier 1 contribution cap | (SSNIT) |
Local considerations
Working for a Ghanaian employer
Your employer runs PAYE using the monthly bands (Ghana Revenue Authority)and deducts your 5.5% SSNIT contribution (SSNIT). If you are paid in cedis, your US return reports the dollar equivalent. Use one documented exchange rate method each year and keep it consistent.
Working remotely for a US employer
A remote worker is the case Ghanaian rules handle least clearly.
- Under 183 days and not a citizen: you are non-resident. Ghana taxes non-residents on Ghana-source income (PwC). A secondary source notes that a non-resident's assessable income includes Ghana-source employment income even without a permanent establishment (TaxLawGH, secondary). Work done while physically in Ghana is the risk area. With no US–Ghana treaty, you cannot use the short-stay employment exemption that treaties usually contain.
- 183 days or more: you are resident and taxed on worldwide income, including the US salary (PwC). If your employer runs no Ghanaian payroll, expect to register with GRA and pay and file yourself.
- Your employer's risk: PwC Ghana has warned that remote staff in Ghana can create a permanent establishment and registration duties for the foreign employer (PwC Ghana). Tell your employer before you move.
Running a business
- Registration and tax ID: individuals use the Ghana Card PIN as TIN. Companies use a GRA-issued TIN (Ghana Revenue Authority).
- Branch profits: a non-resident operating through a Ghanaian branch pays 8% on repatriated profits (PwC).
- Foreign investment rules changed in 2026. A secondary source reports that the GIPA Act, 2026 (Act 1173) took effect on July 15, 2026: the Ghana Investment Promotion Centre became GIPA, the general minimum foreign capital requirement was removed for non-trading businesses, trading companies need US$500,000 in cash equity, and registration is renewed annually (Firmus Advisory, secondary). Confirm these points with GIPA or a Ghanaian lawyer before you invest.
- VAT: for businesses dealing in goods, the registration threshold rose to GHS 750,000 from January 1, 2026 (Ghana Revenue Authority). Crowe Ghana reports that Act 1151 sets no registration threshold for services (Crowe Ghana, secondary).
- US side: a Ghanaian company you control brings Form 5471 and possibly US CFC income inclusions. A sole proprietorship goes on Schedule C, and you owe US self-employment tax (IRS / Greenback, secondary).
Real estate
Ownership limits. Under Article 266 of the 1992 Constitution and section 10 of the Land Act, 2020 (Act 1036), a non-citizen cannot hold a freehold interest in Ghanaian land, and any attempt to create one is void. A non-citizen's lease cannot exceed 50 years at any one time (MyJoyOnline, secondary, law-firm summaries). Citizens can generally hold leases of up to 99 years (MyJoyOnline, secondary). A company counts as a non-citizen if non-citizens hold more than 40% of it (Open Exam Prep, secondary). Commentators note that marriage to a Ghanaian does not remove the restriction for the non-citizen spouse (Ownkey, secondary). Leases are typically renewable.
Ghanaian citizenship (see the residency section above) changes this. A dual US–Ghanaian citizen is not a non-citizen for land purposes.
Renting property out. Rent income tax is 8% (residential) or 15% (commercial) (Ghana Revenue Authority), due within 30 days of receipt (The Ghana Report, secondary). On your US return, the rent goes on Schedule E with depreciation. Ghana's rent tax is on gross rent, so check with your preparer how much of it is creditable (see the double-taxation section above).
Selling. Expect the 30-day realisation return and possible 3% withholding by a corporate buyer (capital gains, above). Your primary residence is excluded from the gains tax according to GRA's notice (Regfollower, secondary). On the US side, ask your preparer whether the US home-sale exclusion applies to your Ghanaian home.
What happens when leaving Ghana?
Ghana side
- Deemed sale of foreign assets when you stop being resident. A Ghanaian tax research publisher summarising sections 101–105 of Act 896 says that when residence ends, a non-domestic asset held immediately before departure is generally treated as realised at market value (TaxLawGH, secondary). In plain terms, US brokerage accounts and other foreign assets may be treated as sold for Ghana tax when you leave. This rule, and its section number, could not be confirmed in a primary copy of the Act, so get advice before you leave if you hold large unrealised gains.
- The reverse on arrival. The same source says the Ghana cost base of a non-domestic asset generally resets to market value when you become resident (TaxLawGH, secondary). Record values on the date you arrive.
- SSNIT emigration benefit. Non-Ghanaian members leaving permanently can claim a lump sum from SSNIT (SSNIT).
- Final return. File your final-year return. Residence for part of a year counts as residence for the whole year (see the residency section above).
US side
- FEIE proration. In the year you move back, the exclusion is prorated by qualifying days (IRS). The physical presence test uses any 12-month window, which can help in a move year (IRS).
- FBAR and Form 8938 continue as long as you keep Ghanaian accounts.
- State tax. If you return to a state with an income tax, residency begins on that state's own rules.
Mistakes Americans commonly make in Ghana
- Assuming a 1973 or 2001 "agreement" is a tax treaty. The 2001 notes cover airline and shipping income only (UN Treaty Series). The 1973 notes are not a totalization agreement (SSA Social Security Bulletin; SSA Social Security Bulletin; SSA POMS RS 02610.015).
- Thinking Ghana taxes only money brought into Ghana. That was the old law. Since 2016, residents are taxed on worldwide income (PwC; Ghanaian Times, secondary).
- Forgetting that Ghanaian citizenship makes you resident. Diaspora Americans who took citizenship are resident on the citizenship test, even if they spend months abroad, unless they have a permanent home abroad and live there all year (PwC).
- Using the FEIE and assuming self-employment tax goes away. It does not (IRS / Greenback, secondary).
- Claiming the FEIE by default on a high Ghanaian salary. When Ghana tax is at or above US tax, the FTC usually does better and builds carryforwards.
- Buying Ghanaian mutual funds or unit trusts without thinking about PFIC rules (IRS).
- Signing a "freehold" deed as a foreigner. It is void (MyJoyOnline, secondary).
- Ignoring the 30-day realisation return when selling property or shares in Ghana (KPMG Ghana).
- Using GRA's old capital gains page. It still shows 15%; the elective rate has been 25% since 2023 (Ghana Revenue Authority; KPMG Ghana).
- Missing the Ghana Card. Without a non-citizen Ghana Card you will struggle to transact with GRA (Ghana Revenue Authority).
- Forgetting to tell a US employer you have moved to Ghana, which can create Ghanaian payroll and registration duties for them (PwC Ghana).
Checklist
Before or on arrival
- Record the market value of foreign assets on the day you arrive (possible Ghana cost-base reset) (TaxLawGH, secondary)
- Apply for a non-citizen Ghana Card (it serves as your Ghana TIN) (Ghana Revenue Authority)
- Count days: 183 in any 12-month window makes you Ghana-resident (PwC)
- Decide whether to apply for the SSNIT expatriate exemption (contracts of 36 months or less, proof of home-country coverage) (KPMG Flash Alert)
- Tell your US employer if you will work remotely from Ghana
Every year
- Ghana annual return by April 30 (PwC); rent tax within 30 days of each receipt (The Ghana Report, secondary)
- US Form 1040 by June 15 (automatic), or October 15 with Form 4868 (IRS)
- Compare FEIE and FTC; file Form 2555 or Form 1116
- Schedule SE if you are self-employed (IRS / Greenback, secondary)
- FBAR if accounts together exceed $10,000 at any time (FinCEN)
- Form 8938 if over the abroad thresholds (Greenback Expat Tax Services, secondary)
- Form 8621 for each Ghanaian fund (IRS); Form 5471 for any Ghanaian company (IRS)
- Keep GRA receipts and certificates to back your Form 1116 claim
When you sell
- Ghana realisation return within 30 days (KPMG Ghana)
- Decide whether to elect the 25% rate on investment-asset gains (PwC)
- Report the gain on your US return in dollars
When you leave
- Get advice on deemed realisation of foreign assets (TaxLawGH, secondary)
- Claim the SSNIT emigration benefit if you are leaving for good (SSNIT)
- File final Ghana return; prorate the FEIE on your US return (IRS)
Frequently asked questions
Is there a tax treaty between the US and Ghana? No. Ghana is not on the IRS treaty list (IRS), and GRA's list of Ghana's tax treaties does not include the US (Ghana Revenue Authority). A 2001 exchange of notes exempts international shipping and airline income only (UN Treaty Series).
Do I have to pay tax in both countries? You may owe tax in both countries, but you should not pay twice on the same income. Ghana taxes you if you are resident or have Ghana-source income (PwC). The US taxes you as a citizen, and gives the FEIE or a credit for Ghana tax (IRS).
How many days can I spend in Ghana before I become a tax resident? Fewer than 183 days in any 12-month period that starts or ends in the year, unless you are a Ghanaian citizen (PwC). The window rolls, so count carefully across year ends.
I'm a dual US–Ghanaian citizen. Does the 183-day rule apply to me? The citizenship test applies first. You are resident unless you keep a permanent home outside Ghana and live in it for the whole year (PwC).
Does Ghana tax my US Social Security, 401(k) or IRA? As a resident, you are taxed on worldwide income (PwC), and no treaty sets special pension rules. How Ghana treats each US retirement payment is a question for a Ghanaian adviser. No GRA guidance specific to US retirement accounts turned up.
Will I pay Social Security in both countries? If you are self-employed, you owe US self-employment tax (IRS / Greenback, secondary). If you work for a Ghanaian employer, you are generally in SSNIT unless you qualify for the expatriate exemption (PwC; KPMG Flash Alert). With no totalization agreement (SSA), double contributions are possible.
What is the 1973 "social security" agreement with Ghana? It is TIAS 7734, a 1973 exchange of notes catalogued under "social security" (Monthly Catalog of US Government Publications, secondary). It is not a totalization agreement: US authority for those only arrived in 1977 (SSA Social Security Bulletin), and SSA does not list Ghana (SSA). Its text was not available to us.
Can I buy a house in Ghana as an American? You can hold a lease of up to 50 years at a time, but not freehold (MyJoyOnline, secondary). Ghanaian citizens can generally hold leases of up to 99 years (MyJoyOnline, secondary).
What is the capital gains tax rate in Ghana? For a resident individual, the gain is added to income (up to 35%), or you can elect 25% on investment-asset gains (PwC). File a return within 30 days of the sale (KPMG Ghana).
Do Ghanaian banks report my account to the IRS? Ghana has no FATCA intergovernmental agreement (US Treasury). Banks that comply register and report directly to the IRS, and dozens had registered by 2015 (Graphic Online, secondary). Plan on your account being reported.
Is mobile money still taxed? The 1% E-Levy was abolished from April 2, 2025 (EY).
Where do I find Ghanaian tax court decisions? See When to hire a professional, below. Ghanaian judgments, including Supreme Court and Court of Appeal tax cases, are published online (GhaLII; EY; judy.legal, secondary).
When should you hire a professional?
Get help from a US expat tax professional, and often a Ghanaian chartered tax adviser too, if any of these apply:
- You are Ghana-resident and your income includes US investments, rent or retirement income.
- You are self-employed, run a Ghanaian company or use the 3% presumptive tax.
- You hold Ghanaian funds, Tier 2 or Tier 3 pension accounts, or mobile money balances you are unsure how to report.
- You are buying, selling or renting out Ghanaian property.
- You are a dual citizen or are planning to apply for Ghanaian citizenship.
- You are leaving Ghana with large unrealised gains.
- You have unfiled US returns or FBARs.
How does Ghana's dispute system and published case law work?
Ghana does publish tax case law. Here is how disputes work.
- The Independent Tax Appeals Board (ITAB). The Revenue Administration (Amendment) Act, 2020 (Act 1029) created an independent board to hear appeals against the Commissioner-General's decisions (KPMG Ghana). You appeal to the board within 30 days, and a further appeal lies to the High Court (KPMG Ghana). The Finance Minister inaugurated the 11-member board on January 20, 2023 (Ministry of Finance (Ghana)), but PwC reported in March 2024 that it had yet to start work (PwC Ghana). It is now deciding cases: a secondary source summarises a board decision of August 7, 2026 in TotalEnergies Marketing Ghana v GRA, and notes that board decisions are administrative, appealable to the High Court and not binding precedent (TaxLawGH, secondary).
- Court decisions are published. The Ghana Legal Information Institute (GhaLII) hosts Act 1029 and links it to a 2022 Supreme Court tax judgment that cites it (GhaLII). Commercial databases such as judy.legal publish tax decisions, for example Perseus Mining Ghana Ltd v Commissioner-General (Supreme Court, March 2025) (judy.legal, secondary). In January 2026 the Court of Appeal ruled on how to claim corporate tax and VAT refunds, and EY summarised the decision (EY).
- Pay-now-argue-later. Ghanaian procedure has long required part payment of disputed tax before an appeal. Ghana's Supreme Court upheld the requirement to pay 30% of disputed tax before challenging an assessment (Graphic Online, secondary, news report). Ask your adviser how this applies under the current rules.
If GRA issues you an assessment, the deadlines are short. Get help the week it arrives.
Sources
All sources were checked on or before November 3, 2026. Type marks each source: Primary (government, statute, official registry or tax authority), Big Four (PwC, KPMG, Deloitte, EY), or Secondary (law firm, practitioner, tax-prep firm, news, or third-party database), which we used only to cross-check or where no primary source was available.
| # | Source | Type | URL | Supports |
|---|---|---|---|---|
| S1 | IRS, Table 3: List of Tax Treaties (updated through Sept. 26, 2025) | Primary | https://www.irs.gov/pub/irs-lbi/table-3-list-of-tax-treaties.pdf | Ghana not a US treaty partner |
| S2 | IRS, Publication 54 ch. 6 (archived), competent authority & treaty countries | Primary | https://webarchive.library.unt.edu/web/20130214031422/http://www.irs.gov/publications/p54/ch06.html | No competent-authority help without a treaty |
| S3 | PwC Worldwide Tax Summaries, US – Foreign tax relief and tax treaties (reviewed Sept. 4, 2026) | Big Four | https://taxsummaries.pwc.com/united-states/individual/foreign-tax-relief-and-tax-treaties | List of 67 US treaty countries; Ghana absent |
| S4 | Ghana Revenue Authority, Status of Ghana's Double Taxation Agreements (June 2023) | Primary | https://gra.gov.gh/wp-content/uploads/2023/06/updated_GHANAS-DTAS-AND-STATUS-06_06_2023-UPDATED.pdf | No US entry |
| S5 | United Nations Treaty Series vol. 2934, No. 51038 (US–Ghana exchange of notes, Apr. 24 & Nov. 12, 2001) | Primary | https://www.un-ilibrary.org/content/books/9789210477062s002-c010 | Shipping/aircraft agreement, 2001 |
| S6 | Texas A&M Libraries catalogue record, TIAS 13171 | Secondary (library catalogue of State Dept. publication) | https://libcat.library.tamu.edu/Record/in00002508762 | 2001 notes = TIAS 13171 |
| S7 | Monthly Catalog of US Government Publications (UNT), TIAS 7734 | Secondary (catalogue of State Dept. publication) | https://mocat.library.unt.edu/catalog/969-16559 | 1973 "Social security" notes, dates, entry into force |
| S8 | SSA, Status of Totalization Agreements | Primary | https://www.ssa.gov/international/status.html | 31 agreements; none in Africa; Romania eff. Sept. 1, 2026 |
| S9 | SSA, Social Security Bulletin vol. 78 no. 4, "Social Security Totalization Agreements" | Primary | https://www.ssa.gov/policy/docs/ssb/v78n4/v78n4p1.html | Section 233 enacted 1977; Italy 1973/1978 |
| S10 | SSA, Social Security Bulletin vol. 51 no. 9, "International Social Security Agreements: The U.S. Experience" | Primary | https://www.ssa.gov/policy/docs/ssb/v51n9/v51n9p4.pdf | Diplomatic-note "social security agreements" not binding |
| S11 | SSA POMS RS 02610.015 (rev. Nov. 18, 2024) | Primary | https://secure.ssa.gov/poms.nsf/lnx/0302610015 | Ghana meets neither social insurance nor treaty exception |
| S12 | US Treasury, Foreign Account Tax Compliance Act – agreements by jurisdiction | Primary | https://home.treasury.gov/about/offices/tax-policy/foreign-account-tax-compliance-act | Ghana absent from IGA list; FFIs may register directly |
| S13 | Graphic Online, "The US Foreign Account Tax Compliance Act; A concern for Ghana?" | Secondary (news) | https://graphiconline.com/business/business-news/the-us-foreign-account-tax-compliance-act-a-concern-for-ghana.html | 55 Ghanaian FIs registered by July 2015 |
| S14 | IRS, Figuring the foreign earned income exclusion | Primary | https://www.irs.gov/individuals/international-taxpayers/figuring-the-foreign-earned-income-exclusion | $130,000 (2025), $132,900 (2026); must file to claim; proration |
| S15 | IRS Newswire on Rev. Proc. 2025-32 (2026 inflation adjustments) | Primary | https://content.govdelivery.com/accounts/USIRS/bulletins/3f65fe1 | FEIE $132,900 for 2026 |
| S16 | IRS, Foreign earned income exclusion – Physical presence test | Primary | https://www.irs.gov/individuals/international-taxpayers/foreign-earned-income-exclusion-physical-presence-test | 330 full days in 12 months |
| S17 | IRS, US citizens and resident aliens abroad – Automatic 2-month extension; IRS Extensions FAQ | Primary | https://www.irs.gov/individuals/international-taxpayers/us-citizens-and-resident-aliens-abroad-automatic-2-month-extension-of-time-to-file ; https://www.irs.gov/faqs/irs-procedures/extensions | June 15 deadline; Form 4868; worldwide filing duty |
| S18 | FinCEN, BSA E-Filing FBAR Help | Primary | https://bsaefiling.fincen.treas.gov/docs/FinCENFBARHelp.pdf | $10,000 threshold; April 15 / Oct. 15 |
| S19 | Greenback Expat Tax Services, Form 8938 thresholds; Chamberlain Hrdlicka, Form 8938 | Secondary | https://www.greenbacktaxservices.com/?p=42279 ; https://www.chamberlainlaw.com/tax-blawg/form-8938-foreign-reporting-trap-for-the-unwary | Abroad thresholds (IRS page not retrieved) |
| S20 | IRS, Instructions for Form 8621 (rev. Dec. 2025) | Primary | https://www.irs.gov/instructions/i8621 | PFIC filing; separate form per PFIC |
| S21 | IRS, Certain taxpayers related to foreign corporations must file Form 5471 | Primary | https://www.irs.gov/node/9882 | Separate form per corporation; penalties, FTC reduction |
| S21b | Greenback Expat Tax Services, Form 5471 for expats | Secondary | https://www.greenbacktaxservices.com/blog/expat-taxes-filing-form-5471/ | 10% ownership / officer categories; $10,000 penalty |
| S22 | IRS, Instructions for Form 3520 | Primary | https://www.irs.gov/pub/irs-prior/i3520--2014.pdf | >$100,000 gifts from nonresident aliens |
| S23 | IRS Topic 855 (archived); Greenback, "Do U.S. Expats Pay Self-Employment Tax?" | Primary / Secondary | https://webarchive.library.unt.edu/eot2008/20080919222613/http://www.irs.gov/taxtopics/tc855.html ; https://www.greenbacktaxservices.com/knowledge-center/do-us-expats-pay-self-employment-tax/ | SE tax not reduced by FEIE; no relief without totalization |
| S24 | KPMG TaxNewsFlash, Notice 2025-55 (remittance transfer tax); Bloomberg Tax on proposed regulations (Apr. 2026) | Big Four / Secondary | https://kpmg.com/us/en/taxnewsflash/news/2025/10/tnf-notice-2025-55-penalty-relief-for-remittance-transfer-providers-who-fail-to-deposit-new-excise-tax-on-certain-remittance-transfers.html ; https://news.bloomberglaw.com/daily-tax-report/irs-issues-proposed-regulations-on-1-percent-excise-tax-on-certain-remittance-transfers | 1% tax on cash-funded remittances from Jan. 1, 2026 |
| S24b | KPMG Flash Alert 2023-239 (Notice 2023-80); RSM on Notice 2023-80 | Big Four / Secondary | https://assets.kpmg.com/content/dam/kpmg/xx/pdf/2023/12/fa23-239.pdf ; https://rsmus.com/insights/tax-alerts/2023/irs-releases-guidance-on-the-foreign-tax-credit-and-globe-.html | FTC regulation relief extended until further notice |
| S24c | Greenback Expat Tax Services, IRS proposed regulations on the 1% remittance tax | Secondary | https://www.greenbacktaxservices.com/blog/irs-remittance-transfer-tax-proposed-regulations/ | Tax depends on funding method; not expat-specific |
| S25 | Taxes for Expats, Streamlined Foreign Offshore Procedures; Greenback, Streamlined Filing | Secondary | https://www.taxesforexpats.com/articles/fbar/streamlined-foreign-offshore-procedures.html ; https://www.greenbacktaxservices.com/blog/late-us-tax-caught-up/ | 3 returns + 6 FBARs; non-willful certification |
| S26 | PwC WWTS, Ghana – Individual – Residence (reviewed Mar. 11, 2026) | Big Four | https://taxsummaries.pwc.com/Ghana/Individual/Residence | Four residence tests; whole-year rule |
| S27 | PwC WWTS, Ghana – Individual – Taxes on personal income (Act 1178 table) | Big Four | https://taxsummaries.pwc.com/Ghana/Individual/Taxes-on-personal-income | Worldwide taxation; foreign employment exemption; rates; 25% non-resident |
| S28 | PwC WWTS, Ghana – Individual – Income determination (reviewed Mar. 11, 2026) | Big Four | https://taxsummaries.pwc.com/Ghana/Individual/Income-determination | 8% final dividend WHT; interest exemptions |
| S29 | PwC WWTS, Ghana – Individual – Other taxes (reviewed Mar. 11, 2026) | Big Four | https://taxsummaries.pwc.com/Ghana/Individual/Other-taxes | SSNIT tiers & rates; expat contribution; CGT 25% election; gifts |
| S29b | EY Worldwide Personal Tax and Immigration Guide 2021–22, Ghana (via Issuu) | Big Four (older edition) | https://issuu.com/worldtradepresss/docs/ghana-personal-tax-guide | Modified-basis taxation for Ghana-only business income |
| S30 | PwC WWTS, Ghana – Corporate – Group taxation (reviewed Oct. 27, 2026) | Big Four | https://taxsummaries.pwc.com/Ghana/Corporate/Group-taxation | No express CFC provisions; thin cap |
| S30b | PwC WWTS, Ghana – Corporate – Branch income (reviewed Mar. 11, 2026) | Big Four | https://taxsummaries.pwc.com/ghana/corporate/branch-income | 8% branch profits tax |
| S31 | PwC WWTS, Ghana – Quick rates and dates | Big Four | https://taxsummaries.pwc.com/Ghana | Return due within four months; 25% CIT |
| S32 | GRA, Amendments – Income Tax Act, 2026 (Act 1178) | Primary | https://gra.gov.gh/news/portfolio/amendments-income-tax-act-2026-act-1178/ | Sept. 1, 2026 bands; presumptive tax 3% on GHS 20,000–750,000 |
| S33 | 3News, "Review of the Income Tax (Amendment) Act, 2026 (Act 1178)" | Secondary (news/commentary) | https://3news.com/opinion/review-of-the-income-tax-amendment-act-2026-act-1178-its-impact-on-taxpayers | Assent Aug. 26, 2026; schedules amended; old vs new bands |
| S34 | Firmus Advisory, "Business Taxes in Ghana (2026)" | Secondary | https://firmusadvisory.com/taxes-in-ghana-all-you-need-to-know/ | Jan–Aug 2026 PAYE on old bands; MTS ceiling previously GHS 500,000; GIPA Act 2026 |
| S35 | KPMG Ghana, Tax Flash Alert – New Tax Amendments (Apr. 27, 2023) | Big Four | https://assets.kpmg.com/content/dam/kpmg/gh/pdf/KPMG%20Tax%20Flash%20Alert%20_%20New%20Tax%20Amendments%20-%2027.04.2023-Final.pdf | Act 1094: 25% election; 30-day return; 3%/10% WHT |
| S36 | Regfollower, "Ghana: GRA issues reminder on tax applicable to asset and liability gains" (relays GRA notice) | Secondary relay of primary notice | https://regfollower.com/ghana-gra-issues-reminder-on-tax-applicable-to-asset-and-liability-gains/ | s.39A 30-day return; primary residence excluded; non-resident 25% on gross |
| S37 | GRA, Capital Gains Tax page | Primary (outdated) | https://gra.gov.gh/domestic-tax/tax-types/capital-gains-tax/ | Still shows 15% (pre-2023) |
| S38 | TaxLawGH (MSL Business School), "Ghana Tax Residence, Source and Foreign Tax Credit" | Secondary | https://www.taxlawgh.com/ghana-tax-residence-source-foreign-tax-credit | 183-day start rule; deemed realisation on exit; cost reset on entry; s.112 FTC |
| S38b | TaxLawGH, "Ghana permanent establishment and non-resident tax" | Secondary | https://www.taxlawgh.com/ghana-permanent-establishment-non-resident-tax | Non-resident Ghana-source employment income |
| S38d | Ghanaian Times, "Taxation of resident persons in Ghana" | Secondary (news/commentary) | https://ghanaiantimes.com.gh/taxation-of-resident-persons-in-ghana/ | Act 592 taxed foreign income only when brought into Ghana; Act 896 worldwide |
| S39 | GRA press release, "Clarifies status of resident individuals for tax purposes" (Apr. 22, 2024) | Primary (hosted by Starr FM) | https://starrfm.com.gh/wp-content/uploads/2024/04/Press-Release-22.04.2024.pdf | Residents taxed on foreign income |
| S40 | EY Global Tax News, "Ghana's Parliament enacts several indirect tax-related laws, effective 1 January 2026" | Big Four | https://taxnews.ey.com/news/2026-0163-ghanas-parliament-enacts-several-indirect-tax-related-laws-effective-1-january-2026 | VAT Act 2025 (Act 1151); COVID levy abolished |
| S40b | Crowe Ghana, "Ghana VAT reform 2026" | Secondary (accounting network) | https://www.crowe.com/gh/news/ghana-vat-reform-2026 | No VAT registration threshold for services |
| S41 | GRA notice on VAT Act 1151 | Primary | https://gra.gov.gh/news/portfolio/notice-to-all-vat-registered-taxpayers/ | Goods threshold GHS 750,000; flat rate scheme abolished; Jan. 1, 2026 |
| S42 | EY Global Tax News, "Ghana's Parliament amends tax laws following the 2025 budget" | Big Four | https://taxnews.ey.com/news/2025-0844-ghanas-parliament-amends-tax-laws-following-the-2025-budget-statement-presentation | E-Levy Repeal Act (Act 1128); Act 1129; Apr. 2, 2025 |
| S43 | Graphic Online, "GRA assures refund of E-Levy deductions after abolition" | Secondary (news) | https://www.graphic.com.gh/news/general-news/ghana-news-gra-assures-refund-of-e-levy-deductions-after-abolition.html | Lottery WHT abolished |
| S44 | Growth and Sustainability Levy (Amendment) Act, 2025 (Act 1131), via judy.legal | Primary text (third-party host) | https://www.judy.legal/legislation/akn/gh/act/2025/1131 | GSL extended to 2028 |
| S44b | KPMG Ghana, 2025 Tax Datacard | Big Four | https://kpmg.com/gh/en/insights/tax/KPMG-2025-tax-data-card.html | Growth and Sustainability Levy categories and extension to 2028 |
| S45 | SSNIT, Public Notice: Maximum and Minimum Insurable Earnings for 2026 | Primary | https://www.ssnit.org.gh/wp-content/uploads/2026/01/Public-Notice-Min-Max-Insurable.pdf | GHS 69,000 cap; GHS 9,315 max contribution |
| S46 | SSNIT, About SSNIT / Act 883 implications | Primary | https://www.ssnit.org.gh/?p=72 ; https://www.ssnit.org.gh/?p=3694 (both pages unavailable at time of writing) | 18.5% split; emigration lump sum |
| S47 | KPMG Flash Alert 2018-016, Ghana expatriate pension exemption | Big Four | https://assets.kpmg.com/content/dam/kpmg/xx/pdf/2018/01/fa18-016.pdf | ≤36-month contracts + proof of home scheme |
| S48 | NPRA, Guidelines for the Registration of Expatriate (Foreign) Workers | Primary | https://www.npra.gov.gh/assets/documents/GUIDELINE_ON_EXPARTRIATE_REGISTRATION_UPDATED_20.03.17.pdf | Applies where no reciprocal agreement |
| S49 | MyJoyOnline, "Freehold, leasehold and the 50-year rule"; Bentsi-Enchill, Letsa & Ankomah via LexAfrica, "Key highlights of Ghana's Land Act 2020" | Secondary (news / law firm) | https://www.myjoyonline.com/freehold-leasehold-and-the-50-year-rule-what-foreign-and-diaspora-buyers-can-actually-own-in-ghana/ ; https://lexafrica.com/2022/04/key-highlights-of-ghanas-land-act-2020/ | Art. 266; Land Act s.10; 50-year cap; 99 years for citizens |
| S49b | Open Exam Prep, Land Act 2020 practice notes | Secondary | https://open-exam-prep.com/practice/gh-plc-conveyancing-drafting | 40% non-citizen company rule |
| S49c | Ownkey, "Why using a nominee or company … doesn't work" | Secondary | https://ownkey.com/gh/blog/nominee-company-bypass-foreign-ownership-restrictions-ghana | Marriage does not lift restriction |
| S50 | GRA, Rent Tax pages | Primary | https://gra.gov.gh/domestic-tax/tax-types/rent-tax/ | 8% / 15%; due within 30 days |
| S50b | The Ghana Report, "Govt to tax rent paid to landlords" (quoting GRA website) | Secondary (news) | https://www.theghanareport.com/?p=124040 | Rent tax due within 30 days |
| S51 | GRA, TIN FAQ | Primary | https://gra.gov.gh/tin/tin-faq/ | Ghana Card PIN = TIN; expatriates need non-citizen card |
| S51b | GRA information on TINs, published by the OECD for CRS purposes | Primary (GRA document, OECD-hosted) | https://www.oecd.org/tax/automatic-exchange/crs-implementation-and-assistance/tax-identification-numbers/Ghana-TIN.pdf | GRA TIN for individuals not eligible for Ghana Card |
| S52 | KPMG Ghana, Tax Alert on Revenue Administration (Amendment) Act 2020 (Act 1029) | Big Four | https://assets.kpmg.com/content/dam/kpmg/gh/pdf/Gh-Tax-Alert-Rev-admin-act-amendment-new.pdf | ITAB created; 30-day appeal; High Court |
| S52b | Ministry of Finance, "The Independent Tax Appeals Board Inaugurated" (Jan. 20, 2023) | Primary | https://mofep.gov.gh/node/1539 | ITAB inaugurated Jan. 20, 2023 |
| S52c | PwC Ghana, Tax Regulatory Journal (March 2024) | Big Four | https://pwc.com/gh/en/assets/pdf/tax-regulatory-journal-march-2024.pdf | ITAB had yet to commence work (March 2024) |
| S53 | GhaLII, Revenue Administration (Amendment) Act, 2020 (Act 1029) | Primary (legal information institute) | https://ghalii.org/akn/gh/act/2020/1029/eng@2020-10-06 | Judgments published and cross-linked |
| S54 | EY Global Tax News, "Ghana Court of Appeal decides on procedures for claiming VAT and corporate tax refunds" (Mar. 17, 2026) | Big Four | https://taxnews.ey.com/news/2026-0662 | Jan. 29, 2026 judgment |
| S55 | judy.legal, Perseus Mining Ghana Ltd v Commissioner-General (SC, Mar. 11, 2025) | Secondary (case database) | https://www.judy.legal/case/perseus-mining-ghana-limited-v-commissioner-general-ghana-revenue-authority | Published tax case law |
| S55b | Graphic Online, "Supreme Court upholds tax law: pay now, argue later" | Secondary (news) | https://www.graphic.com.gh/news/general-news/supreme-court-upholds-tax-law-pay-now-argue-later.html | 30% payment before challenge |
| S56 | TaxLawGH, TotalEnergies Marketing Ghana v GRA (ITAB decision summary) | Secondary | https://www.taxlawgh.com/ghana-tax-case-totalenergies-marketing-ghana-v-ghana-revenue-authority | ITAB decisions summarised; not binding precedent |
| S57 | theGrio / Associated Press, "'Come home,' Ghana told the African diaspora" (Jan. 4, 2025) | Secondary (news) | https://thegrio.com/2025/01/04/come-home-ghana-told-the-african-diaspora-now-some-black-americans-take-its-citizenship/ | 524 diaspora members granted citizenship, Nov. 2024 |
| S58 | 20 CFR 404.460 (SSA) | Primary | https://www.ssa.gov/OP_Home/cfr20/404/404-0460.htm | Treasury-restricted countries: Cuba, North Korea |
| S59 | PwC Ghana, 2026 Tax Facts and Figures (July 2026) | Big Four (further reading) | https://www.pwc.com/gh/en/publications/tax-facts-and-figures.html | General reference |
| S60 | IRS, Foreign Tax Credit – How to figure the credit | Primary | https://www.irs.gov/individuals/international-taxpayers/foreign-tax-credit-how-to-figure-the-credit | FTC limit formula |
| S59b | PwC Ghana, Tax alert: the hidden tax cost of a remote employee | Big Four | https://www.pwc.com/gh/en/assets/pdf/tax-alert-hidden-tax-cost-remote-employee.pdf | Remote workers can create PE/registration duties |
Research limits. The full text of TIAS 7734 (1973) could not be opened, so its exact subject beyond its catalogue title is unconfirmed. Several IRS web pages could not be fetched directly during research. Where that happened we relied on IRS PDFs, IRS pages surfaced through search, or labelled secondary sources (Form 8938 thresholds, streamlined procedures). The exit-realisation rule in the Leaving Ghana section is supported by a single secondary Ghanaian source; we did not verify it in a primary copy of Act 896.
This guide is general information, not tax or legal advice. Tax law in both countries changes often; Ghana changed its personal rates mid-year in 2026.