Key takeaways
- Moving to a zero-tax country removes only the local layer, never the US one. Federal long-term capital gains rates (0/15/20%), the 3.8% net investment income tax, and state tax if domicile wasn't broken all remain due exactly as if the sale happened in the US.
- Whether a gain is "foreign-source" for the foreign tax credit hinges on a specific 10% test. Your tax home has to be abroad AND a foreign tax of at least 10% of the gain has to actually be paid — below that, the gain stays US-source and the local tax generally isn't creditable, so a low flat local rate can cost more overall than a higher, creditable one.
- The 3.8% net investment income tax cannot be offset by any foreign tax credit. The Federal Circuit confirmed this on August 31, 2026 for both the US-Canada and US-France treaties — it can remain due even when credits wipe out the regular federal tax.
- Every crypto disposal is a taxable event, including swapping one token for another. There is no like-kind exchange relief for digital assets, and staking or mining rewards are taxed as income the moment you gain control over them, not when later sold.
- The foreign earned income exclusion does nothing for capital gains or crypto. IRS Publication 54 is explicit that interest, dividends and capital gains are not earned income — excluding a salary does nothing to a stock or crypto sale reported on the same return.
- Puerto Rico is the one place a US citizen can legally cut federal tax on gains without giving up citizenship — but only on gains that accrue after becoming a bona fide resident; appreciation built up in the 10 years before the move stays federally taxable regardless.
A long list of countries do not tax an individual's gains on shares or cryptocurrency, and several of them market that fact to investors. For most people, moving to one of them before selling is a legitimate way to cut the bill, because a gain on securities is generally taxed by the country where the seller lives. For an American, the same move cuts only half the bill, and often the smaller half.
The United States taxes its citizens and green card holders on their worldwide income no matter where they live. A U.S. citizen who sells Apple shares or bitcoin from an apartment in Dubai owes the same federal tax as if the sale had happened in Denver. What changes is the local layer: in a country with no capital gains tax, there is nothing local to pay, and nothing local to credit either.
This article covers both sides. First, what the federal government taxes regardless of your address, including the rules specific to crypto. Second, what happens when your new country taxes the gain too, and why the source of the gain decides whether a foreign tax credit works. Third, the traps that only Americans abroad run into. Fourth, the places where the local tax on gains is zero or low, seen from the point of view of a U.S. taxpayer. The last sections deal with the two exits that do change the federal picture: Puerto Rico and renunciation.
What the United States taxes wherever you live
What are the 2026 rates?
A gain on an asset held more than one year is long-term and taxed at 0, 15 or 20 percent under 26 U.S.C. § 1(h). For 2026, Rev. Proc. 2025-32 sets the top of the 0 percent bracket at $49,450 of taxable income for single filers and $98,900 for married couples filing jointly, and the top of the 15 percent bracket at $545,500 (single) and $613,700 (joint). Above those amounts, the rate is 20 percent.
A gain on an asset held one year or less is short-term and taxed as ordinary income, at rates from 10 to 37 percent. In 2026 the 37 percent bracket starts at $640,600 of taxable income for single filers and $768,700 for joint filers.
None of these figures depend on residence. An American in Singapore with $300,000 of long-term gains and no other income lands in the 15 percent bracket for most of it, exactly as a resident of Ohio would.
What is the 3.8% net investment income tax?
Section 1411 adds a 3.8 percent tax on net investment income, which includes capital gains, dividends and interest, for taxpayers whose modified adjusted gross income exceeds $200,000 (single), $250,000 (joint) or $125,000 (married filing separately). These thresholds are fixed in the statute and are not indexed for inflation.
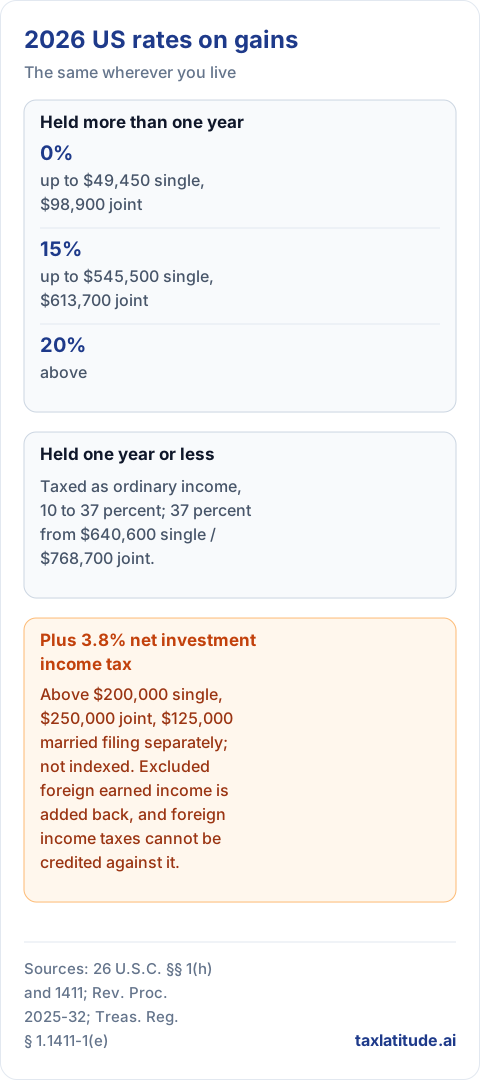
Two details matter for Americans abroad. The modified adjusted gross income used for this tax adds back any amount excluded under the foreign earned income exclusion (§ 1411(d)), so excluding your salary does not keep you under the threshold. And foreign income taxes cannot be credited against it. Treasury Regulation § 1.1411-1(e) says so directly, the Tax Court agreed in Toulouse v. Commissioner (157 T.C. No. 4, 2021), and on August 31, 2026 the Federal Circuit reversed two taxpayer wins in the Court of Federal Claims, holding that neither the U.S.-Canada treaty (Estate of Bruyea v. United States) nor the U.S.-France treaty (Christensen v. United States) allows a credit against this tax. For a high-income American, the 3.8 percent can therefore remain due even when foreign tax credits wipe out the regular federal tax on the gain.
Why doesn't the foreign earned income exclusion help?
The exclusion covers earned income only, meaning pay for personal services. IRS Publication 54 is explicit that interest, dividends and capital gains are not earned income. A digital nomad who excludes $130,000 of salary still owes full federal tax on a crypto sale. Our guide to the FEIE and the foreign tax credit explains how the two interact.
Why is crypto treated as property, not currency?
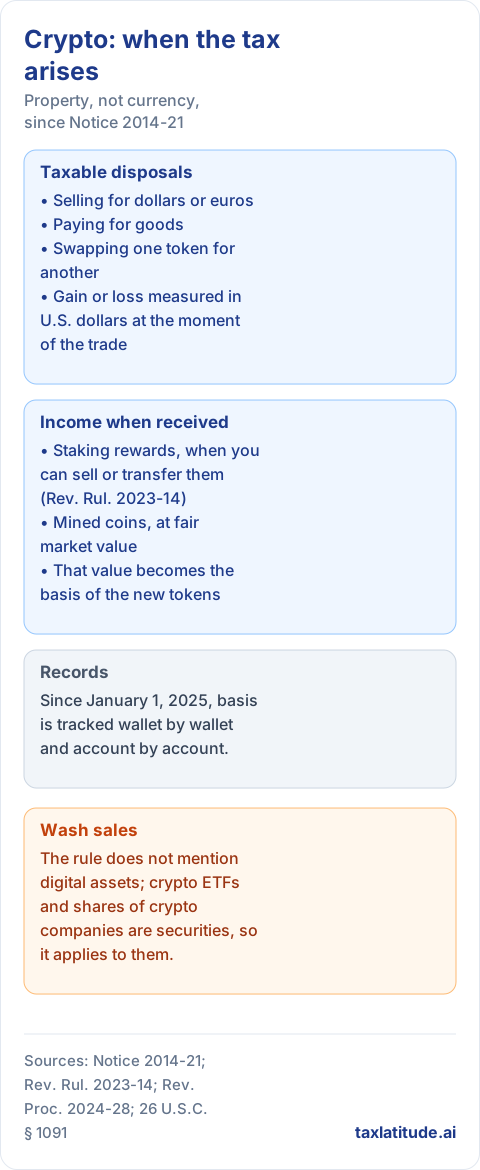
Since Notice 2014-21, the IRS has treated virtual currency as property for federal tax purposes. Every disposal is a realization event: selling for dollars or euros, paying for goods, and exchanging one token for another. Swapping ETH for SOL, or bitcoin for a stablecoin, produces a gain or loss measured in U.S. dollars at the moment of the trade. The like-kind exchange rule that some traders relied on before 2018 is now limited to real property (§ 1031(a)(1)), so it offers no shelter for token swaps.
Income from holding crypto is taxed when received, not when sold. Rev. Rul. 2023-14 holds that a cash-method taxpayer who receives staking rewards includes their fair market value in gross income in the year the taxpayer gains dominion and control over them, meaning the ability to sell or transfer them. Notice 2014-21 already treated mined coins as income at fair market value on receipt. That value becomes the basis of the new tokens, and a later sale produces a separate capital gain or loss.
The holding period rules are the same as for stock. A token held more than one year qualifies for long-term rates; a token traded within the year is taxed at ordinary rates.
What does Form 1099-DA mean for digital assets?
Forms 1040, 1040-SR and 1040-NR carry a yes-or-no question about digital assets near the top of the first page. According to the IRS, you generally answer "yes" if during the year you received digital assets as payment or as a reward, or sold, exchanged or otherwise disposed of them. Someone who only held crypto and did nothing with it can answer "no." The question has to be answered either way, and a false "no" on a signed return is a problem of its own.
U.S. brokers began reporting digital asset sales on Form 1099-DA for transactions on or after January 1, 2025, with gross proceeds only. For transactions on or after January 1, 2026, basis reporting is also mandatory for digital assets that are covered securities, which generally means assets acquired on or after that date and held with the same broker. The first forms showing basis will cover 2026 activity and arrive in early 2027.
A platform outside the United States will generally not send you a 1099-DA. That changes nothing: the IRS states that taxable transactions on foreign platforms must still be reported on your return. The absence of a form only means the burden of proof sits entirely with you.
What is lot accounting?
Since January 1, 2025, basis has to be tracked wallet by wallet and account by account, rather than across all holdings at once. Rev. Proc. 2024-28 gave a one-time safe harbor to allocate unused basis among wallets as of that date. For an American who has used several exchanges in several countries, reconstructing that history is often the longest part of the tax return, and it is impossible without complete transaction records. Export them before an exchange closes your account or stops serving your country.
What are wash sales?
Section 1091 disallows a loss on the sale of "stock or securities" when substantially identical securities are bought within 30 days before or after. The statute does not mention digital assets, and as of this writing Congress has not extended it to them. A loss on bitcoin sold and repurchased the same day is therefore still recognized under current law. Crypto ETFs and shares of crypto companies are securities, so the rule applies to them in full.
When your new country taxes the gain too
Why does the foreign tax credit only offset tax on foreign-source income?
If you move to a country that does tax capital gains, the foreign tax credit is the tool that prevents double taxation. Its limit is the problem. Under § 904 and as IRS Publication 514 explains, the credit can only reduce the U.S. tax on foreign-source income. Whether a capital gain is foreign-source is therefore the first question to ask, not a technicality. The limitation is computed separately by category of income too, so a large credit from a high-tax salary can sit unused while you still owe US tax on a gain in a different category — TaxLatitude's deep dive into the foreign tax credit basket trap walks through a fully worked example.
Where a gain on shares or crypto is sourced
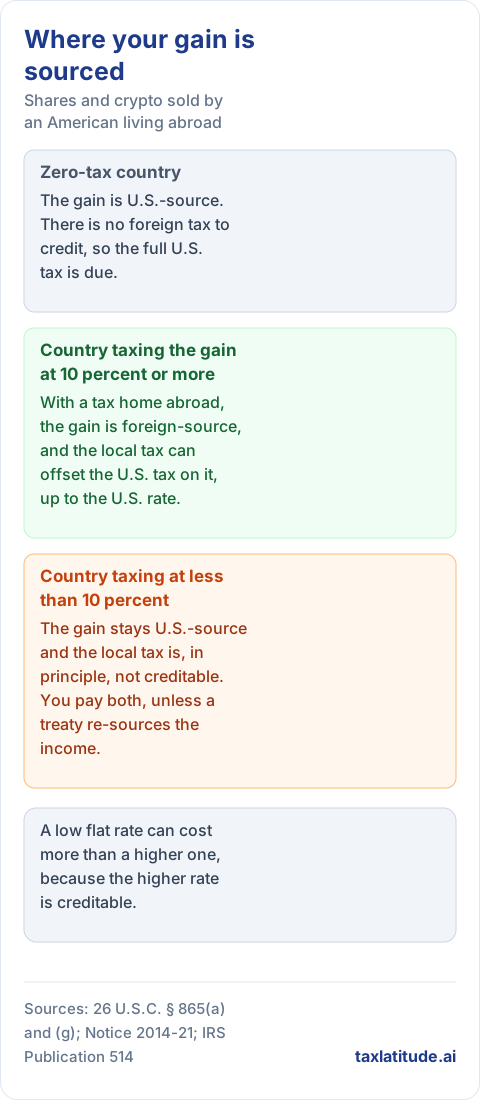
Section 865(a) sources gain on the sale of personal property, which includes shares and, under Notice 2014-21, crypto, by the residence of the seller. The trap is in the definition. Under § 865(g)(1), a U.S. citizen or green card holder is a "United States resident" for this purpose unless they have a tax home in a foreign country. And § 865(g)(2) adds a second condition: a citizen or resident alien is not treated as a nonresident for a given sale unless a foreign income tax of at least 10 percent of the gain is actually paid on it.
The result for an American living abroad:
- Zero-tax country. The gain is U.S.-source. There is no foreign tax to credit anyway, so the full U.S. tax is due.
- Country taxing the gain at 10 percent or more. If your tax home is abroad, the gain is foreign-source, and the local tax can offset the U.S. tax on it, up to the U.S. rate.
- Country taxing at less than 10 percent. The gain stays U.S.-source and the local tax is, in principle, not creditable. You pay both, unless a treaty re-sources the income.
That third case is the least known. A low flat rate on crypto gains in a new country can end up costing more than a higher rate would, because the higher rate is creditable and the lower one is not.
Is your destination's tax rate on gains actually above or below 10%? That one number decides whether your gain stays US-source with no credit available, or becomes foreign-source and creditable — easy to get backwards. Ask TaxLatitude to check your destination's rate against the 10% test →
Treaties: the saving clause and re-sourcing
Nearly every U.S. income tax treaty contains a saving clause, which lets the United States tax its citizens as if the treaty did not exist (Article 1(4) of the 2016 U.S. Model). A treaty therefore does not exempt an American from U.S. tax on capital gains. What some treaties do is re-source income so the credit can work. In the relief article of the U.S. Model (Article 23(4)), for a U.S. citizen resident in the other country, items of income that the treaty exempts or taxes at a reduced U.S. rate when earned by a non-citizen resident are deemed to arise in that country to the extent necessary to avoid double taxation. Income re-sourced by treaty goes into its own foreign tax credit limitation category under § 904(d)(6), so it cannot absorb credits from other income.
The exact wording differs in each treaty and with each country. Our article on how to read a U.S. tax treaty walks through the relevant articles, and dual tax residency covers the tie-breaker rules that decide which country considers you resident.
Traps specific to Americans abroad
Foreign funds
Almost every fund or ETF domiciled outside the United States is a passive foreign investment company for U.S. purposes. Unless an election was made in time, gains are taxed at the top ordinary rate with an interest charge, and each fund generally requires an annual Form 8621. Our PFIC guide covers the regime in detail, and TaxLatitude's deep dive into the PFIC trap walks through a fully worked example of what the default tax regime actually costs. In the European Union the trap closes from the other side: the PRIIPs Regulation (EU No 1286/2014) requires a key information document that most U.S.-domiciled ETFs do not produce, which in practice keeps them out of reach of retail clients of EU brokers. An American in Lisbon or Munich ends up choosing between individual stocks, a U.S. brokerage account if one can be kept open, or PFIC treatment.
Foreign accounts and platforms
An American with more than $10,000 in aggregate in foreign financial accounts at any time in the year files an FBAR. On crypto, FinCEN's position since Notice 2020-2 is that a foreign account holding only virtual currency is not currently reportable on the FBAR, unless it also holds other reportable assets such as fiat cash. The same notice says FinCEN intends to propose amending the rules to add virtual currency. An exchange account that holds euros or dollars alongside crypto is reportable now. Our FBAR guide covers the filing itself.
Form 8938 is a separate obligation with higher thresholds for those living abroad: more than $200,000 at year-end or $300,000 at any time for a single filer, and $400,000 or $600,000 for a joint return. Its scope is defined differently from the FBAR's, and the cautious approach is to include foreign-held digital assets in the calculation unless current instructions clearly exclude them. See our pages on FATCA and CRS for how foreign institutions report Americans to the IRS.
Brokers
Moving abroad can cost you your U.S. brokerage account, because some firms do not serve clients with an address in certain countries. Ask your broker in writing, before you move, whether it accepts residents of your destination, and plan what happens to the positions if it does not. A forced transfer is usually possible in kind; a forced sale is a taxable event chosen by someone else.
Currency
U.S. tax is computed in dollars. When you sell a stock bought in euros, the gain is the difference between the dollar value of the proceeds and the dollar value of the cost, so exchange rate moves can create a taxable gain on an investment that lost money in local currency. Loans add a second layer. Under Quijano v. United States, 93 F.3d 26 (1st Cir. 1996), a gain from repaying a mortgage in a foreign currency that has fallen against the dollar is taxable, while a loss on a personal loan is not deductible.
Your home
A main home abroad can qualify for the § 121 exclusion of up to $250,000 of gain ($500,000 for a qualifying couple), because the statute does not limit it to U.S. property. The currency rules above still apply to the gain and to the mortgage.
Dividends
As a U.S. person, you do not suffer U.S. withholding on dividends from American companies if your broker has a valid Form W-9. Dividends from foreign companies may be withheld at source by the issuer's country. That tax can be credited against U.S. tax on the dividend, within the § 904 limit, but if you live in a zero-tax country, the U.S. tax on foreign dividends is your only tax and the foreign withholding may exceed what can be credited.
Exit tax and estate planning
Two subjects connect to every relocation plan: the exit tax, covered below, and how a move changes your estate plan, covered in estate planning abroad. If you hold a foreign company rather than a portfolio, read owning a company abroad before selling it.
Where is the local tax on gains zero or low?
For each country below, the point is the local rule. In every case, the U.S. tax described above remains due.
Middle East
United Arab Emirates. The UAE levies no federal personal income tax. Its corporate tax applies to individuals only for business activities, and Cabinet Decision No. 49 of 2023 states that wage income, personal investment income and real estate investment income of a natural person are not business income, whatever the amount. A personal portfolio of shares or crypto held on your own account, without a license, is therefore outside UAE tax. There is no U.S.-UAE income tax treaty, which matters little for a citizen because of the saving clause. See our UAE guide.
Asia
Singapore. The Inland Revenue Authority of Singapore states that gains from the sale of property, shares and financial instruments are generally not taxable, while gains from trading can be. The line between investing and trading turns on factors such as frequency, holding period and intent. There is no U.S.-Singapore income tax treaty. See our Singapore guide.
Hong Kong. Section 14 of the Inland Revenue Ordinance (Cap. 112) charges profits tax on profits from a trade or business in Hong Kong and expressly excludes profits arising from the sale of capital assets. A passive investor's gains are not taxed; a person found to be trading shares or tokens as a business can be. There is no comprehensive U.S.-Hong Kong income tax treaty. See our Hong Kong guide.
Malaysia. Malaysia introduced a capital gains tax in 2024, but the Inland Revenue Board's guidelines apply it to companies, limited liability partnerships, trust bodies and cooperatives disposing of unlisted shares and certain foreign assets. Individuals are not within its scope. Real property and shares in real property companies remain under the separate real property gains tax. There is no U.S.-Malaysia income tax treaty. See our Malaysia guide.
Thailand. According to press reports of its publication in the Royal Gazette on September 5, 2025 (secondary source), Ministerial Regulation No. 399 exempts individuals from Thai personal income tax on gains from transferring cryptocurrency or digital tokens through an exchange, broker or dealer licensed in Thailand, for transfers from January 1, 2025 through December 31, 2029. Trades on foreign or unlicensed platforms are outside the exemption. Thailand also has its own rules on foreign income brought into the country, and the United States and Thailand have an income tax treaty. See our Thailand guide before relying on either.
Europe
Switzerland. Article 16(3) of the federal direct tax law exempts capital gains on private assets, and cantonal practice applies the same rule to crypto held privately. The exemption is lost if the tax authority treats you as a professional securities dealer. The Federal Tax Administration's Circular No. 36 lists criteria that, if all are met, rule out that classification, including a holding period of at least six months, annual trading volume no more than five times the portfolio at the start of the year, gains below half of net taxable income, no significant borrowing, and derivatives used only for hedging. Cantons tax net wealth annually, and crypto is valued for that purpose at the rate the Federal Tax Administration publishes for year-end. The U.S.-Switzerland treaty exists, but with no Swiss tax on the gain, there is nothing to credit. See our Switzerland guide.
Germany. Germany taxes gains on shares under its flat tax on investment income (25 percent plus the solidarity surcharge, § 32d of the Income Tax Act). Crypto is treated differently: under § 23 of the same Act and the Federal Finance Ministry letter of March 6, 2025, a gain on crypto held privately is taxable only if acquisition and sale fall within one year. After that, it is exempt. For an American, a German share gain taxed at roughly 26 percent is foreign-source under § 865(g) and creditable; a crypto gain exempt in Germany is U.S.-source and fully taxed by the IRS. See our Germany guide.
Portugal. Article 10 of the Personal Income Tax Code excludes from tax gains on crypto-assets held for 365 days or more; shorter holdings are taxed at a special rate of 28 percent unless the taxpayer opts to aggregate them with other income. The tax authority confirmed the exclusion in a binding ruling of December 4, 2025 (process 29052). The U.S.-Portugal treaty applies to residents. See our Portugal guide.
Other European regimes for new residents, such as Italy's flat tax on foreign income, raise issues of their own for Americans. Our Italy guide and the worked example on the U.S. exit tax for someone living in Italy cover them.
The Americas and the Pacific
Panama. Article 694 of the Fiscal Code taxes income produced within the territory of Panama, wherever it is received. Income from foreign sources is outside the tax. How Panama sources a gain on foreign shares or on crypto sold online is a question to settle with a Panamanian adviser, not to assume. There is no U.S.-Panama income tax treaty. See our Panama guide.
New Zealand. New Zealand has no general capital gains tax, but Inland Revenue taxes the disposal of crypto-assets acquired for the purpose of selling or exchanging them, and states that this purpose exists if you plan to sell at some point, however long you intend to hold. In practice, most crypto gains are taxable there. See our New Zealand guide.
Puerto Rico. Puerto Rico is the one place where a U.S. citizen can legally reduce federal tax on gains without giving up citizenship, because § 933 excludes Puerto Rico-source income of a bona fide resident from federal gross income. Bona fide residence under § 937 requires presence, a tax home and closer connection on the island. The limit is built-in gain. Under Treas. Reg. § 1.937-2(f)(1), gain on property owned before becoming a bona fide resident is not Puerto Rico-source if, during any of the 10 years before the year of sale, you were a U.S. citizen or resident who was not a bona fide resident of Puerto Rico. An election under § 1.937-2(f)(1)(vi) treats the portion of the gain that accrued during residence as Puerto Rico-source, but the pre-move gain stays federally taxable. On the local side, Act 38-2026, signed in March 2026, keeps the 0 percent Puerto Rico rate on post-move gains for resident investors who file their decree application by December 31, 2026, and applies a 4 percent rate to those who apply from January 1, 2027, with the program extended to 2055 (secondary source). The IRS has run a compliance campaign aimed at individuals claiming these benefits since 2021, focused on whether they meet the § 937 residence and sourcing rules.
Already sitting on significant unrealized gains before moving to Puerto Rico? The 10-year look-back keeps appreciation built up before you became a bona fide resident fully taxable federally, exclusion or not. Ask TaxLatitude to separate your pre-move and post-move gain →
Georgia, Costa Rica and several other countries are also popular with investors. We have not repeated their local rules here because we could not confirm them on an official source at the time of writing; our Georgia and Costa Rica guides cover what we have verified.
Leaving your state
Before any foreign country, there is a state. A state that considers you domiciled there can keep taxing your worldwide gains after you move abroad, and California and New York are known for examining departures closely. Washington has no tax on wages but imposes a separate excise tax on long-term capital gains under chapter 82.87 RCW. Breaking domicile means leaving with your home, your driver's license, your voter registration and your intent, and documenting it. Our guide to state taxes after moving abroad explains how each major state approaches it.
Is renouncing citizenship the only full exit, and what does it cost?
Giving up citizenship, or a long-term green card, is the only way to stop U.S. tax on future gains outside Puerto Rico. It is not free. A covered expatriate is treated as selling all worldwide assets at fair market value the day before expatriation (§ 877A). You are covered for 2026 if your average annual net income tax for the five prior years exceeds $211,000, if your net worth is at least $2,000,000 (§ 877(a)(2)), or if you cannot certify five years of tax compliance. The deemed gain is reduced by an exclusion of $910,000 for 2026.
For someone holding bitcoin or shares bought long ago, the exit tax amounts to paying the whole bill at once. A second cost lasts longer: under § 2801, gifts and bequests from a covered expatriate to U.S. citizens or residents are taxed in the recipient's hands at the highest estate and gift tax rate, currently 40 percent. Renunciation therefore rarely makes sense for someone whose children or heirs are American.
Our exit tax guide covers the mechanics and the planning options, and our exit tax tool estimates exposure. For investors who keep their passport, retiring abroad and U.S. retirement accounts abroad explain how to keep tax-deferred accounts working from another country.
Common mistakes
- Treating the local exemption as the whole answer. A zero-tax country removes the local layer only. The federal tax, the 3.8 percent tax and the state tax if domicile was not broken remain.
- Assuming the foreign tax credit will absorb everything. It does not offset the 3.8 percent tax, it only offsets tax on foreign-source income, and a foreign rate below 10 percent can leave the gain U.S.-source.
- Ignoring token swaps. Each crypto-to-crypto trade is a disposal. Years of swaps on a foreign exchange with no records can produce a reconstruction bill larger than the tax.
- Answering "no" to the digital asset question after trading, staking or spending crypto.
- Buying local funds. A European or Asian ETF bought for convenience is usually a PFIC.
- Forgetting currency. A loss in euros can be a gain in dollars, and a foreign mortgage can create taxable income on repayment.
- Counting on Puerto Rico for old gains. The 10-year rule keeps pre-move appreciation federally taxable.
- Letting a broker decide. A forced closure can trigger a sale at the worst moment, or leave assets stranded without records.
Before you go
- Calculate your federal tax on the sales you plan, including the 3.8 percent tax, as if you never moved.
- Check whether your destination taxes the gain, at what rate, and whether that rate is at least 10 percent so the credit can work.
- Read the treaty, if there is one, for its saving clause and its re-sourcing rule.
- Confirm in writing that your U.S. broker will keep your account open after the move.
- Download complete transaction histories from every exchange and wallet, and set up wallet-by-wallet basis tracking.
- Avoid buying non-U.S. funds without a PFIC plan.
- Break state domicile deliberately and keep proof.
- If renunciation is on the table, run the exit tax numbers and the § 2801 consequences for your family before anything else.
- Make sure you want to live where the tax is low. A short stay followed by a return to a taxing state or country rarely pays for itself.
A note on scope: this article is general information, not tax, legal or investment advice. Rules, rates and thresholds change, foreign rules in particular. Check current law with a qualified adviser in each country involved before making a decision.
FAQ: capital gains, crypto and moving abroad
If I move to a country with zero capital gains tax, do I still owe US tax?
Yes. The United States taxes citizens and green card holders on worldwide income no matter where they live. A zero-tax country removes the local layer only — the federal long-term rate (0, 15 or 20 percent), the 3.8 percent net investment income tax above the income thresholds, and any state tax if domicile was not broken all remain due exactly as if the sale happened in the US.
Does the foreign earned income exclusion reduce tax on capital gains or crypto?
No. The exclusion covers earned income only, meaning pay for personal services. IRS Publication 54 is explicit that interest, dividends and capital gains are not earned income, so excluding a salary does nothing to a crypto sale or a stock gain reported on the same return.
Is cryptocurrency taxed differently from stocks for US expats?
The capital gains rates and holding-period rules are the same, but crypto has its own traps. Every disposal, including swapping one token for another, is a taxable event, with no like-kind exchange relief available. Staking and mining rewards are taxed as income when received, not when sold. Basis has to be tracked wallet by wallet since January 1, 2025, and the wash-sale rule does not currently apply to digital assets under the statute's text, unlike stocks.
Can I use the foreign tax credit to offset US tax on a gain from shares or crypto?
Only if the gain counts as foreign-source, and that depends on a 10 percent test. A US citizen or green card holder is treated as a nonresident for sourcing this kind of gain only if their tax home is abroad and a foreign income tax of at least 10 percent of the gain is actually paid on it. Below that 10 percent, the gain stays US-source and the local tax is generally not creditable — so a low flat local rate on crypto can end up costing more overall than a higher, creditable one.
Does renouncing US citizenship end all US tax on my capital gains?
It ends future US tax on future gains, outside Puerto Rico, but it is not free. A "covered expatriate" is treated as selling all worldwide assets at fair market value the day before expatriating, with a $910,000 exclusion for 2026 against that deemed gain. Gifts and bequests from a covered expatriate to US citizens or residents are also taxed in the recipient's hands at up to 40 percent under § 2801, which makes renunciation a poor fit for anyone whose heirs are American.
If I leave the United States, does my state automatically stop taxing my capital gains?
No. A state that still considers you domiciled there can keep taxing worldwide gains after the move; California and New York are known for scrutinizing departures closely. Ending that exposure generally takes deliberate, documented steps — leaving with your home, driver's license, voter registration and intent — not just time spent abroad.
Sources
Primary sources (accessed October 29, 2026)
- 26 U.S.C. § 1, tax imposed (capital gains rates)
- Rev. Proc. 2025-32, 2026 inflation adjustments
- 26 U.S.C. § 1411, net investment income tax
- 26 C.F.R. § 1.1411-1, general rules (paragraph (e))
- Toulouse v. Commissioner, 157 T.C. No. 4, 157 T.C. 49 (2021)
- Estate of Bruyea v. United States, No. 2025-1563 (Fed. Cir. Aug. 31, 2026)
- Christensen v. United States, No. 2024-1284 (Fed. Cir. Aug. 31, 2026)
- IRS Publication 54, Tax Guide for U.S. Citizens and Resident Aliens Abroad
- IRS Publication 514, Foreign Tax Credit for Individuals
- IRS Notice 2014-21, virtual currency
- IRS, Frequently asked questions on virtual currency transactions
- Rev. Rul. 2023-14, staking rewards
- Rev. Proc. 2024-28, basis allocation safe harbor for digital assets
- IRS, Digital assets (Form 1040 question and reporting)
- IRS, Final regulations on reporting by digital asset brokers
- IRS, Instructions for Form 1099-DA
- IRS, Understanding your Form 1099-DA
- 26 U.S.C. § 1031, like-kind exchanges of real property
- 26 U.S.C. § 1091, wash sales
- 26 U.S.C. § 865, source rules for personal property sales
- 26 U.S.C. § 904, foreign tax credit limitation
- U.S. Treasury, 2016 U.S. Model Income Tax Convention
- IRS, United States income tax treaties A to Z
- FinCEN Notice 2020-2, FBAR filing requirement for virtual currency
- IRS, Comparison of Form 8938 and FBAR requirements
- Regulation (EU) No 1286/2014 (PRIIPs)
- 26 U.S.C. § 121, exclusion of gain from sale of principal residence
- Quijano v. United States, 93 F.3d 26 (1st Cir. 1996)
- 26 U.S.C. § 877, expatriation to avoid tax
- 26 U.S.C. § 877A, tax responsibilities of expatriation
- 26 U.S.C. § 2801, gifts and bequests from expatriates
- 26 U.S.C. § 933, income from sources within Puerto Rico
- 26 U.S.C. § 937, residence and source rules involving possessions
- 26 C.F.R. § 1.937-2, income from sources within a territory
- IRS Chief Counsel, AM 2024-005, source of gain under section 937
- IRS, LB&I compliance campaigns, January 27, 2021 (Puerto Rico Act 22)
- DLA Piper, Puerto Rico Individual Resident Investor tax benefits extended through 2055 (Act 38-2026) (secondary source)
- Chapter 82.87 RCW, Washington capital gains tax
- UAE Ministry of Finance, Cabinet Decision No. 49 of 2023
- IRAS, Gains from sale of property, shares and financial instruments
- Hong Kong, Inland Revenue Ordinance (Cap. 112)
- Hong Kong Board of Review decision citing section 14 of Cap. 112
- Inland Revenue Board of Malaysia, Guidelines on capital gains tax for unlisted shares (July 21, 2025)
- The Nation Thailand, Ministerial Regulation No. 399 published in the Royal Gazette (secondary source)
- Swiss Federal Act on Direct Federal Taxation (DBG), Art. 16
- Swiss Federal Tax Administration, Circular No. 36, professional securities trading (as published by Canton Basel-Landschaft)
- Canton of Zug, information sheet on cryptocurrencies
- Germany, Income Tax Act § 23
- Germany, Income Tax Act § 32d
- German Federal Ministry of Finance, letter of March 6, 2025 on crypto-assets
- Portuguese Tax Authority, binding ruling, process 29052 (December 4, 2025)
- Panama, Law 1 of January 8, 2014, restoring Article 694 of the Fiscal Code
- Inland Revenue New Zealand, Acquiring cryptoassets to sell or exchange
A note on method: the 2026 rates and thresholds in this article were checked against Revenue Procedure 2025-32, the sourcing and credit rules against sections 865 and 904 of the Internal Revenue Code and IRS Publication 514, and the crypto rules against Notice 2014-21, Revenue Ruling 2023-14 and Revenue Procedure 2024-28. Where only a secondary source was available, the text labels it; where no official source settles a question, the text says so. Paraphrases are ours, so check the cited text before you rely on it.