Key takeaways
- Social Security keeps paying almost everywhere — Medicare almost never does. Benefits continue abroad except to Cuba, North Korea and seven restricted countries, but Medicare only covers care abroad in narrow emergency exceptions.
- The IRS doesn't care that you moved. US citizens and green card holders keep filing the same Form 1040 on worldwide income, with only an automatic extension to June 15 — interest on unpaid tax still runs from April 15.
- The foreign earned income exclusion does nothing for retirement income. The law specifically excludes pensions, annuities and Social Security from its definition of foreign earned income, and interest and dividends are not earned income either.
- Dropping Medicare Part B can be permanent and expensive if you come back. Late re-enrollment generally costs an extra 10% of the premium for every full 12 months you went without it, and you can usually only re-enroll January 1 to March 31.
- A noncitizen spouse's benefits depend heavily on their own citizenship. Some nationalities keep Social Security payments abroad without restriction; others lose them after six full calendar months abroad unless specific conditions are met.
- Whether a treaty protects your pension or Social Security depends on exactly which article covers it — France and Mexico generally give the US exclusive taxing rights over Social Security, while Thailand and the Philippines can treat private pensions completely differently.
Retiring abroad is no longer unusual for Americans. Mexico, Portugal, Costa Rica, Panama, Thailand and the Philippines all have established communities of US retirees, drawn by lower costs, a gentler climate and, often, a lower cost of medical care. What surprises many of them is how much of the United States comes along. Social Security keeps paying in most places, but Medicare mostly stops at the border. The IRS keeps taxing you as if you still lived in Ohio. And the country you move to may tax the same income again, unless a treaty or a local rule says otherwise.
This article sorts out what follows you, what stays behind, and the decisions that are hard to undo, for US citizens and green card holders, including couples in which one spouse is not American.
What problems do three different retirees face?
The same rules land differently depending on who you are. These simplified profiles are illustrations, not tax calculations.
A couple in Portugal, one spouse not American. Linda is a US citizen with Social Security and a traditional IRA. Her husband, Paulo, is a Brazilian citizen who never worked in the United States but may qualify for a spousal benefit on her record. Linda's own benefit continues because she is a citizen. Paulo's can too: Social Security lists Brazil among the countries whose citizens keep receiving payments abroad. But as neither a US citizen nor a US resident, he faces US withholding of 25.5 percent, which no treaty on Social Security's list eliminates for residents of Portugal. The couple must also decide whether to elect joint filing, covered below. Portugal generally taxes pensions at ordinary rates; how it treats Linda's IRA withdrawals, and how that interacts with US tax, depends on Portuguese law and the treaty's relief rules.
A single retiree in Mexico. Robert, 66, lives on Social Security and withdrawals from a 401(k) he rolled into an IRA. Under the US-Mexico treaty, his Social Security is taxable only in the United States. That rule does not cover his IRA withdrawals, which the United States keeps taxing because he is a citizen. Medicare does not cover him in Mexico, so Part B is his biggest health-cost decision. And Mexico is not on Social Security's list of countries where the questionnaire can come every two years rather than every year.
A former federal employee in France. Carol has a civil service pension from work not covered by Social Security, plus a smaller Social Security benefit from earlier private-sector jobs. The Windfall Elimination Provision reduced her own benefit, and the Government Pension Offset reduced the survivor benefit she receives on her late husband's record; the Social Security Fairness Act ended both for benefits payable from January 2024. In France, the treaty makes her US Social Security taxable only in the United States. Her federal pension falls under a different treaty article, which she needs to read on its own.
Does Social Security keep paying in most countries?
A US citizen can generally keep receiving Social Security retirement benefits while living abroad, as long as they remain eligible and live in a country where payments can be sent. Benefits are calculated in US dollars and are not adjusted for exchange rates, so currency swings are your risk.
Social Security treats you as "outside the United States" after 30 days in a row outside the states and territories, until you return for 30 days in a row.
Where can payments not go?
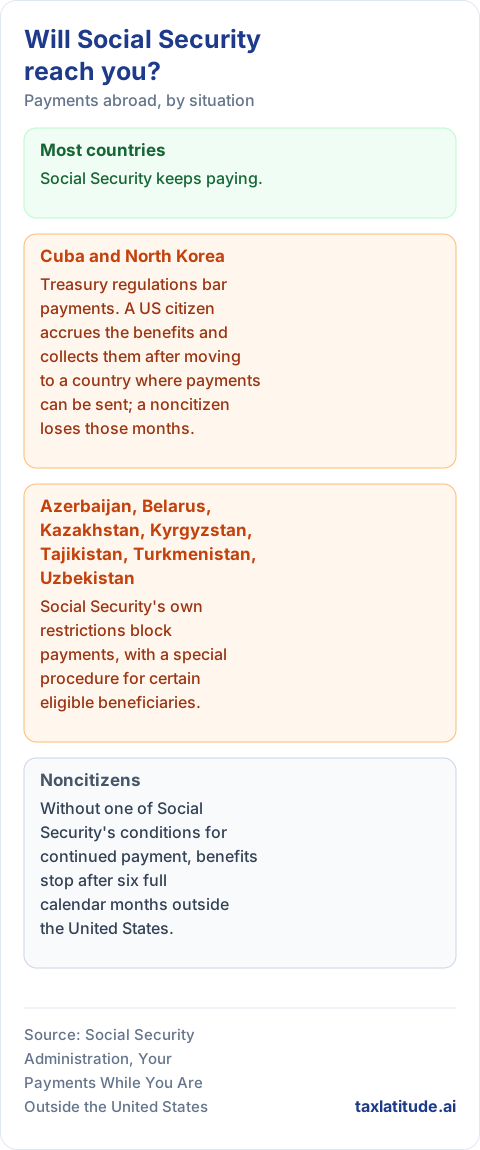
US Treasury regulations bar payments to anyone residing in Cuba or North Korea. A US citizen living there accrues the benefits and can collect the withheld payments after moving to a country where payments can be sent; a noncitizen loses those months. Social Security's own restrictions also block payments in Azerbaijan, Belarus, Kazakhstan, Kyrgyzstan, Tajikistan, Turkmenistan and Uzbekistan, with a special procedure for certain eligible beneficiaries who agree to restricted payment conditions.
What about noncitizens, including spouses and survivors?
The rules are stricter for someone who is not a US citizen, which matters for many couples. A noncitizen who does not meet one of Social Security's conditions for continued payment loses benefits after six full calendar months outside the United States. Payments then cannot restart until the person comes back and stays in the United States for a full calendar month, from the first minute of the first day to the last minute of the last day, and Social Security may ask for proof of lawful presence during that month.
The conditions depend on citizenship and residence. Citizens of one group of countries, including Brazil, Canada, France, Germany, Italy, Japan, Portugal and the United Kingdom, keep receiving payments abroad. Citizens of a second group, including Colombia, Costa Rica, Mexico and the Philippines, keep payments based on their own work but face extra requirements as dependents or survivors. Citizens of a third group, including China, India, Malaysia and Thailand, keep payments only if the worker earned at least 40 US credits or lived in the United States for at least 10 years. Residents of most countries with a US social security agreement are covered too.
A noncitizen spouse or survivor may also have to show five years of US residence while in the family relationship on which the benefit is based. The requirement does not apply to citizens of the first group, to residents of most agreement countries, or to people first eligible before 1985, among other exceptions. Use Social Security's Payments Abroad Screening Tool before you move, not after.
Is your noncitizen spouse's country on the list that keeps paying, or the one that doesn't? The rules split countries into tiers, and a spouse who doesn't meet the right condition loses payments after six full calendar months abroad. Ask TaxLatitude to check your spouse's specific situation →
What are spousal and survivor benefits?
A spouse who has reached full retirement age can receive up to 50 percent of the worker's full retirement age benefit, and less if they claim earlier. A spouse cannot receive a spousal benefit until the worker is receiving their own retirement benefit, except in the case of divorced spouses. A widow or widower who has reached full retirement age for survivors generally receives 100 percent of the deceased worker's benefit; reduced survivor benefits are available from age 60, starting at 71.5 percent. Because the survivor benefit can be the largest payment a spouse ever receives, check a noncitizen spouse's right to be paid abroad while both spouses are alive.
How do you apply for and deal with Social Security from abroad?
You can apply online, and ssa.gov/foreign gives access to Social Security's online services from abroad. You can also call +1-410-965-0160 or write to its Baltimore post office box. People in Canada, the British Virgin Islands and Samoa can visit the nearest Social Security office; everywhere else, in-person service comes from the Federal Benefits Unit that serves your country, listed on ssa.gov/foreign.
You must report changes, including a new address (even if payments go to a bank), work abroad, marriage, divorce and a death. Failing to report can lead to an overpayment that Social Security will recover, and sometimes a penalty.
How do you get paid abroad?
Payments can go to a US bank account wherever you live, unless a restriction applies, or to a local account in countries with an international direct deposit agreement; Social Security keeps the list.
What is the questionnaire?
Social Security mails a questionnaire to beneficiaries abroad every year or every two years, between May and June, and payments stop if it is not returned. The frequency depends on your age, whether you have a representative payee, the type of benefit and your country. The two-year cycle can apply to residents of a list of countries that includes Canada, Costa Rica, France, Germany, Italy, Panama, Portugal, Spain and the United Kingdom, but not Mexico, Thailand or the Philippines. On the two-year cycle, the year depends on the last two digits of your Social Security number: 00 through 49 in even years, 50 through 99 in odd years. If the questionnaire does not arrive when expected, contact Social Security or your Federal Benefits Unit.
What happens if you work abroad before full retirement age?
If you are younger than full retirement age, which is 67 for anyone born in 1960 or later, benefits are withheld for each month you work more than 45 hours outside the United States in work not subject to US Social Security taxes, including as a self-employed person or business owner. The amount you earn does not matter. You count as working on any day you are employed or self-employed, have an agreement to work even if you are sick or on vacation, or own part of a business, even one you do not work in or earn from. The rule applies even if a totalization agreement exempts you from US Social Security taxes. And if your benefit is withheld, benefits paid to dependents on your record are withheld for the same months, even if they do not work. If your work abroad is covered by US Social Security, the regular annual earnings test applies instead. Once you reach full retirement age, work no longer affects your benefit.
Are WEP and GPO gone?
One recent change helps many people who worked abroad or in the public sector. The Social Security Fairness Act, signed on January 5, 2025, ended the Windfall Elimination Provision and the Government Pension Offset. The Windfall Elimination Provision could reduce the US benefit of someone who also received a pension from work not covered by US Social Security, including a foreign pension. The Government Pension Offset reduced spousal and survivor benefits for people with a US federal, state or local government pension from work not covered by Social Security. The repeal applies to benefits payable for January 2024 and later.
What are totalization agreements and partial benefits?
The United States has social security agreements, often called totalization agreements, with countries including Brazil, Canada, France, Germany, Italy, Japan, Portugal, Spain and the United Kingdom; Social Security keeps the current list. For a retiree, credits from both countries can be combined to qualify for a partial benefit when one system alone is not enough. Social Security's claims procedures list fewer than six US quarters of coverage as a reason a totalization claim is denied. Mexico, Thailand, the Philippines, Panama and Costa Rica are not on the list. For how these agreements work while you are still earning, see our guide to self-employment abroad and totalization.
Does Medicare stop at the border?
Medicare usually does not cover health care outside the United States. The exceptions are narrow: a foreign hospital that is closer than the nearest US hospital when an emergency happens in the United States, a medical emergency while traveling through Canada between Alaska and another state, or a US resident whose nearest suitable hospital is across the border. Medicare drug plans do not cover prescriptions bought abroad.
What is Part A?
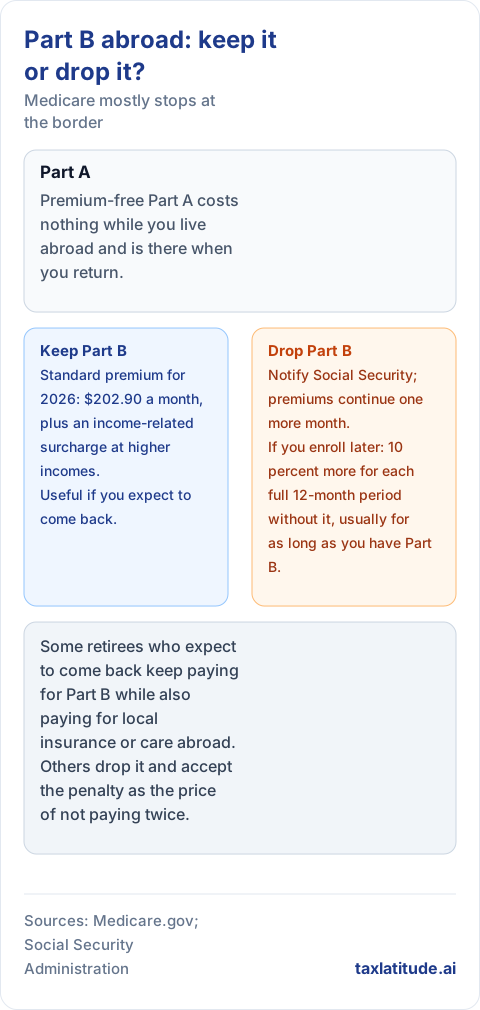
Premium-free Part A costs nothing while you live abroad, and it is available when you return to the United States.
What is the real decision with Part B?
Part B carries a monthly premium: the standard amount for 2026 is $202.90, and beneficiaries with higher modified adjusted gross income pay an income-related surcharge on top. Large IRA withdrawals or Roth conversions can push a retiree into those brackets. Social Security's own guidance notes that paying for Part B may not be to your advantage if you will be abroad for a long time. If you have Part B and want to cancel it, you notify Social Security, and premiums continue for one more month after the month you notify them.
If you drop Part B, or never sign up, and later enroll, you generally pay an extra 10 percent of the premium for each full 12-month period you could have had Part B but did not, and that penalty usually lasts as long as you have Part B. Some retirees who expect to come back keep paying for Part B while also paying for local insurance or care abroad. Others drop it and accept the penalty as the price of not paying twice.
The penalty is not the only cost. A retiree living abroad does not get a special enrollment period for Part B on returning, so outside your first enrollment window you can generally sign up only from January 1 to March 31, with coverage starting the month after you sign up. Someone who moves back in June can go months without Part B.
Weighing whether to keep paying for Medicare Part B while you're abroad? The penalty for dropping it is close to permanent, and re-enrolling is capped to a narrow January-to-March window with no special case for returning expats. Ask TaxLatitude to weigh your specific return timeline →
What about Part D and Medicare Advantage?
Medicare Advantage plans and Part D drug plans are organized around a US service area, and people who live abroad generally cannot stay enrolled (secondary source: Medicare Rights Center). When you move back, Medicare gives you a special enrollment period of two full months after the month you return to join one. Part D has its own late enrollment penalty, 1 percent of the national base beneficiary premium for each full month you were eligible but went without Part D or other creditable drug coverage, for as long as you have Part D; ask Medicare how months abroad will be counted.
What about Medigap?
Most Medigap plans (C, D, F, G, M and N, and the older E, H, I and J) include foreign travel emergency coverage. They pay 80 percent of the billed charges for certain medically necessary emergency care outside the United States after a $250 annual deductible, for care that begins during the first 60 days of a trip, with a lifetime limit of $50,000. That is travel coverage, not a health plan for someone who lives abroad.
What about local health insurance?
Whatever you decide about Medicare, budget for health insurance in your new country, and check how its premiums and exclusions change after 70 or 75.
Does the IRS retire when you move?
The United States taxes its citizens and green card holders on worldwide income wherever they live, so a retiree in Lisbon or Chiang Mai files the same Form 1040 as before. If you live outside the United States and Puerto Rico on the regular due date, you generally get an automatic two-month extension to file, to June 15 for calendar-year filers, by attaching a statement to your return. Interest on any tax still owed runs from April 15.
How does the IRS tax Social Security?
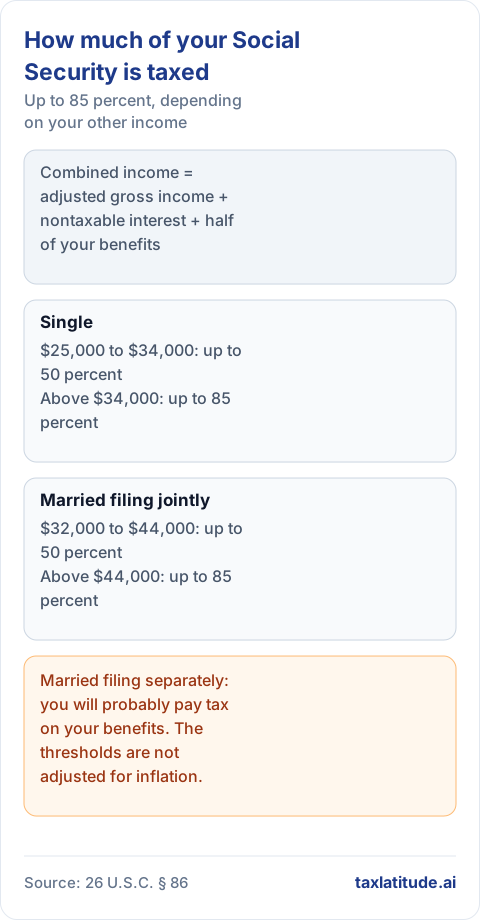
Up to 85 percent of Social Security benefits can be taxable, depending on your other income. The test uses "combined income": adjusted gross income, plus nontaxable interest, plus half of your benefits. On an individual return, up to 50 percent of benefits may be taxable if combined income is between $25,000 and $34,000, and up to 85 percent above $34,000. On a joint return the thresholds are $32,000 and $44,000. A married person filing separately will probably pay tax on their benefits. These thresholds are fixed in the law and not adjusted for inflation.
How are IRAs, 401(k)s and Roth accounts taxed?
Distributions from traditional IRAs and 401(k) plans are generally taxed as ordinary income. Required minimum distributions start at age 73 for people who reach 73 before 2033, and at 75 for those who reach 74 after 2032, which generally means people born in 1960 or later. Roth IRAs have none during the owner's lifetime. Required withdrawals raise taxable income every year, which in turn can raise the taxable share of Social Security and the Medicare Part B premium. For how US retirement accounts are treated by the country where you live, see our guide on US retirement accounts abroad and tax treaties.
What is the senior deduction?
For 2025 through 2028, filers who are 65 or older can also claim an extra deduction of $6,000 each, reduced by 6 percent of modified adjusted gross income above $75,000, or $150,000 on a joint return. It requires a Social Security number and, for married couples, a joint return. That second condition matters for couples in which one spouse is not a US citizen.
Can you file jointly with a noncitizen spouse?
A married couple generally cannot file a joint return if one spouse is a nonresident alien at any time in the year. The couple can instead elect to treat the noncitizen spouse as a US resident for the whole year and later years, which allows a joint return but brings that spouse's worldwide income onto the US return and bars a treaty claim of nonresidence. For a spouse with little income of their own, a joint return can lower the couple's tax; for a spouse with a foreign salary, pension or investments, it can raise it. Run both versions before deciding.
Why doesn't the foreign earned income exclusion help?
The foreign earned income exclusion, which many working expats rely on, does not help here: the law excludes pensions and annuities from foreign earned income, and Social Security, interest and dividends are not earned income either. Our guide comparing the foreign earned income exclusion and the foreign tax credit explains the difference.
How do double taxation and the source of income interact?
Relief from double taxation is less automatic for retirees than for workers. The US foreign tax credit can only reduce US tax on foreign-source income, and Social Security and distributions from US retirement accounts are generally US-source. When the country where you live taxes them too, relief usually depends on that country giving a credit for US tax, or on a treaty rule that changes who taxes the income or re-sources it.
What about state tax?
State tax is the one layer you may be able to leave behind, but only if you actually end your residence in your former state. Some states make that hard. See our guide to state taxes after moving abroad.
Where does the treaty or local law change the answer?
Most US tax treaties contain a "saving clause" that lets the United States keep taxing its citizens as if the treaty did not exist. But several treaties carve out Social Security and certain pensions, and some countries simply do not tax what retirees typically live on. A few examples from our country guides:
- France. Under the treaty as amended in 2004, US Social Security and distributions from US retirement plans paid to a French resident are taxable only in the United States, and this rule is an exception to the saving clause. France gives a credit for its own tax on that income. France also has a social security agreement with the United States. See our France guide.
- Mexico. Social security benefits and other public pensions paid by one country to a resident of the other, or to a US citizen, are taxable only in the paying country, and this rule is also excepted from the saving clause. Private pensions remain taxable by the United States for its citizens. There is no US-Mexico totalization agreement. See our Mexico guide.
- Thailand. The treaty makes social security benefits taxable only by the paying country, so Thailand cannot tax your US Social Security. Private pensions are treated differently. Since January 1, 2024, Thailand also taxes foreign income earned from 2024 onward that a Thai resident brings into the country, whatever the year it is transferred; income earned before 2024 is not caught if you can show when it was earned. That makes the timing and records of transfers matter. See our Thailand guide.
- The Philippines. A resident who is not a Philippine citizen is taxed there only on Philippine-source income, so US dividends, interest, IRA and 401(k) distributions and Social Security are normally taxed only by the United States. Former Filipinos who have reacquired Philippine citizenship are different: as resident citizens, they are taxed there on worldwide income. See our Philippines guide.
- Panama and Costa Rica. Both tax mainly local-source income, and neither has an income tax treaty with the United States. A retiree living on US income often owes little or no local income tax, while US tax is unchanged. See our Panama and Costa Rica guides.
- Portugal. The old non-habitual resident regime, which once exempted foreign pensions, was repealed for new arrivals, and its replacement, IFICI, does not cover foreign pensions. A retiree who moves to Portugal today generally pays Portuguese tax on pensions at ordinary rates, and how that tax interacts with US tax depends on the treaty's relief rules. Portugal does have a social security agreement with the United States. See our Portugal guide.
Treaties differ on every one of these points, and Social Security, a government pension, a private pension and an IRA can each fall under a different article. Before you rely on a treaty, read the article that applies to your income; our guide on how to read a US tax treaty explains how. If you could be a tax resident of two countries in the same year, see dual tax residency. We also cover Spain, Italy and Malaysia.
Couples in which one spouse is not American
- Benefits on the US spouse's record. Whether the noncitizen spouse is paid abroad depends on their citizenship, the country where they live and, sometimes, five years of US residence in the marriage. Check again before any later move to a third country.
- US withholding. Benefits paid to someone who is neither a US citizen nor a US resident are subject to US withholding of 30 percent of 85 percent of the benefit, or 25.5 percent, unless a treaty eliminates or reduces it. Social Security lists treaties with Canada, Egypt, Germany, Ireland, Israel, Italy, Japan, Romania and the United Kingdom that eliminate it, and a 15 percent rate for residents of Switzerland. The Mexico, Thailand and France rules described above confirm the US right to tax, so they do not remove it. Social Security's Alien Tax Screening Tool helps check whether a treaty rate applies.
- Filing status. The election to file jointly brings the noncitizen spouse into the US tax system on worldwide income. It can unlock the joint-return thresholds and the senior deduction, but it is not free — see our full article on filing when your spouse isn't a US citizen for how the election works, when it helps or hurts, and what it does to FBAR and Form 8938.
- Estates. The unlimited marital deduction does not apply to a noncitizen spouse; see the estates section below.
Do your accounts travel as well as you do?
The tax-free status of a Roth IRA is a US rule. Some countries do not recognize it and may tax its growth or its withdrawals, while some treaties protect it under conditions. The same question arises in reverse for local pension products you buy after moving. Our guide on US retirement accounts abroad and tax treaties covers the main cases.
Investments raise their own issues. Local mutual funds and many non-US ETFs are usually passive foreign investment companies for US tax purposes, with punitive default rules; see PFICs explained. Some US brokerages restrict or close accounts for clients with a foreign address, so check before you change your address on file. Foreign banks report the accounts of US persons to the IRS under FATCA, which is why some of them turn American clients away. For capital gains on a home or portfolio you sell around the move, see capital gains and crypto.
Once your foreign accounts together exceed $10,000 at any time in the year, they go on an FBAR; see our FBAR guide. Form 8938 applies above higher thresholds, which for a taxpayer living abroad start at more than $200,000 at year-end or $300,000 at any time if single, and $400,000 or $600,000 if married filing jointly.
What two sets of estate rules apply at once?
A US citizen's worldwide estate stays subject to US estate tax wherever they die. For deaths in 2026, the basic exclusion amount is $15,000,000, so most retirees will owe no federal estate tax, but larger estates still need planning. If your spouse is not a US citizen, the unlimited marital deduction does not apply: property left to them generally qualifies only through a qualified domestic trust.
At the same time, the country where you live may apply its own inheritance tax and its own succession law, including rules that reserve part of an estate for children whatever a will says. A US will may not work smoothly abroad, and property held through a local company or trust can complicate things further. Social Security also needs to know about a death promptly: no benefit is payable for the month of death, so the payment issued the following month must be returned. See our article on estate planning abroad.
Common mistakes
- Assuming the foreign earned income exclusion covers a pension. It does not apply to pensions, annuities or Social Security.
- Dropping Medicare Part B without deciding what happens if you come back. The late enrollment penalty is usually permanent, and there is no special enrollment period for Part B when a retiree returns.
- Moving a noncitizen spouse abroad without checking their benefits. Payments on your record can stop after six full calendar months abroad unless a condition for continued payment is met, and restarting them requires a full calendar month back in the United States.
- Ignoring the Social Security questionnaire. If it is not returned, payments stop.
- Taking a part-time job abroad before full retirement age. More than 45 hours of work in a month can cost that month's benefit, and the benefits of dependents on your record too.
- Treating the June 15 extension as extra time to pay. Interest on unpaid tax still runs from April 15.
- Treating a residence visa as a tax decision. Immigration status and tax residence are separate questions, in both countries.
- Relying on a preferential regime without reading its current rules. Portugal's former regime is the best-known example of a program that closed to new arrivals.
- Assuming a Roth IRA is tax-free everywhere. Its US status does not bind the country where you live.
- Forgetting the FBAR for a local bank account. The $10,000 threshold counts all your foreign accounts together.
Before you go
- Run Social Security's screening tool for your destination, especially if your spouse is not a US citizen.
- Check whether your destination has international direct deposit, and find the Federal Benefits Unit that serves it.
- Decide about Medicare Part B with the penalty and the January to March enrollment window in mind, and tell any Medicare Advantage or Part D plan that you are moving, since those plans are tied to a US service area.
- Price local health insurance at 75, not at 65.
- Read the treaty article that applies to each kind of income you will receive: Social Security, government pension, private pension, IRA.
- If your spouse is not a US citizen, compare filing separately with the election to file jointly.
- Close your state residence cleanly if you want to stop paying state tax.
- Check what your brokerage does with a foreign address, and avoid buying local funds before reading about PFICs.
- Make sure your estate plan works in both countries, including a qualified domestic trust if your spouse is not a citizen.
A note on scope: this article is general information, not tax, legal or financial advice. Benefit rules, tax rates and local regimes change, and each should be confirmed with the relevant agency or a professional before you act.
FAQ: retiring abroad as an American
Can I still receive Social Security if I retire abroad?
Generally yes, as long as you remain eligible and live in a country where payments can be sent. Payments cannot go to Cuba or North Korea, though a US citizen there still accrues the benefits and can collect them later, and Social Security restricts payments to seven other countries with a special procedure for certain beneficiaries.
Does Medicare cover healthcare if I live abroad?
No, with only narrow exceptions: a foreign hospital that happens to be closer than the nearest US hospital during an emergency that begins in the United States, or a medical emergency while transiting Canada between Alaska and another state. Medicare drug plans also do not cover prescriptions bought abroad, which is why Part B is usually the biggest health-cost decision for a retiree moving overseas.
Does the United States stop taxing me once I retire and move abroad?
No. The United States taxes citizens and green card holders on worldwide income wherever they live, so a retiree abroad files the same Form 1040 as before, including tax on Social Security, IRA and 401(k) distributions. Living abroad only affects the filing deadline, with an automatic extension to June 15 for those outside the US on the regular due date.
Does the foreign earned income exclusion help reduce tax on my pension or Social Security?
No. The exclusion only covers foreign earned income, and the law specifically excludes pensions and annuities from that definition. Social Security, interest and dividends are not earned income either, so the exclusion that many working expats rely on does nothing for typical retirement income.
If my spouse isn't a US citizen, can they still receive Social Security spousal benefits abroad?
It depends on citizenship and residence. Citizens of some countries, including Brazil, Canada, France, Germany, Italy, Japan, Portugal and the UK, keep receiving payments abroad. Citizens of other countries, including China, India, Malaysia and Thailand, only keep payments if the worker earned at least 40 US credits or lived in the US for at least 10 years. A noncitizen spouse who doesn't meet one of these conditions loses benefits after six full calendar months outside the United States.
Should I keep paying for Medicare Part B if I live abroad full-time?
There's a real trade-off either way. Dropping it avoids a premium for coverage that mostly doesn't work abroad, but re-enrolling later generally costs an extra 10 percent of the premium for each full 12-month period you could have had it and didn't, and you can usually only sign up again between January 1 and March 31, with no special window for returning from abroad. Some retirees who expect to move back keep paying for Part B anyway as the price of not facing that penalty and gap in coverage later.
Sources
Primary sources (accessed October 29, 2026)
- Social Security Administration, Your Payments While You Are Outside the United States, Publication No. 05-10137 (April 2026)
- Social Security Administration, Payments Abroad Screening Tool
- Social Security Handbook, § 1848, Restricted countries (revised August 27, 2026), and POMS VB 01201.015
- Social Security Administration, Social Security Fairness Act (updated July 21, 2025)
- Social Security Administration, Countries with international direct deposit
- Social Security Administration, Status of Totalization Agreements
- Social Security Administration, POMS GN 01701.005, International Social Security (Totalization) Agreements and GN 01704.880, Totalization status codes
- Social Security Administration, Family benefits
- Social Security Administration, What you could get from survivor benefits
- Medicare.gov, Travel outside the U.S. and What Medigap covers
- Medicare.gov, Medicare Coverage Outside the United States (fact sheet)
- Medicare.gov, Avoid late enrollment penalties
- Medicare.gov, When does Medicare coverage start?
- Medicare.gov, Special Enrollment Periods
- Medicare.gov, 3 ways to avoid the Part D late enrollment penalty
- CMS, 2026 Medicare Parts A & B Premiums and Deductibles (November 14, 2025)
- 26 U.S.C. § 86, Social Security benefits
- 26 U.S.C. § 911(b)(1)(B), Pensions and annuities excluded from foreign earned income
- 26 U.S.C. § 151(d)(5)(C), Deduction for seniors, added by Pub. L. 119-21 (2025)
- 26 U.S.C. § 401(a)(9)(C)(v), Applicable age for required minimum distributions
- 26 U.S.C. § 2056(d), Surviving spouse who is not a US citizen
- 26 U.S.C. § 6013, Joint returns
- 26 C.F.R. § 1.6013-6, Election to treat nonresident alien individual as resident of the United States
- IRS, Rev. Proc. 2025-32, 2026 inflation adjustments
- IRS, Publication 514 (2025), Foreign Tax Credit for Individuals
- IRS, U.S. citizens and resident aliens abroad: automatic 2-month extension of time to file
- IRS, Retirement plan and IRA required minimum distributions FAQs (reviewed January 29, 2026)
- IRS, Comparison of Form 8938 and FBAR requirements
- IRS, What's new: Estate and gift tax and Instructions for Form 706
- Country-specific treaty and local tax points are drawn from TaxLatitude's country guides linked above, each of which lists its own primary sources. For Thailand's treatment of income earned before 2024, see also Thai Revenue Department, Instruction Paw. 162/2566 of November 20, 2023 (in Thai).
Secondary source
- Medicare Rights Center, Medicare and living abroad (secondary source), on Medicare Advantage and Part D service-area rules for people living outside the United States
A note on method: the benefit, Medicare and tax rules in this article were checked against Social Security Administration publications and handbook, Medicare.gov, IRS publications and the Internal Revenue Code, the treaty texts cited, and the official sources of the countries named, including Thailand's Revenue Department. The three retirees are fictional profiles, not tax calculations. Where only a secondary source was available, the text labels it; where no official source settles a question, the text says so. Paraphrases are ours, so check the cited text before you rely on it.