Key takeaways
- An American who owns a foreign company alone, or with a US spouse, almost always owns a CFC. A controlled foreign corporation is one where US shareholders (each owning at least 10%) together own more than 50% of vote or value — family attribution counts a spouse's and children's shares toward that test.
- Being a CFC shareholder means paying US tax every year, whether or not the company pays out profits. Subpart F income and net CFC tested income (formerly called GILTI) are both taxed annually, at ordinary rates up to 37% for an individual, with none of the breaks a US corporation gets.
- The foreign earned income exclusion does not cover CFC inclusions — it only shields pay for your own personal services, like a salary, not the company's retained profits.
- Missing Form 5471 can cost more than the tax itself. The penalty is $10,000 per foreign corporation per year, with another $10,000 for every 30 days after an IRS notice, up to $50,000 more — and it applies even if the company made no profit.
- A non-American spouse's shares are not attributed to you. Under §958(b)(1), a 50/50 split with a non-US spouse can keep the company from being a CFC at all — though it can then be a PFIC instead.
- Four main ways to manage the US tax: a real local salary, the high-tax exclusion (if foreign tax on US-measured income exceeds 18.9%), a section 962 election (taxed as if a US corporation), or disregarding the entity — none right in every case.
Forming a company has never been easier: an Estonian company through e-Residency, a UK private limited company registered online, or a Wyoming LLC set up from an apartment in Lisbon. For most founders, the only question is how the country where the company is formed will tax it. A US citizen or green card holder has a second question that never goes away: what does the IRS make of it?
Owning a company abroad is legal and often sensible. But the United States looks through the structure far more than most founders expect, and the paperwork penalties can exceed the tax itself. This article walks through the rules that decide what you owe and what you file, starting with the 2026 tax year. If you are a founder receiving shares that vest over time, the 30-day deadline for the §83(b) election is covered in our guide for foreign startup founders.
Can you own a foreign company, and how does the IRS classify it?
Apart from US sanctions and the outbound investment rules that cover certain technology investments in China, Hong Kong and Macau, no US law stops a citizen from forming or owning a company in another country, and most countries welcome foreign founders. What matters for your US return is how the entity is classified for federal tax purposes: as a corporation, a partnership, or an entity "disregarded" as separate from its owner.
That classification is a US tax label only. A German GmbH remains a taxable company in Berlin even if the IRS treats it as part of its owner.
What are per se corporations?
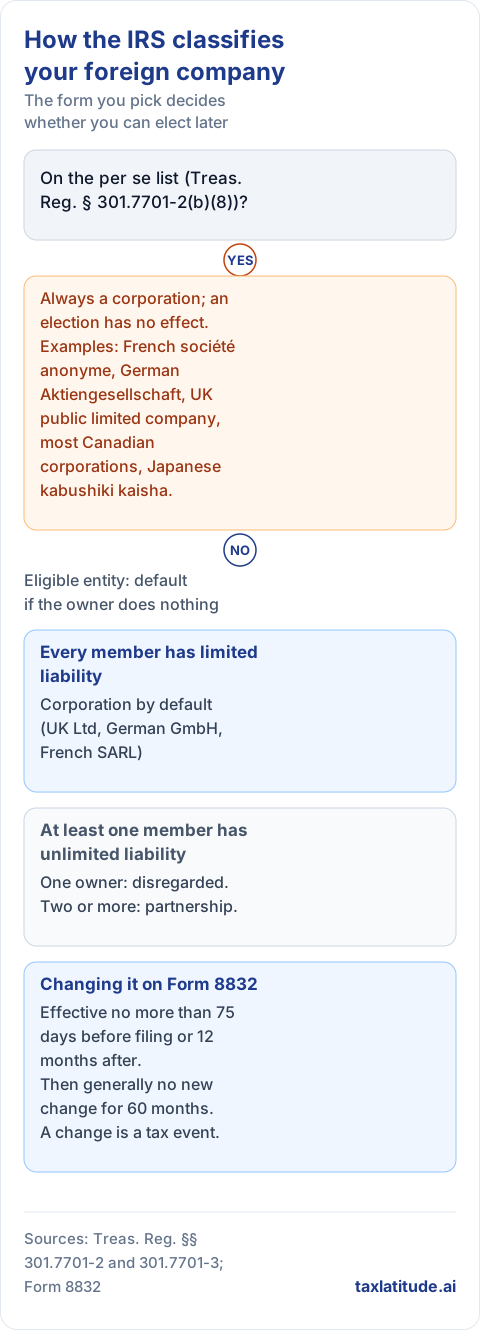
Some foreign company forms are always treated as corporations. Treasury regulations list them by country: a French société anonyme, a German Aktiengesellschaft, a UK public limited company or an Estonian aktsiaselts, for example. The list is not limited to large companies: it also includes most Canadian corporations and the Japanese kabushiki kaisha, both common forms for small businesses. For a company on the list, an election to change classification has no effect.
The private limited forms that small businesses usually choose are generally not on the list: the UK private limited company, the German GmbH, the French SARL and the Estonian osaühing, for example. Read your country's entry in Treas. Reg. § 301.7701-2(b)(8) before forming anything, because the form you pick decides whether you can elect later.
What are eligible entities, and what are their default classifications?
Most other foreign entities are "eligible entities" that can choose. If the owner does nothing:
- If every member has limited liability, the entity is a corporation by default.
- If at least one member has unlimited liability, a single-owner entity is disregarded and an entity with two or more owners is a partnership.
A UK Ltd, a German GmbH or a French SARL owned by one American is therefore a foreign corporation for US purposes unless the owner elects otherwise.
How do you change the classification, step by step?
The owner of an eligible entity changes its classification on Form 8832:
- Timing. The election cannot take effect more than 75 days before it is filed, or more than 12 months after.
- The 60-month rule. Once you change classification, you generally cannot change it again for 60 months.
- A change is a tax event. A corporation that elects to become disregarded is treated as distributing all its assets and liabilities to its owner in liquidation. The reverse change is treated as the owner contributing assets and liabilities to a new corporation for its stock; for a foreign corporation, that deemed transfer can bring Form 926.
- Earnings make it expensive. A deemed liquidation of a company with built-up earnings can produce dividend income under section 1248, discussed below. The cheapest time to choose is at formation.
That choice drives almost everything below. A foreign corporation brings the controlled foreign corporation rules and Form 5471. A foreign disregarded entity puts its profits directly on your own return, as if you had earned them yourself, and brings Form 8858 instead.
When is a foreign corporation you control a CFC?
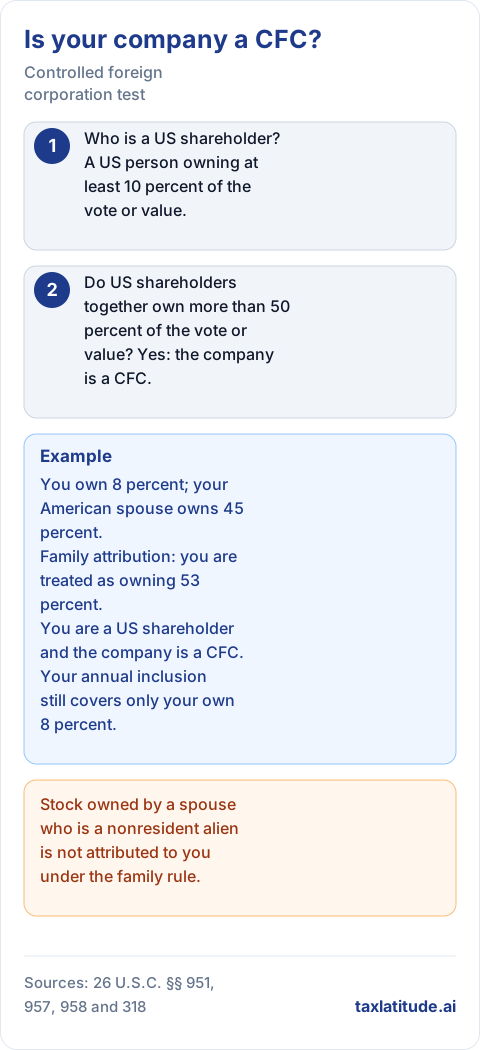
A foreign corporation is a controlled foreign corporation (CFC) when US shareholders own more than 50 percent of its vote or value. Only US persons who own at least 10 percent of the vote or value count as "US shareholders." An American who owns a company abroad alone, or with a US spouse, almost always owns a CFC.
How is ownership counted?
Ownership is counted in three layers: stock in your name, stock held indirectly through foreign entities, and stock attributed to you under the constructive ownership rules of section 318, as modified for CFCs. Constructive ownership decides whether you are a US shareholder and whether the company is a CFC; the annual inclusion itself uses only direct and indirect ownership.
Family attribution treats you as owning stock held by your spouse, children, grandchildren and parents. If you own 8 percent and your American spouse owns 45 percent, you are treated as owning 53 percent: you are a US shareholder even though your own stake is below 10 percent, and the company is a CFC. Your annual inclusion still covers only your own 8 percent.
Your own stake under 10%, but your American spouse owns the rest? Family attribution can still make you a "US shareholder" through the combined ownership test, even though your personal inclusion stays limited to your own share. Ask TaxLatitude to check whether your company counts as a CFC →
What happens when one spouse is not American?
Section 958(b)(1) provides that stock owned by a nonresident alien individual is not attributed to a US citizen or resident under the family rule.
Take Claire, a US citizen living in Lyon, and her French husband, who is neither a US citizen nor a US resident. Each owns 50 percent of a SARL. Claire is a US shareholder, but US shareholders together own exactly 50 percent, not more than 50 percent, so the SARL is not a CFC. Claire has no annual Subpart F or net CFC tested income inclusion. She files Form 5471 for the year she acquired her shares, but not every year as a controlling shareholder, and the company's accounts are on her FBAR only if she has signature authority.
That result can change. If Claire's share rises above 50 percent, or another US person buys in, the SARL becomes a CFC. And because the SARL is not a CFC, a mostly passive SARL can be a PFIC for Claire. An election to treat a non-American spouse as a US resident for joint filing can change this analysis, so check it before making that election — see our full article on the §6013(g) election for how it works and what it changes. See our France guide.
What is taxed every year?
Being a CFC shareholder means paying US tax on some of the company's profits each year, whether or not the company pays them out. Two main categories are reached.
Subpart F income is mainly passive income such as dividends, interest, royalties, rents and certain gains, plus certain sales income from deals with related parties and income from services performed for a related person outside the company's country of incorporation. A UK consulting company billing unrelated UK clients for work done in the UK does not earn that services income. These categories together are called "foreign base company income." If it is below the lesser of 5 percent of gross income or $1,000,000, none of it is treated as such; above 70 percent of gross income, all of the company's gross income is.
Net CFC tested income is, broadly, the rest of the company's business profits. This is the regime that used to be called GILTI. The tax law enacted on July 4, 2025 (Public Law 119-21) renamed it for tax years beginning after December 31, 2025, and removed the old allowance for a return on the company's tangible assets. A company with significant equipment or property no longer gets that carve-out, so its inclusion can be larger in 2026 than in 2025. The inclusion is computed on Form 8992.
The same 2025 law also put back a rule, for tax years of foreign corporations beginning after December 31, 2025, that stops US persons from being treated as owning stock held by a foreign person. That mostly affects groups with a foreign parent; it does not change the picture for an American who owns a company directly.
Are you taxed once, not twice?
Profits already included are not taxed again as income when distributed: section 959 treats them as previously taxed earnings. But the distribution can still be subject to the 3.8 percent net investment income tax, and exchange rate movements can create a currency gain or loss under section 986(c).
Why do individuals get the worst version of these rules?
The CFC rules were written with US parent companies in mind, and an individual owner gets a much harsher version:
- An individual includes net CFC tested income at ordinary rates, which now go up to 37 percent.
- An individual gets neither the 40 percent deduction that a US corporation receives on that income nor a credit for the corporate tax the company already paid abroad. The credit for the foreign taxes a company pays on that income (90 percent of them, from 2026) belongs to domestic corporations.
- The foreign earned income exclusion does not help, because these inclusions are not pay for your personal services.
Left alone, the result can be US tax on profits that were already taxed abroad and that never reached your bank account.
Four ways owners deal with it
Can you pay yourself a salary?
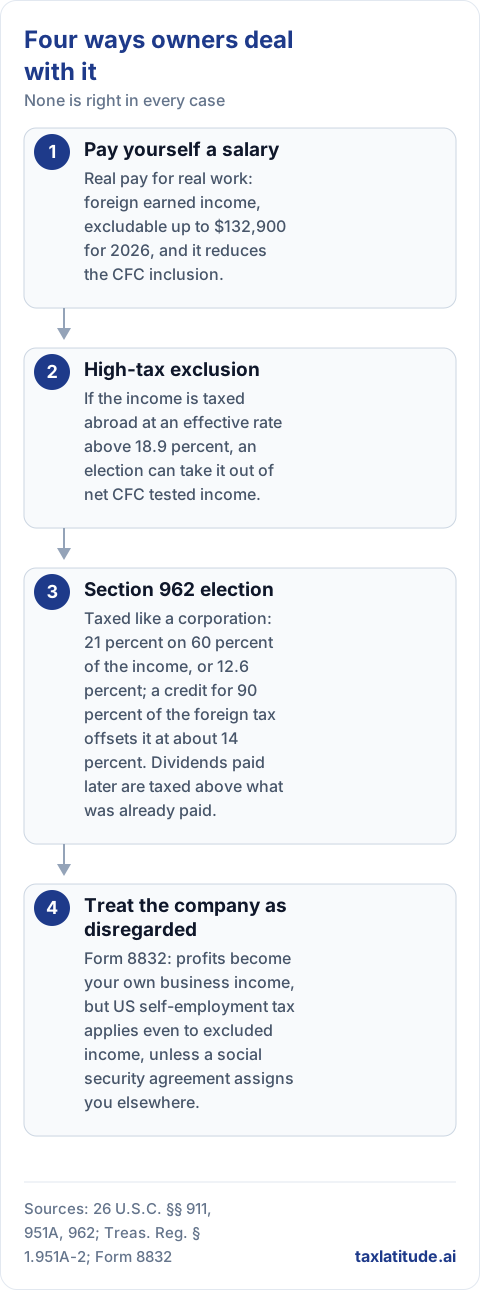
Wages for work you perform abroad are foreign earned income, which the foreign earned income exclusion can cover, if you qualify for it, up to $132,900 for 2026. The foreign tax credit is the alternative. Salary also reduces the company's profits, and with them the CFC inclusion. It has to be real pay for real work, deductible under local rules, and it brings payroll obligations in the country where you work. See FEIE versus the foreign tax credit.
Can you use the high-tax exclusion?
If the company's income is taxed abroad at an effective rate above 90 percent of the US corporate rate, that is, above 18.9 percent, an election can take it out of net CFC tested income. A parallel exception exists for Subpart F income. Four details decide the result:
- Per tested unit. The rate is computed separately for each "tested unit": the CFC itself and certain branches or transparent entities it holds, with units in the same country generally combined.
- US measure of income. The denominator is income measured under US tax rules. If local law allows faster deductions than US rules, the effective rate can fall below the headline rate.
- Tax actually paid. Countries that tax company profits mainly when they are distributed, such as Estonia, generally fail the test in years when profits are retained.
- Group-wide and deadline-bound. The election binds all the CFCs in a commonly controlled group, and it has to be made with a timely original return or on an amended return filed within 24 months of the original return's unextended due date.
Where the foreign tax actually paid clears that level, the election can remove the CFC inclusion entirely.
Not sure if your company's foreign tax actually clears 18.9% under US rules? The test uses income measured under US tax rules, not your country's headline rate — a higher sticker rate can still fail it if local law allows faster deductions. Ask TaxLatitude to work through your company's effective rate →
Can you make a section 962 election?
This lets an individual be taxed on CFC inclusions as if they were a US corporation: at the 21 percent corporate rate, with the 40 percent deduction that corporations get on net CFC tested income and a credit for the company's foreign taxes. The election is made each year with a statement attached to the return.
A simplified illustration, ignoring the credit limitation rules: 21 percent on 60 percent of the income is 12.6 percent. A credit for 90 percent of the foreign tax offsets that once the foreign rate reaches about 14 percent (12.6 divided by 0.9). A company taxed abroad between 14 and 18.9 percent, too little for the high-tax exclusion, can therefore leave little or no current US tax under the election.
The cost comes later. When the company actually pays the profits out, the dividend is taxable to the extent it exceeds the US tax already paid under the election. That dividend may qualify for the lower qualified-dividend rates if the company is eligible for the benefits of a comprehensive US income tax treaty.
Can you treat the company as disregarded?
With a Form 8832 election, a single-owner foreign company that is an eligible entity can become, for US purposes only, part of you. Its profits then appear on your return as your own business income: the earned portion can qualify for the exclusion, and foreign taxes on the income you do not exclude can generally be credited. No credit is allowed for foreign tax on income the exclusion already covers.
In exchange, US self-employment tax applies even to income the exclusion covers, unless a US social security agreement assigns you to the other country's system. Where both capital and your personal services produce the income, generally no more than 30 percent of the net profit counts as earned income. Changing the classification of an existing company is treated as a liquidation, so the timing matters. See self-employment tax and totalization agreements.
None of these is right in every case, and they interact with each other and with the other country's rules.
Why can two owners get two different outcomes?
Anna in Berlin. Anna, a US citizen, owns 100 percent of a GmbH that provides IT consulting to unrelated German clients. The GmbH is an eligible entity and, by default, a corporation and a CFC. Its profits are tested income, not Subpart F income, because the services are performed in Germany for unrelated clients. German corporate tax is 15 percent, plus a solidarity surcharge and a municipal trade tax. Because that combined burden normally exceeds 18.9 percent, a high-tax exclusion election will often remove the inclusion, if the German tax still clears that level on income measured under US rules. Her salary is foreign earned income on her US return. See our Germany guide.
Ben in London. Ben owns 100 percent of a UK private limited company with modest profits. UK corporation tax is 19 percent on profits up to £50,000, with marginal relief up to £250,000 and a 25 percent main rate above that. Nineteen percent is barely above 18.9 percent. If UK capital allowances give his company larger deductions than US depreciation would, its effective rate on US-measured income can fall below the threshold, and the exclusion fails. Ben would then pay US tax at up to 37 percent on retained profits, with no credit for UK corporation tax, unless he uses a section 962 election or a higher salary. See our UK guide.
What happens to the American abroad with a US LLC?
Many Americans who move abroad keep running their business through a US LLC. For the IRS, a single-member US LLC is disregarded by default. Its profits go on Schedule C of your Form 1040 and are subject to self-employment tax, even where the exclusion removes the income tax, unless a social security agreement says otherwise. The Form 5472 reporting for foreign-owned single-member LLCs does not apply to a US owner.
Carla in Lisbon. Carla runs a design business through a Wyoming LLC and has moved to Portugal. Her US return keeps Schedule C, with the exclusion available on her net earnings if she meets the residence or physical presence test. The United States and Portugal have a social security agreement under which a self-employed person is generally covered only by the country of residence, documented with a certificate of coverage. The open questions are Portuguese: how Portugal classifies a US LLC, and whether managing it from Lisbon makes it resident there. Ask a Portuguese adviser before the first local return. See our Portugal guide and state taxes after moving abroad.
The country where you live may see the same LLC very differently. The United Kingdom is the best-known example: HMRC's guidance generally treats US LLCs as companies rather than as transparent entities. The UK Supreme Court's 2015 Anson decision allowed one member relief for US tax on his share of LLC profits, but HMRC said the ruling turned on its facts and kept its general approach. In a consultation that ran from June 10 to July 31, 2026, the UK government looked at letting UK-resident individual members of US LLCs be taxed on a transparent basis. Its response, published on October 28, 2026, chose a different route: the LLC would stay opaque for the member, distributions would be taxed at dividend rates, and members could elect a credit for US federal, state and local taxes they paid personally, based on an average foreign tax rate. The government plans to legislate in a future Finance Bill, with claims possible from early 2028, and says a further technical consultation will follow.
When two countries disagree about whether the entity or its owner is the taxpayer, they can tax different people at different times, and a foreign tax credit may not line up with the US tax it is meant to offset. That mismatch is the first thing to check before moving abroad with an LLC. See also digital nomads.
Where is the company actually managed?
The United States decides whether a company is domestic by where it was created or organized. Many other countries also look at where it is run:
- Spain treats an entity as resident if its place of effective management is in Spain. Run your Delaware corporation from your kitchen table in Madrid and Spain may tax its profits.
- Germany treats a corporation as fully taxable there if its place of management or its registered seat is in Germany.
- The United Kingdom treats UK-incorporated companies as resident by statute, and a foreign company as resident if its central management and control is exercised in the UK, a test developed by the courts.
A company can then be resident in both countries. The 2016 US Model Income Tax Convention, the template the United States uses to negotiate its tax treaties, says that such a company is not treated as resident of either country for claiming treaty benefits. Actual treaties vary. See how to read a US tax treaty.
Even when the company stays foreign, a home office from which the business is regularly carried on can be a "permanent establishment": a fixed place of business that lets your country of residence tax the profits attributable to it. Article 5 of the 2016 Model lists a place of management and an office among its examples, and also covers a person who habitually concludes contracts for the company. Remote work has made both questions more common, not less.
What are the forms, and why can they cost more than the tax?
For many owners, the largest risk is not the tax but a missing information return. Most of these forms are attached to your income tax return and due with it, including extensions: June 15 automatically for Americans abroad, October 15 on request.
What is Form 5471?
Form 5471 is filed with your return each year by a US person who controls a foreign corporation (more than 50 percent of vote or value) and by US shareholders of a CFC. It is also required, for the year of the event, from a US person who acquires 10 percent or more of a foreign corporation, even one that is not a CFC, and from US officers and directors of a foreign corporation in which a US person makes such an acquisition. The instructions sort these filers into categories 2 (officers and directors), 3 (acquisitions), 4 (control) and 5 (US shareholders of a CFC); category 1 concerns the 2017 transition tax. A sole owner is usually category 4 and 5.
The penalty for not filing is $10,000 per foreign corporation per year. If the failure continues more than 90 days after an IRS notice, another $10,000 applies for each 30-day period, up to $50,000 more. Foreign tax credits can be reduced as well. None of this depends on the company making a profit.
The other returns
- Form 8992 computes the net CFC tested income inclusion.
- Form 8858 covers a foreign disregarded entity, with the same $10,000 penalty structure under section 6038. Form 8865 covers a foreign partnership.
- Form 926 reports transfers of property, including cash, to a foreign corporation. A cash transfer must be reported if you own at least 10 percent of the company right after it, or if your cash transfers to it exceed $100,000 over 12 months. The penalty is 10 percent of the value transferred, capped at $100,000 unless the failure was intentional.
- The FBAR covers the company's bank accounts if you own more than 50 percent of it, and accounts over which you have signature authority, once all your foreign accounts together exceed $10,000 at any time in the year. It goes to FinCEN, due April 15 with an automatic extension to October 15. See our FBAR guide.
- Form 8938 counts your interest in the foreign company toward its thresholds, even when the company is already reported on Form 5471, though you do not describe it again in detail; you list the Form 5471 in Part IV. The thresholds for a taxpayer living abroad are more than $200,000 at year-end or $300,000 at any time if single, and $400,000 or $600,000 if married filing jointly. A missing Form 8938 carries its own $10,000 penalty, with up to $50,000 more after a notice.
Does the assessment period stay open?
When required foreign information returns such as Form 5471 or Form 926 are not filed, the IRS's time to assess tax for that year does not run out until three years after the information is provided. If the failure was due to reasonable cause, only the related items stay open. The IRS publishes delinquent international information return submission procedures for taxpayers with reasonable cause who are not under examination.
What about investment companies?
A foreign corporation whose income is at least 75 percent passive, or whose assets are at least 50 percent passive, is a passive foreign investment company (PFIC), with its own punitive regime. For a US shareholder of a CFC, the CFC rules generally take priority and the PFIC rules do not apply for that period. A non-controlled company, like Claire's SARL, gets no such protection. See PFICs explained.
Does the bank already know?
Under FATCA, banks around the world report accounts held by US persons to the IRS, including accounts of certain foreign entities with substantial US owners. A foreign bank will ask you for a Form W-9, and some banks turn away US clients altogether rather than take on the reporting. Opening an account for your company abroad is often harder than forming it. The United States has not joined the Common Reporting Standard, the system other countries use to exchange the same information among themselves. See FATCA and the CRS.
One US filing has gone away. FinCEN's final rule of August 11, 2026, effective August 14, 2026, permanently exempts US companies and US persons from beneficial ownership reporting under the Corporate Transparency Act. Foreign companies registered to do business in a US state still report, but only their non-US beneficial owners. A foreign company owned by an American therefore does not report the American.
Does the global minimum tax affect you yet?
The OECD's 15 percent global minimum tax, known as Pillar Two, applies to groups with annual revenue of €750 million or more. In January 2026 the countries of the OECD/G20 Inclusive Framework agreed on a "side-by-side" package under which groups headquartered in the United States can use a safe harbor that switches off two of its main rules, in recognition of the US minimum tax rules they already face. Countries can still apply their own domestic minimum taxes. For an owner-operated company, none of this applies directly. What it shows is the direction of travel: profits booked where nothing real happens are getting harder to defend.
What happens when selling, liquidating or borrowing?
Selling. When you sell stock of a company that was a CFC while you were a 10 percent US shareholder, section 1248 treats the gain as a dividend to the extent of earnings accumulated during your ownership and not already taxed to you. For individuals, section 1248 also caps the tax on that portion.
Liquidating. An individual who receives the company's assets in a complete liquidation is treated as selling the stock for them, so section 1248 applies the same way, including to the deemed liquidation that follows a disregarded-entity election.
Borrowing. When a CFC lends money to its US shareholder, or pledges its assets or guarantees the shareholder's debt, section 956 can treat the amount as an investment in US property and tax it to an individual owner as if it had been paid out, up to the company's earnings.
For renouncing citizenship or a long-held green card, see the exit tax guide and our exit tax tool; for heirs, estate planning abroad.
Common mistakes
- Assuming a CFC's profits escape US tax until paid out. Subpart F income and net CFC tested income are taxed each year.
- Applying the foreign earned income exclusion to company profits. It covers pay for your work only.
- Relying on the headline rate for the high-tax exclusion, or missing its deadline.
- Forgetting Form 5471 because the company made no profit.
- Electing disregarded treatment after earnings have built up.
- Counting a non-American spouse's shares toward control.
- Running a US LLC from abroad without checking how your new country sees it.
- Managing the company from home without asking where it is resident.
- Assuming a sale or liquidation produces only capital gain.
- Borrowing from your own company.
- Leaving the company's bank accounts off the FBAR.
Before you start
- Check whether the local form is on the per se list.
- Decide the US classification at formation, within the Form 8832 window.
- Count US ownership, including family attribution and the nonresident spouse exception.
- Estimate foreign tax on US-measured income against 18.9 percent and, under section 962, about 14 percent.
- Set a real, locally deductible salary.
- Ask how your country of residence classifies the entity and whether it becomes resident there.
- Check self-employment tax and the social security agreement for a disregarded business.
- Calendar Form 926, Form 5471 or 8858, Form 8992, the FBAR and Form 8938.
- Keep accounts that allow US earnings and profits to be computed.
What does this mean for your US return?
Owning a company abroad is legal, and it can be the right tool: to sign local clients, to hire, to meet investor or licensing requirements, or simply because you live there. But for a US citizen the structure never ends at the border. Four questions decide the outcome: how the entity is classified for US purposes, whether it is a CFC and which of its profits are reached each year, where the company is actually managed, and whether every information return is filed on time. The best structure is usually the simplest one that answers all four consistently, in both countries.
A note on scope: this article is general information, not tax or legal advice. Each cross-border structure needs its own professional review in every country involved, and the rules described here change often enough that they should be confirmed before you rely on them.
Frequently asked questions
What is Form 5471?
Form 5471 is the information return that reports a US person's interest in certain foreign corporations. It is filed with your return each year by a US person who controls a foreign corporation (more than 50 percent of vote or value) and by US shareholders of a controlled foreign corporation (CFC). It is also required, for the year of the event only, from a US person who acquires 10 percent or more of a foreign corporation, even one that is not a CFC, and from US officers and directors of a foreign corporation in which a US person makes such an acquisition.
Who needs to file Form 5471?
Anyone who falls into one of the filer categories the instructions define: officers and directors of a foreign corporation (category 2), someone who acquires 10 percent or more of a foreign corporation (category 3), someone with control of a foreign corporation (category 4), or a US shareholder of a CFC (category 5). A sole owner of a foreign company is usually both category 4 and category 5. Filing does not depend on the company making a profit.
What are the Form 5471 filer categories?
The instructions sort filers into categories 2 through 5 for individuals: category 2 covers US officers and directors of a foreign corporation in which a US person makes a qualifying acquisition; category 3 covers a US person who acquires 10 percent or more of a foreign corporation; category 4 covers control of a foreign corporation; and category 5 covers US shareholders of a CFC. Category 1 is separate and concerns the 2017 transition tax.
When is Form 5471 due?
Form 5471 is attached to your income tax return and due with it, including extensions: the automatic June 15 extension for Americans abroad, or October 15 if requested.
What is the penalty for not filing Form 5471?
The penalty is $10,000 per foreign corporation per year. If the failure continues more than 90 days after an IRS notice, another $10,000 applies for each additional 30-day period, up to $50,000 more. Foreign tax credits can also be reduced, and none of this depends on the company having made a profit.
What is a controlled foreign corporation (CFC)?
A foreign corporation is a CFC when US shareholders together own more than 50 percent of its vote or value. Only US persons who own at least 10 percent of the vote or value count as "US shareholders" for this test. Ownership is counted across three layers (direct stock, indirect stock through foreign entities, and constructive ownership attributed under family attribution rules), so an American who owns a company abroad alone, or together with a US spouse, almost always owns a CFC.
Sources
Primary sources (accessed October 29, 2026)
- Public Law 119-21 (H.R. 1, 119th Congress), enacted July 4, 2025
- 26 U.S.C. § 951A, Net CFC tested income, as amended by Pub. L. 119-21 (2025)
- 26 U.S.C. § 951 and § 957, US shareholders and controlled foreign corporations
- 26 U.S.C. § 954, Subpart F income, de minimis and full inclusion rules, and the high-tax exception
- 26 U.S.C. § 956, Investment of earnings in US property
- 26 U.S.C. § 958, Direct, indirect and constructive ownership, including § 958(b)(1)
- 26 U.S.C. § 318, Constructive ownership of stock
- 26 U.S.C. § 959, Previously taxed earnings
- 26 U.S.C. § 986, Foreign currency gain or loss on previously taxed earnings
- 26 U.S.C. § 250 and § 960, Deduction and deemed-paid credit
- 26 U.S.C. § 962, Treas. Reg. § 1.962-1 and Treas. Reg. § 1.962-2, Election by individuals
- Treas. Reg. § 1.951A-2, including (c)(7), High-tax exclusion election and tested units
- 26 U.S.C. § 1, (j) and (h)(11), Individual rates and qualified dividends
- 26 U.S.C. § 11, Corporate tax rate
- 26 U.S.C. § 1248, Gain from sale of CFC stock
- 26 U.S.C. § 331, Gain or loss to shareholders in corporate liquidations
- Treas. Reg. § 1.1411-10, Net investment income tax and CFC earnings
- 26 U.S.C. § 6038 and § 6038B, Information reporting penalties
- 26 U.S.C. § 6038D, Form 8938 penalties
- 26 U.S.C. § 1297, Passive foreign investment companies, including the CFC overlap rule
- 26 U.S.C. § 6501(c)(8), Period of assessment
- 26 U.S.C. § 6013(g), Election to treat nonresident alien spouse as resident
- 26 U.S.C. § 7701(a)(4)–(5), Domestic and foreign entities
- Treas. Reg. § 301.7701-2 and § 301.7701-3, Entity classification, per se list, defaults, elections and deemed transactions
- 26 U.S.C. § 911(d)(2)(B) and (d)(6), Earned income where capital is a material factor; no credit on excluded income
- US Treasury, OFAC, Sanctions programs and country information
- US Treasury, Outbound Investment Security Program (31 CFR Part 850)
- Estonian Tax and Customs Board, Income and social taxes
- IRS, Instructions for Form 5471 (Rev. December 2025)
- IRS, About Form 8992
- IRS, Instructions for Form 926
- IRS, About Form 8858, About Form 8865 and About Form 8832
- IRS, Instructions for Form 5472
- IRS, Comparison of Form 8938 and FBAR requirements
- IRS, Instructions for Form 8938
- IRS, Publication 54 (Rev. December 2025)
- IRS, Rev. Proc. 2025-32, 2026 foreign earned income exclusion amount
- IRS, Delinquent international information return submission procedures
- IRS, Information for foreign financial institutions (last reviewed December 5, 2025)
- FinCEN, Report foreign bank and financial accounts (FBAR)
- FinCEN, Beneficial ownership information reporting, and final rule, 91 FR 52508 (August 14, 2026)
- US Social Security Administration, US–Portugal social security agreement
- US Treasury, 2016 US Model Income Tax Convention, Articles 4(4) and 5
- US Treasury, press release of January 5, 2026 on the side-by-side agreement
- OECD, Global Anti-Base Erosion Model Rules (Pillar Two)
- HMRC, International Manual INTM180050, HMRC view of Delaware LLCs in light of Anson
- HMRC, Revenue and Customs Brief 15 (2015)
- UK government, Consultation on reform to taxation of UK-resident members of LLCs and other reverse hybrids (June 10 to July 31, 2026), and Summary of responses (October 28, 2026)
- Anson v Commissioners for HMRC [2015] UKSC 44
- UK government, Corporation Tax rates and allowances
- UK, Corporation Tax Act 2009, section 14 (companies incorporated in the UK)
- Germany, Körperschaftsteuergesetz (KStG), §§ 1 and 23 (in German)
- Spain, Ley 27/2014 del Impuesto sobre Sociedades, Article 8 (in Spanish)
A note on method: the rules in this article were checked against the Internal Revenue Code and Treasury regulations as published by Cornell's Legal Information Institute, Public Law 119-21, IRS forms and instructions, and the official sources of the foreign tax systems named. Anna and Ben are fictional, and their figures are illustrations, not calculations for your company. Where only a secondary source was available, the text labels it; where no official source settles a question, the text says so. Paraphrases are ours, so check the cited text before you rely on it.