Key takeaways
- US self-employment tax follows you abroad no matter what — the FEIE doesn't touch it. The foreign earned income exclusion (up to $132,900 in 2026) wipes out regular income tax, but the IRS is explicit it doesn't reduce the 15.3% self-employment tax, and the foreign tax credit doesn't help either since it only offsets income tax.
- The only way out is a totalization agreement — and only 31 countries have one (as of September 2026). Romania is the newest, effective September 1, 2026. Covered under a partner country's system, a certificate of coverage exempts you from US self-employment tax; without an agreement (Mexico, Colombia, Thailand, UAE, among others), there is no way out.
- A digital nomad visa decides where you can live and work — not which social security system you belong to. Settling under a visa in a country with no agreement, or in a residence-rule country without registering locally, can leave your US return and your local status telling two different stories.
- The certificate of coverage has to be attached to your US return every single year you claim the exemption — not a one-time filing — with "Exempt, see attached statement" written on the self-employment tax line.
- Already paid US self-employment tax while you were covered abroad? It's often recoverable. Obtain the certificate, then file Form 1040-X — generally within 3 years of filing or 2 years of payment, whichever is later.
- The 15.3% rate itself splits into two parts. 12.4% for Social Security, on net earnings up to $184,500 in 2026, and 2.9% for Medicare with no earnings cap, plus an additional 0.9% above certain thresholds.
If you are a US citizen freelancing or running a one-person business from abroad, the foreign earned income exclusion can wipe out your US income tax — but not your US self-employment tax. That 15.3% Social Security and Medicare tax follows you to Lisbon, Mexico City or Bali unless one specific rule takes you out of it.
Most guides stop at "get a certificate of coverage." This one goes further: which popular destinations actually have an agreement with the United States, why the rule for self-employed people differs from country to country, what happens on a digital nomad visa, and exactly how to claim the exemption on your return.
Who this guide is for: US citizens and green card holders who are self-employed abroad — freelancers, contractors, consultants, creators and solo founders.
Our method: every rule below is checked against primary sources: the Social Security Administration's official agreement pages and operations manual, IRS guidance, and foreign government websites. Where the official sources leave a question open, we say so.
The 30-second answer
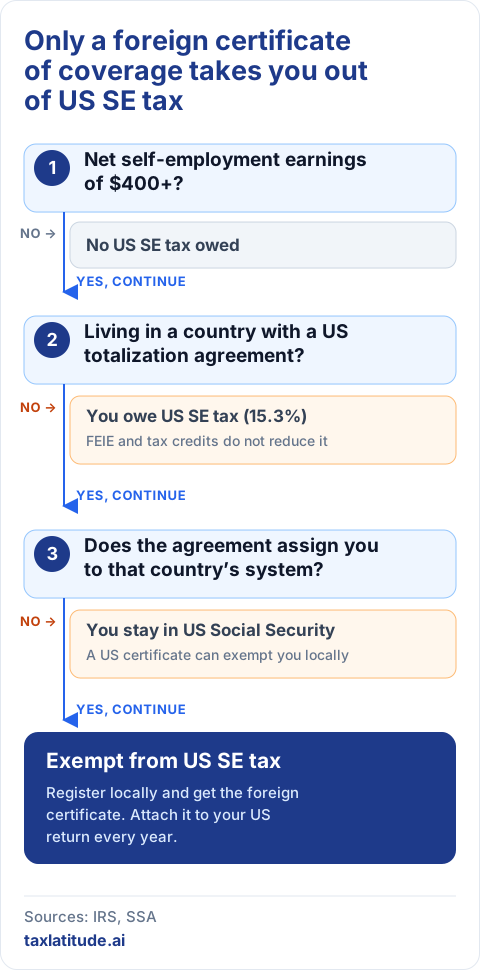
Three questions settle it. If your net self-employment earnings reach $400, you owe US self-employment tax wherever you live — unless a totalization agreement assigns you to another country's social security system and you can prove it with that country's certificate of coverage. Living abroad, claiming the foreign earned income exclusion or paying foreign income tax does not change this on its own.
Why doesn't the foreign earned income exclusion protect you?
The foreign earned income exclusion (FEIE) and US self-employment tax live in two different parts of the tax code. The FEIE reduces your income tax; self-employment tax is a Social Security and Medicare tax, and the IRS is explicit that the two don't mix. You owe self-employment tax if your net earnings from self-employment are at least $400, and you must count all of your self-employment income when figuring it, even the part you excluded under the FEIE (IRS, Self-employment tax for businesses abroad). The IRS's FEIE page says the same thing in one line: the excluded amount reduces your regular income tax but not your self-employment tax (IRS, Foreign earned income exclusion).
The foreign tax credit doesn't help either: it offsets US income tax with foreign income tax, not Social Security or Medicare tax.
The 2026 numbers
- FEIE: up to $132,900 per person for tax year 2026 (IRS).
- Social Security part of SE tax: 12.4%, on net earnings up to $184,500 in 2026 (SSA).
- Medicare part of SE tax: 2.9%, with no earnings cap, plus an additional 0.9% Medicare tax on earnings above certain thresholds.
| Component | Rate | Earnings it applies to |
|---|---|---|
| Social Security | 12.4% | Net earnings up to $184,500 |
| Medicare | 2.9% | No earnings cap |
| Additional Medicare tax | 0.9% | Earnings above certain thresholds |
A quick example
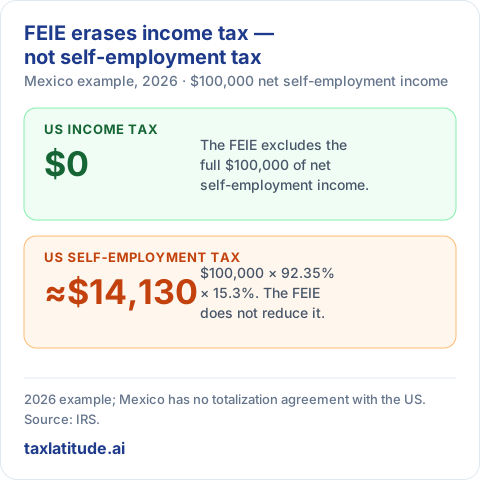
Take a US freelancer living in Mexico City in 2026 with $100,000 of net self-employment income, all from services performed in Mexico. Mexico has no totalization agreement with the United States.
- Income tax: the FEIE can exclude the full $100,000, so the US income tax on it can drop to zero.
- Self-employment tax: still due. Schedule SE applies the rate to 92.35% of net earnings, so roughly $100,000 × 92.35% × 15.3% ≈ $14,130 of US self-employment tax.
That $14,130 is the bill many first-year freelancers abroad don't see coming.
Freelancing in Mexico, Colombia, Thailand or the UAE? None of these countries has a totalization agreement with the US, so a $100,000 income year can mean roughly $14,130 of US self-employment tax even after the FEIE wipes out your income tax. Calculate your own self-employment tax bill →
How do totalization agreements treat the self-employed?
Under US law, Social Security covers self-employed US citizens even when they live and work outside the United States. Totalization agreements exist so that someone who would otherwise pay into two systems pays into only one (SSA, Totalization Agreements). The question is always which one — and the answer is not the same in every agreement.
The usual rule: where you live
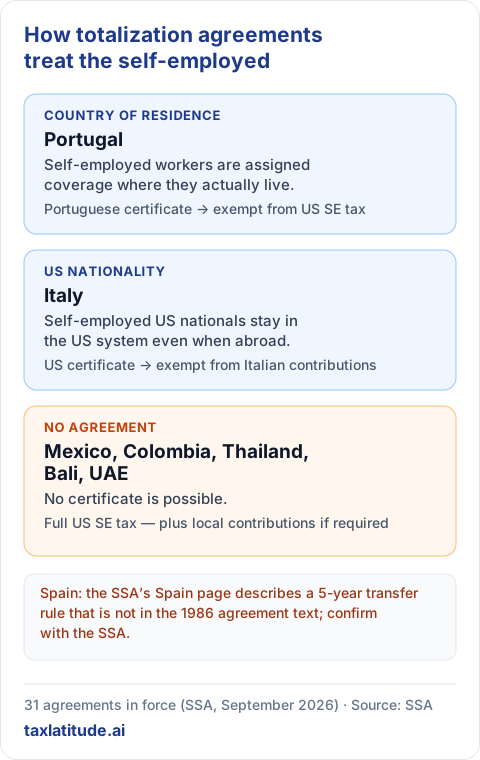
Most agreements assign self-employed people to the country where they reside. The SSA's page for Portugal is typical: self-employed workers who reside in Portugal are assigned Portuguese coverage, and those who reside in the United States are assigned US coverage (SSA, Portugal agreement). Under that rule, a US freelancer who has truly moved to Portugal pays Portuguese contributions and is exempt from US self-employment tax — once they can prove it.
Exception 1: a temporary move may keep you in the US system (Spain)
Some agreements may add a transfer rule. The SSA's page on the US–Spain agreement says that a person normally self-employed in one country who transfers their trade or business to the other for five years or fewer stays covered by the country they came from (SSA, Spain agreement). That rule does not appear in the text of the 1986 agreement, which the SSA lists as the one in force: Article 4 assigns the self-employed to their country of residence, and the five-year rule in Article 5 covers employees sent by a firm (SSA, agreement text). Ask the SSA for a certificate before relying on the transfer rule. That matters for digital nomads, as we'll see below.
Exception 2: US citizenship decides (Italy)
The US–Italy agreement turns the usual rule around. Self-employed US nationals who would otherwise be covered by both countries are covered only by the US system; Italian or dual US–Italian nationals working in Italy can generally choose (SSA, Italy agreement). A US-only citizen freelancing in Rome keeps paying US self-employment tax, and it is a US certificate that exempts them from Italian contributions — the opposite of what most generic guides suggest.
How many agreements are there?
Many guides still say 30. The SSA's operations manual, updated in September 2026, lists 31 agreements in force, the newest being Romania, effective September 1, 2026 (SSA POMS GN 01701.005). Some guides also claim Brazil's agreement is not in force; according to the SSA, it has been effective since October 1, 2018.
The takeaway: never assume the residence rule. Read your country's page on the SSA site before you plan around it.
Which destinations are popular for young Americans, country by country?
The table below covers destinations that come up most often among US freelancers and remote workers. Agreement status and effective dates come from the SSA's list of agreements in force (SSA POMS GN 01701.005). Where we have checked the SSA's country page for the self-employed rule, we say what it is; where we haven't, we tell you to check rather than guess.
| Destination | US agreement in force? | What it means for you |
|---|---|---|
| Portugal | Yes, since Aug. 1, 1989 | Country of residence. Living in Portugal: pay Portuguese contributions, get a Portuguese certificate, exempt from US SE tax |
| Spain | Yes, since Apr. 1, 1988 | Country of residence under the 1986 agreement; the SSA's Spain page also describes a 5-year transfer rule. Moved for good: Spanish system. Temporary move: ask the SSA whether you can stay in the US system |
| Italy | Yes, since Nov. 1, 1978 | US nationals stay in the US system. A US-only citizen keeps paying US SE tax; a US certificate exempts you in Italy |
| Germany | Yes, since Dec. 1, 1979 | Check the SSA's Germany page. Agreement available; confirm which system covers you |
| France | Yes, since July 1, 1988 | Check the SSA's France page. Agreement available; confirm which system covers you |
| Netherlands | Yes, since Nov. 1, 1990 | Check the SSA's Netherlands page. Agreement available; confirm which system covers you |
| United Kingdom | Yes, coverage rules since Jan. 1, 1985 | Check the SSA's UK page. Agreement available; confirm which system covers you |
| Greece | Yes, since Sept. 1, 1994 | Check the SSA's Greece page. Agreement available; confirm which system covers you |
| Romania | Yes, since Sept. 1, 2026 | Check the SSA's Romania page. Brand-new agreement; earlier years are not covered |
| Brazil | Yes, since Oct. 1, 2018 | Check the SSA's Brazil page. Agreement available despite claims to the contrary |
| Japan | Yes, since Oct. 1, 2005 | Check the SSA's Japan page. Agreement available; confirm which system covers you |
| South Korea | Yes, since Apr. 1, 2001 | Check the SSA's South Korea page. Agreement available; confirm which system covers you |
| Mexico | No | US SE tax applies in full; Mexican contributions may apply too |
| Colombia | No | US SE tax applies in full |
| Costa Rica | No | US SE tax applies in full |
| Argentina | No | US SE tax applies in full |
| Thailand | No | US SE tax applies in full |
| Indonesia (Bali) | No | US SE tax applies in full |
| Vietnam | No | US SE tax applies in full |
| United Arab Emirates | No | US SE tax applies in full |
The pattern is striking: many of the destinations most associated with digital nomads — Mexico, Colombia, Thailand, Bali, the UAE — have no agreement at all. In those countries, a self-employed US citizen owes US self-employment tax no matter what, and if local law also requires contributions, they pay twice with no treaty relief. Every country not on the SSA's list is in the same position.
Picked your destination for the lifestyle, not the tax treaty? Many of the most popular digital nomad destinations have no US totalization agreement at all, which means full US self-employment tax with no way out. Check if your country has an agreement →
What is the digital nomad visa trap?
A digital nomad visa is an immigration permit. It decides whether you may live and work remotely in a country; it does not, by itself, decide which social security system you belong to. Three situations come up again and again.
1. Nomad visa in a country with no agreement
In Mexico, Colombia, Thailand or the UAE, your visa changes nothing on the US side. With no agreement, there is no foreign certificate of coverage to obtain, so US self-employment tax applies to your net earnings in full — on top of whatever the local system requires.
2. Nomad visa in a residence-rule country, without registering locally
Where an agreement assigns residents to the local system, settling there and skipping local registration is the worst of both worlds. You have no foreign certificate to attach to your US return, so the US exemption isn't available, and you may be out of compliance with local rules.
3. Spain: the visa asks the question for you
Spain makes the issue explicit. According to its official consular guidance, self-employed applicants for the teleworker visa must show registration in RETA, the Spanish scheme for the self-employed. The exception: if the applicant's home country has a social security agreement with Spain, its authorities can issue a certificate of applicable legislation providing temporary coverage in Spain — and the consulate warns that only some countries issue that certificate for teleworkers (Spanish Ministry of Foreign Affairs, consulate guidance).
For a US citizen, the possible hook is the transfer rule described on the SSA's Spain page: a self-employed person who moves their business to Spain for five years or fewer stays in the US system (SSA, Spain agreement) — a rule not found in the 1986 agreement text, as noted above. If the SSA certifies that, you keep paying US self-employment tax and skip RETA. If it doesn't, or once you have really settled in Spain, the residence rule points you to RETA — and a Spanish certificate then exempts you from US self-employment tax. No SSA guidance is written specifically for digital nomads, so request a certificate early and plan for either answer.
Rule of thumb: before you apply for any nomad visa, find out which social security system the agreement assigns you to, and make sure the visa paperwork and your US return tell the same story.
How to get a certificate of coverage and claim the exemption
Step 1: Confirm which country covers you
Open your destination's page on the SSA's agreements site and read the section on self-employment. That tells you whether you need a foreign certificate (you are assigned to the other country) or a US certificate (you stay in the US system and want to be exempt locally).
Step 2a: If the other country covers you, ask its social security agency
The certificate comes from the country whose system you pay into. For Portugal, for example, the SSA tells self-employed residents to write to the regional social security center where they are registered, giving their name, date and place of birth, citizenship, country of permanent residence, US and Portuguese social security numbers, the nature of their self-employment, the dates of the activity, and the name and address of their business in both countries (SSA, Portugal agreement). Other countries follow the same pattern, with their own agency and forms.
If the foreign country won't issue a certificate, the IRS says you should ask the SSA for a statement that your income is not covered by the US Social Security system (IRS).
Step 2b: If the US covers you, ask the SSA
Self-employed individuals can request a US certificate of coverage online through the SSA's form at opts.ssa.gov, or by mail or fax; no special form is required. The SSA recommends asking as early as possible, ideally before the work abroad begins. The exemption generally takes effect from the date you started working in the other country, but no earlier than the date the agreement took effect (SSA, Totalization Agreements).
Step 3: Claim the exemption on your US return
When a foreign certificate exempts you from US self-employment tax, the IRS asks you to:
- Attach a photocopy of the certificate (or the SSA statement) to your Form 1040 every year you are exempt.
- Write "Exempt, see attached statement" on the line for self-employment tax.
(IRS, Self-employment tax for businesses abroad). Keep the original with your records.
What if you've already paid twice, and how do you fix past years?
It is common to discover the problem a year or two late: you paid US self-employment tax and contributed to the local system for the same earnings. Whether you can fix it depends on where you were and when.
If you lived in a country with an agreement. Request the certificate of coverage now. The SSA notes that the exemption generally runs from the date you began working in the other country, but never earlier than the date the agreement took effect (SSA, Totalization Agreements). With the certificate in hand, you can file an amended return on Form 1040-X to remove the self-employment tax for the years it covers, attaching the certificate.
Mind the deadline. To claim a refund, you generally must file Form 1040-X within 3 years after the date you filed the original return, or within 2 years after the date you paid the tax, whichever is later. A return filed before the due date is treated as filed on the due date (IRS, Topic 308). Years beyond that window are usually lost.
Realized you paid self-employment tax twice in an earlier year? You generally have only 3 years from filing or 2 years from payment, whichever is later, to claim it back on Form 1040-X — miss that window and it's gone. See if you're still inside the deadline →
If the agreement assigns you to the US system (for example, a US national in Italy), the refund question runs the other way: it is the foreign contributions you would need to recover, under that country's procedures, using a US certificate of coverage.
If you lived in a country without an agreement — India, New Zealand, Georgia, the Philippines and Malaysia do not appear on the SSA's list, for example — there is nothing to fix on the US side: the self-employment tax was owed. The only relief is planning for the future, such as choosing a destination with an agreement or changing how your work is structured with professional advice.
Frequently asked questions
Does the foreign earned income exclusion reduce self-employment tax?
No. The IRS states that the FEIE reduces regular income tax but not self-employment tax, and that all self-employment income counts when figuring it, including the part you excluded.
How much self-employment income triggers US self-employment tax abroad?
Net earnings from self-employment of $400 or more, the same threshold as in the United States.
How many countries have a totalization agreement with the United States?
31 as of September 2026, according to the SSA's operations manual. Romania is the newest, effective September 1, 2026.
Does Mexico have a totalization agreement with the US?
No agreement with Mexico appears on the SSA's list of agreements in force, so self-employed US citizens living in Mexico owe US self-employment tax in full.
I'm a US citizen freelancing in Italy. Which system do I pay into?
Under the US–Italy agreement, self-employed US nationals who would otherwise be covered by both countries are covered only by US Social Security. You keep paying US self-employment tax, and a US certificate of coverage is what exempts you from Italian contributions. Dual US–Italian nationals can generally choose.
Do I need to send my certificate of coverage to the IRS every year?
Yes. The IRS asks you to attach a photocopy to your Form 1040 for every year you claim the exemption, and to write "Exempt, see attached statement" on the self-employment tax line.
Can I get back US self-employment tax I paid in earlier years?
Often, if you were covered by a foreign system under an agreement: obtain the certificate, then file Form 1040-X within the refund deadline — generally 3 years from filing or 2 years from payment, whichever is later.
Check your own situation
The answer turns on details: your citizenship, where you are really resident, whether your move is temporary, and what the agreement for your country actually says. TaxLatitude answers from official texts, cites each source and lists what it could not confirm. For example:
"I'm a US citizen freelancing for US clients from Valencia on a digital nomad visa. Do I pay US self-employment tax, Spanish RETA contributions, or both?"
Methodology and primary sources
Every rule in this guide was checked against the following official sources in October 2026. Agreements and figures change; check for updates before relying on any rule.
Social Security Administration
- POMS GN 01701.005, International Social Security (Totalization) Agreements — list of agreements in force
- Totalization Agreements: overview, self-employment and certificates of coverage
- Agreement with Portugal
- Agreement with Spain
- Agreement with Italy
- Agreement with Spain: text of the 1986 agreement
- Status of totalization agreements
- Contribution and benefit base, 2026
Internal Revenue Service
- Self-employment tax for businesses abroad
- Foreign earned income exclusion
- Tax inflation adjustments for tax year 2026
- Topic 308, Amended returns
Foreign government
This guide is general information, not tax or legal advice. Social security coverage depends on your individual facts, and local rules in your country of residence can change the outcome. Consult a qualified cross-border tax professional before acting.