Key takeaways
- Under 26 U.S.C. § 6501, the IRS's normal three-year assessment window becomes six years if you omit more than 25% of your income or more than $5,000 of income from foreign assets, and there is no time limit at all for fraud or for failing to file.
- A willful failure to report a foreign account on an FBAR currently carries a penalty of up to $165,353 or 50% of the account balance per year, whichever is greater, under FinCEN's January 2025 inflation adjustment.
- For 2026, Americans can give $19,000 per recipient with no gift tax filing and pass $15 million per person free of federal estate tax, according to IRS Rev. Proc. 2025-32.
- Non-willful U.S. taxpayers with unreported foreign assets can come into compliance through the IRS Streamlined Domestic Offshore Procedures by filing three years of amended returns and six years of FBARs and paying a 5% penalty, or no penalty at all if they live abroad.
- In Germany, a complete voluntary self-disclosure filed before discovery removes criminal liability, but evasion above €25,000 per offense also requires a surcharge of 10%, 15%, or 20% depending on the amount, under § 398a of the German Fiscal Code.
- Several rules described below are in motion: Germany's Federal Constitutional Court heard challenges to the inheritance tax relief for business assets in October 2026 without yet ruling, the UK cuts the cash ISA limit for savers under 65 to £12,000 from April 6, 2027, and proposed changes to the IRS Voluntary Disclosure Practice announced in December 2025 have not been finalized.
What do tax authorities now see?
For a century, tax evasion ran on an information gap: the taxpayer knew, the government didn't. That gap has flipped. The government often knows before you do, and sometimes better than you do.
Foreign accounts are reported automatically. The OECD's Common Reporting Standard moved balances and income on 171 million accounts holding almost €13 trillion in 2024, exchanged among 116 jurisdictions (OECD Global Forum, December 2025), with 129 jurisdictions committed in total. For Americans, FATCA requires banks around the world to send the IRS the accounts of their "U.S. person" clients, wherever they live, as described on the IRS FATCA page. An account left behind in Geneva, Luxembourg, or
Still have an old foreign account nobody's ever reported? Under FATCA and the CRS, it's usually already a line in a file somewhere, not a secret — and once matched, the assessment window can run for years. Find out what fixing it actually involves →
Singapore is no longer a secret, just a line in a file that may not have been matched yet.Domestic income is reported by third parties: employers, banks, and brokers, through Forms W-2 and 1099 in the United States, and through prefilled returns in Spain, Italy, the Netherlands, and the Nordic countries (see Spain's 2026 Tax Control Plan, which relies on the Renta Web draft return, and Italy's dichiarazione precompilata). Platforms have been pulled in: since 2023, the EU's DAC7 directive has required Airbnb, Vinted, Uber, and their peers to report their users' income, and the United States has its Form 1099-K. Crypto, the supposed last refuge, is next: Form 1099-DA for U.S. transactions starting in 2025, the DAC8 directive in Europe starting in 2026, and the OECD's global framework with first exchanges planned for 2027. The blockchain is, on top of that, a permanent public ledger, which makes it one of the worst places to hide anything.
Then there are the tools the taxpayer never sees. Britain's tax authority, HMRC, has run a system called Connect, dating to a 2008 investment, that cross-references data points across land records, vehicle registrations, bank accounts, online platforms, and foreign data to support investigations and has helped raise about £4.6 billion in 2024-25 across more than half a million cases (Pinsent Masons). Spain's tax agency uses big-data analysis to spot fake nonresidents; its 2026 Tax Control Plan names the simulation of tax residence outside Spain as a priority. Whistleblowers get paid: between 15% and 30% of the amounts collected in the United States when more than $2 million is at stake, under 26 U.S.C. § 7623(b) and the IRS Whistleblower Office, and HMRC's own reward scheme, modeled on the American one, launched on November 26, 2025, paying 15% to 30% of tax collected (excluding penalties and interest) where a tip leads to the recovery of at least £1.5 million; anonymous reports do not qualify. Governments buy stolen files: Germany's foreign intelligence service paid more than €4 million for stolen Liechtenstein bank data in 2006, an affair that became public in February 2008 (CNBC). And a decade of leaks, from the Panama Papers to the Pandora Papers, has shown that no law firm and no trust company is safe from a disgruntled employee with a hard drive. The weak link in your secret isn't you. It's everyone who shares it.
Why is time not on your side?
Rigor requires a concession. Audit rates are low overall, under 1% of individual returns in the United States, though IRS compliance-presence figures show rates of 3.9% for incomes of $5 million to $10 million and 6.6% above $10 million. The IRS's resources rise and fall with congressional majorities, as shown by the funding approved in 2022 and then largely clawed back, and by the 2025 staffing cuts. According to TIGTA's September 2026 report on Inflation Reduction Act spending, about $79.4 billion was originally provided and roughly $53.5 billion was rescinded across four laws, and TIGTA's May 2025 workforce snapshot counted more than 11,000 separations by March 2025. Anyone who tells you every tax cheat will be caught by tomorrow morning is lying to you.
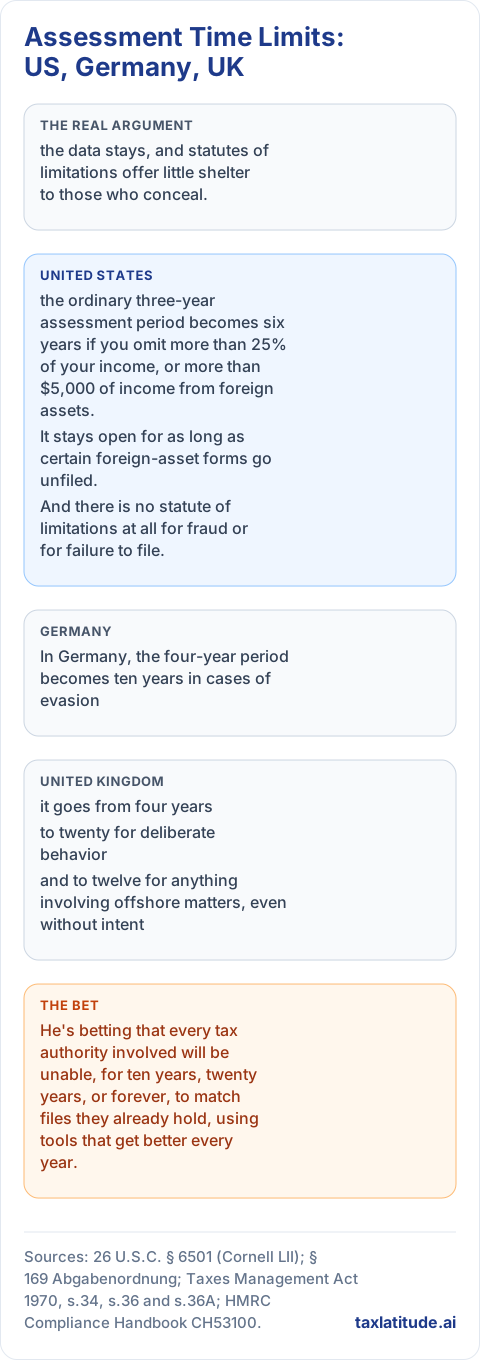
The real argument lies elsewhere: the data stays, and statutes of limitations offer little shelter to those who conceal. In the United States, the ordinary three-year assessment period becomes six years if you omit more than 25% of your income, or more than $5,000 of income from foreign assets. It stays open for as long as certain foreign-asset forms go unfiled. And there is no statute of limitations at all for fraud or for failure to file. All of this is set out in 26 U.S.C. § 6501, subsections (a), (c)(1), (c)(3), (c)(8), and (e). In Germany, the four-year period becomes ten years in cases of evasion, under § 169(2) of the Fiscal Code. In the United Kingdom, it goes from four years (Taxes Management Act 1970, s.34) to twenty for deliberate behavior (s.36), and to twelve for anything involving offshore matters, even without intent (s.36A; see also HMRC Compliance Handbook CH53100). So the tax cheat isn't betting against this year's audit. He's betting that every tax authority involved will be unable, for ten years, twenty years, or forever, to match files they already hold, using tools that get better every year. It's a bet you rarely lose right away and almost always lose in the end.
What is the price of losing?
In the United States, the civil fraud penalty is 75% of the tax underpaid, under 26 U.S.C. § 6663. Willful failure to report a foreign account (FBAR) is penalized, per year, at the greater of two amounts: an inflation-adjusted figure just above $165,000, or half the account balance, so the penalty can exceed the account itself. The current figure is $165,353 under FinCEN's January 2025 inflation adjustment; the 2026 adjustment was cancelled by an April 2026 OMB memorandum, so the 2025 amounts still apply. TaxLatitude's FBAR guide for Americans abroad covers the filing mechanics. For non-willful violations, the Supreme Court limited the damage in 2023 in Bittner v. United States: the roughly $10,000 statutory non-willful penalty — $16,536 as inflation-adjusted under FinCEN's January 2025 adjustment — applies per report, not per account. On the criminal side, tax evasion carries up to five years in prison per count, under 26 U.S.C. § 7201.
In Germany, tax evasion is punishable by five years in prison, ten in serious cases, under § 370 of the Fiscal Code, and case law since a 2008 Federal Court of Justice ruling (1 StR 416/08, December 2, 2008) has progressively established that above roughly €1 million evaded, actual prison time, not a suspended sentence, is the norm. Evaded amounts also bear interest at 6% a year, at the half-percent-per-month rate set by § 238 of the Fiscal Code. In the United Kingdom, penalties run to 100% of the tax for deliberate concealment (HMRC factsheet CC/FS7a) and up to 200% for uncorrected offshore assets (Finance (No. 2) Act 2017, Schedule 18, and the offshore categories of Finance Act 2007, Schedule 24), and HMRC publishes the names of deliberate defaulters. In Spain, the criminal offense, triggered above €120,000 evaded per tax per year, carries one to five years in prison and a fine of up to six times the amount, rising to two to six years in aggravated cases, notably the use of shell structures or tax havens, under Articles 305 and 305 bis of the Spanish Criminal Code.
Examples abound, and what they have in common is that they struck people who could afford the best advice. Uli Hoeneß, president of soccer club Bayern Munich, was sentenced in 2014 to three and a half years in prison for €28.5 million in tax evaded through a Swiss account; his voluntary disclosure, filed in a rush, was ruled incomplete. Klaus Zumwinkel, chief executive of Deutsche Post, lost his job overnight in 2008 and got a two-year suspended sentence and a €1 million fine over a Liechtenstein foundation. Boris Becker was given a two-year suspended sentence in 2002 for claiming to be a resident of Monaco while living in Munich. Paul Manafort was convicted in 2018 of tax fraud and failure to report foreign accounts. Texas billionaire Robert Brockman, indicted in 2020 for concealing some $2 billion in income, died before trial; in December 2025 his estate agreed to pay $750 million to settle with the IRS. In Spain, the Supreme Court upheld Lionel Messi's 21-month prison sentence and multimillion-euro fine in 2017, before the prison term was replaced by a further fine, while Cristiano Ronaldo and Shakira accepted suspended prison sentences and multimillion-euro fines in deals with prosecutors.
What cost does no penalty schedule mention?
A hidden dollar is not worth a dollar. It can't fund a home purchase, a business, or a gift without raising the question of where it came from. Banks, bound by anti-money-laundering rules, close suspicious accounts or demand documentation, and in the European Union as in the United States, using the proceeds of tax fraud can constitute a separate money laundering offense; in the United States, tax evasion is not itself a predicate offense for money laundering, so prosecutors have had to reach some tax schemes through wire fraud instead, a practice the Justice Department limits as a matter of policy (American Bar Association, Tax Times). Hidden money is expensive in intermediaries, who know you won't be filing a complaint.
It leaves you exposed to anyone who knows the secret: an ex-spouse in a divorce, a business partner in a dispute, a fired employee, a dishonest adviser. It poisons estates, leaving children a choice between coming clean at great cost or taking over the fraud themselves, with the assessment clock still running. And it costs peace of mind, which appears on no spreadsheet but which every lawyer who has handled disclosures describes the same way: the relief of clients who hadn't slept well in twenty years.
Where does the line fall?
None of this condemns the pursuit of the lowest possible tax. The law explicitly protects it. Judge Learned Hand put it in 1934 in a line that became a classic: anyone may arrange his affairs so that his taxes shall be as low as possible, and no one is bound to choose the pattern that best pays the Treasury. The line comes from the Second Circuit's opinion in Helvering v. Gregory, 69 F.2d 809 (2d Cir. 1934), affirmed by the Supreme Court in Gregory v. Helvering, 293 U.S. 465 (1935). The House of Lords said the same thing when it decided IRC v Duke of Westminster on May 7, 1935 ([1935] UKHL 4, reported at [1936] AC 1), and most European courts recognize the taxpayer's right to choose the least-taxed route.
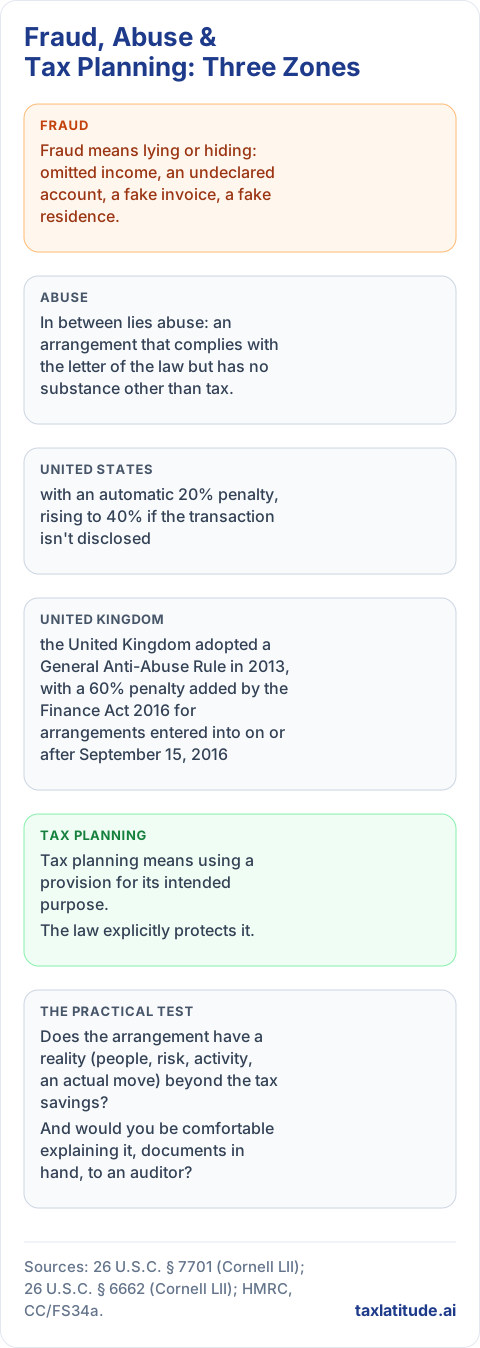
The line has three zones. Fraud means lying or hiding: omitted income, an undeclared account, a fake invoice, a fake residence. Tax planning means using a provision for its intended purpose. In between lies abuse: an arrangement that complies with the letter of the law but has no substance other than tax. The United States codified the economic substance doctrine in 2010 (26 U.S.C. § 7701(o); see IRS Notice 2010-62), with an automatic 20% penalty, rising to 40% if the transaction isn't disclosed, under 26 U.S.C. § 6662(b)(6) and (i). Germany has long disregarded the "abuse of legal structuring options," under § 42 of the Fiscal Code, the United Kingdom adopted a General Anti-Abuse Rule in 2013, with a 60% penalty added by the Finance Act 2016 for arrangements entered into on or after September 15, 2016 (HMRC factsheet CC/FS34a), and Italy codified abuse of law in 2015, in Legislative Decree 128/2015, which inserted Article 10-bis into the Taxpayers' Statute. The EU has its own general clause, in Article 6 of the Anti-Tax Avoidance Directive (EU) 2016/1164, and its Court of Justice has set aside "wholly artificial arrangements" since its 2006 Cadbury Schweppes ruling (Case C-196/04).
The practical test comes down to two questions. Does the arrangement have a reality (people, risk, activity, an actual move) beyond the tax savings? And would you be comfortable explaining it, documents in hand, to an auditor? If the strategy only works as long as nobody looks at it, it isn't tax planning.
What does the law offer Americans?
The Internal Revenue Code is public policy written as incentives, and Congress wants you to use them.
Retirement savings first. A 401(k) lets you take roughly $24,500 a year off your taxable income, more after age 50, often with an employer match. IRAs add a few thousand dollars ($7,500 for 2026, plus a $1,100 catch-up, per the same IRS release), and the Roth version flips the logic: no deduction going in, but growth and withdrawals that are tax-free for good. The health savings account (HSA) is the only triple-advantaged vehicle: deductible contributions, tax-free growth, and tax-free withdrawals for medical expenses; 2026 contribution limits are set in Rev. Proc. 2025-19. 529 plans do much the same for education.
Then investing. Gains on securities held more than a year are taxed at 0%, 15%, or 20% depending on income (IRS Topic 409), against ordinary rates topping out at 37% (IR-2025-103). Capital losses offset capital gains, and up to $3,000 a year of ordinary income (IRS Topic 409), subject to the wash sale rule barring repurchase of the same security within 30 days (26 U.S.C. § 1091). Municipal bond interest is exempt from federal tax (26 U.S.C. § 103). Giving appreciated stock rather than cash to charity lets you deduct its value without ever paying tax on the gain (26 U.S.C. § 170, subject to a 30%-of-income limit for such gifts to public charities). At death, assets get a step-up in basis to their value on that date, wiping out the built-in gain (26 U.S.C. § 1014). The One Big Beautiful Bill Act, signed in July 2025 (Public Law 119-21), permanently set the federal estate tax exemption at $15 million per person starting in 2026 (26 U.S.C. § 2010, indexed for inflation after 2026; confirmed for 2026 in IRS, What's new — Estate and gift tax), and anyone can give roughly $19,000 a year per recipient with no filing at all ($19,000 for 2026 per Rev. Proc. 2025-32). IRS pages now also refer to this law as the "Working Families Tax Cuts."
For business owners, the 20% deduction on pass-through business income was made permanent by that same 2025 law (26 U.S.C. § 199A), and the qualified small business stock rules (Section 1202) can exclude millions of dollars of gain on a sale, subject to holding periods (for stock acquired after July 4, 2025, 50%, 75%, or 100% of the gain after three, four, or five years, up to $15 million). Real estate investors have depreciation and tax deferral through like-kind exchanges (Section 1031).
Two points need making. Moving to a state with no income tax, Florida or Texas, is legal provided you actually move: New York and California audit fake departures closely, down to cell phone records and veterinary bills. New York's Nonresident Audit Guidelines examine home, business ties, time, items "near and dear," and family. TaxLatitude's guide to state taxes after moving abroad covers what it takes to actually clear a state's domicile. And leaving the country isn't enough, since the United States taxes its citizens wherever they live. Expats do have the Foreign Earned Income Exclusion, on the order of $130,000, the foreign tax credit, and tax treaties. In a high-tax European country, the residual U.S. tax is often zero, as long as you file.
Living in a high-tax European country and worried about double taxation? Between the FEIE, the foreign tax credit and the treaty, the residual US bill is often zero — but only if you actually file every year. Check your own numbers →
What does the law offer Europeans?
Europe has 27 systems and then some. The logic is similar everywhere: retirement, savings wrappers, holding periods, wealth transfer, business.
In Germany, the allowance on investment income is €1,000 per person (§ 20(9) of the Income Tax Act; €2,000 for jointly assessed couples), occupational pension contributions are mostly tax-free up front rather than deductible, while Rürup contracts are specifically deductible (Federal Ministry of Finance, Basisrente), and holding periods are rewarded: the gain on rental property held more than ten years is tax-free, as is the gain on physical gold or crypto held more than a year (§ 23 of the Income Tax Act; for crypto, the Ministry of Finance letter of March 6, 2025). Each parent can pass €400,000 to each child every ten years (§ 16 of the Inheritance and Gift Tax Act, with the ten-year aggregation in § 14), and family businesses get an 85% or even 100% exemption, subject to keeping the business and its jobs going (§§ 13a and 13b of the Inheritance and Gift Tax Act).
In the United Kingdom, the ISA shelters £20,000 of annual contributions from all tax (GOV.UK, Individual Savings Accounts), pension contributions are deductible up to £60,000 a year (GOV.UK, pension annual allowance), the EIS and SEIS programs offer 30% and 50% income tax relief for investing in young companies (GOV.UK, venture capital schemes), charitable giving gets Gift Aid, and gifts fall out of the estate after seven years (GOV.UK, Inheritance Tax rules on gifts).
In Italy, individual savings plans (PIRs) exempt gains after a five-year holding period (Agenzia delle Entrate, Circular 19/2021; Law 232/2016), pension fund contributions are deductible (COVIP), and inheritance tax for direct descendants is among the lowest in Europe: 4% above €1 million per heir, with favorable treatment for business succession (Agenzia delle Entrate, inheritance tax rates and allowances; Circular 3/E of April 16, 2025 on the 2024 reform, which left the rates unchanged). In Spain, family businesses pass with a 95% reduction (Law 29/1987 on Inheritance and Gift Tax, Article 20.2.c), several regions, Madrid among them, almost entirely exempt inheritances between close relatives (Comunidad de Madrid, 99% relief for spouses, descendants, and ascendants), and executives arriving from abroad can elect a flat 24% rate for six years (Agencia Tributaria, special regime for posted workers, covering the year of arrival and the five following years; the 24% rate applies up to €600,000, per the Agencia Tributaria IRPF manual). The Netherlands offers employees recruited from abroad a partial exemption on their pay, the "30% ruling," which falls to 27% on January 1, 2027 for most new and post-2024 arrivals (Netherlands government), and, like Belgium, deductions or credits for retirement savings.
And you can leave: Italy's flat tax (Agenzia delle Entrate, option for new residents; raised to €300,000 a year for those moving from 2026 by Law 199/2025), Switzerland's lump-sum taxation, the Greek or Emirati regimes. It's legal if it's real. Tax residence turns on where your home is, where you spend your time, and where your economic interests are centered, not on a mailbox address. That was the issue in Boris Becker's conviction and in Spain's prosecution of Shakira (AP reported prosecutors' case that she spent more than half of each year in Spain). TaxLatitude's tax residency tool walks through how that determination gets made. Several countries, including Germany (§ 6 of the Foreign Tax Act), Spain (Article 95 bis of the Personal Income Tax Law), and the Netherlands, impose an exit tax on unrealized gains in significant shareholdings.
What caveat does rigor demand?
It would be dishonest to conclude that everyone "always" has a solution of the same size. The legal menu is unevenly stocked. A salaried employee with no assets has retirement savings, a few wrappers, and some tax credits: real savings, from a few hundred to a few thousand dollars or euros a year, but not a transformation. Most of the powerful provisions involve capital, business ownership, and wealth transfer. That is a legitimate political debate, one this article doesn't settle. But it changes nothing in the individual calculation: for the employee, whose income is reported by third parties, fraud is nearly impossible; for the owner of capital, it's pointless, since the law already offers something better, without the risk.
What if you've already hidden something?
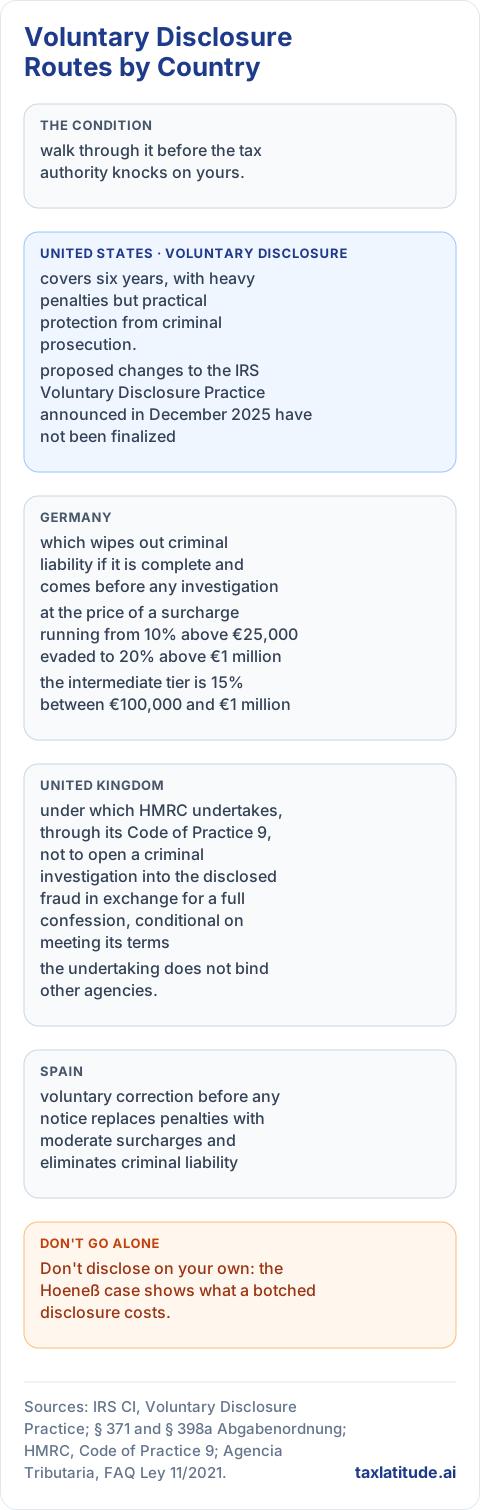
Almost every country leaves a door open, on one cardinal condition: walk through it before the tax authority knocks on yours.
In the United States, the Streamlined Filing Compliance Procedures are for taxpayers whose failure was non-willful: three years of amended returns, six years of FBARs, and a flat penalty of 5% of foreign assets for U.S. residents (IRS, U.S. taxpayers residing in the United States), zero for those living abroad (IRS, U.S. taxpayers residing outside the United States). It's the natural route for "accidental Americans" and good-faith expats. For willful cases, the
Realized you should have reported a foreign account years ago? The Streamlined Filing Compliance Procedures cover non-willful cases with a 5% penalty — or zero if you live abroad — but only before the IRS finds it first. See whether streamlined fits your situation →
IRS Voluntary Disclosure Practice covers six years, with heavy penalties but practical protection from criminal prosecution.Germany has voluntary self-disclosure, which wipes out criminal liability if it is complete and comes before any investigation (§ 371 of the Fiscal Code), at the price of a surcharge running from 10% above €25,000 evaded to 20% above €1 million (§ 398a of the Fiscal Code; the intermediate tier is 15% between €100,000 and €1 million). The United Kingdom has its Worldwide Disclosure Facility for offshore assets and, for outright fraud, the Contractual Disclosure Facility, under which HMRC undertakes, through its Code of Practice 9, not to open a criminal investigation into the disclosed fraud in exchange for a full confession, conditional on meeting its terms (HMRC Code of Practice 9); the undertaking does not bind other agencies. In Spain, voluntary correction before any notice replaces penalties with moderate surcharges and eliminates criminal liability (Agencia Tributaria FAQ on Law 11/2021, on the surcharges of Article 27 of the General Tax Law; Article 305.4 of the Criminal Code). Italy's ravvedimento operoso, or "active repentance," reduces penalties the faster you correct.
Two pieces of practical advice. Don't disclose on your own: the Hoeneß case shows what a botched disclosure costs. And in the United States, start with a lawyer rather than an accountant, because accountant-client privilege doesn't hold up in criminal matters (26 U.S.C. § 7525 limits the tax practitioner privilege to noncriminal tax matters).
Should you ask instead of guess?
One last, underused tool: tax authorities answer questions. The private letter ruling in the United States, clearances in Britain, the binding ruling in Germany, the interpello in Italy, the binding consultation in Spain, and Dutch rulings all let you get a position you can rely on before you do the deal. A strategy approved up front beats a brilliant strategy defended after the fact. Failing that, document: the non-tax reasons for your choices, the proof of your residence, the source of your funds. In an audit, the good-faith taxpayer with a paper trail and the concealer do not have the same experience, and the penalty schedules, from zero to 200%, measure exactly that difference (see the UK's Finance Act 2007, Schedule 24).
What is the final math?
Hide-and-seek assumed a playing field with dark corners. They have been lit up one by one: foreign accounts, platforms, crypto, and, soon, real estate. What remains hidden today is hidden by a processing backlog, not a secret, with assessment periods running from ten years to forever.
On the other side, legal tax planning has known returns, guaranteed by law, usable in broad daylight, and passed on without shame. The rational taxpayer doesn't need to be virtuous to choose honesty, only able to count. The one who is virtuous too sleeps better, and that has a price as well.
Frequently asked questions
Will the IRS find out about my foreign bank account?
Very likely: under FATCA, banks around the world report the accounts of "U.S. person" clients directly to the IRS, and the Common Reporting Standard exchanges data on 171 million accounts a year among other countries. An unreported account is usually a line in a file waiting to be matched, not a secret.
How far back can the IRS go if I hid income?
Three years normally, six years if you omitted more than 25% of your income or more than $5,000 of foreign-asset income, and indefinitely for fraud or unfiled returns, under 26 U.S.C. § 6501. The window also stays open while required foreign-asset information returns remain unfiled.
What is the penalty for not filing an FBAR?
For a willful failure, up to $165,353 or 50% of the account balance per year, whichever is greater; for a non-willful failure, a capped penalty that, after the Supreme Court's 2023 Bittner decision, applies once per report rather than once per account. The inflation-adjusted non-willful maximum currently in force is $16,536.
Does a voluntary self-disclosure in Germany protect me from prosecution?
Only if it is complete, covers all years of the tax in question, and is filed before the authorities discover the evasion; above €25,000 per offense you must also pay the evaded tax plus a surcharge of 10%, 15%, or 20%. Uli Hoeneß's disclosure was ruled incomplete, and he went to prison.
Is moving to a low-tax country legal tax avoidance?
Yes, if the move is real: residence turns on where your home is, where you spend your time, and where your economic interests are centered. Americans remain taxable as citizens wherever they live, and Germany, Spain, and the Netherlands can tax unrealized gains on significant shareholdings when you leave.
What's the difference between tax avoidance and tax evasion?
Evasion means lying or hiding, such as omitted income or an undeclared account, and is a crime; planning means using a provision for its intended purpose. Arrangements in between that have no substance beyond tax can be struck down under anti-abuse rules like the U.S. economic substance doctrine, which carries a 20% penalty, or 40% if undisclosed, and the UK's General Anti-Abuse Rule, with its 60% penalty.
When should you hire a professional?
The choice between concealment, planning, and disclosure turns on facts, deadlines, and criminal exposure that general reading cannot assess, and a misstep, such as an incomplete disclosure or an arrangement that lacks substance, can cost more than the tax itself.
- Undeclared foreign account or asset. Whether a failure counts as willful or non-willful decides between a 5% streamlined penalty and criminal exposure, and that judgment should be made by counsel before anything is filed.
- Arrangement near the abuse line. Whether a structure has enough substance to survive the economic substance doctrine, the UK GAAR, or § 42 of the German Fiscal Code is a fact-specific legal question with penalties of 20% to 60% attached.
- Using retirement, capital gains, and estate provisions. Business owners and investors face holding periods, income limits, and payroll conditions, such as the five-year Section 1202 holding period or Germany's job-retention test for business relief, that are easy to break by accident.
- Moving countries or changing tax residence. A new residence has to hold up under audit on home, time, and economic ties, and may trigger an exit tax on the way out.
- Inheriting an estate with an undisclosed asset. Heirs take over the assessment exposure, and the decision to correct the record has deadlines and consequences in every country involved.
- Wanting certainty before a transaction. Drafting a private letter ruling request, a German binding ruling, an Italian interpello, or a Spanish binding consultation so that the answer actually covers your facts requires technical skill.
Use a tax attorney for disclosure and anything with criminal exposure, since only the attorney-client privilege reliably protects those conversations; a cross-border tax adviser for planning, residence changes, and estates spanning several countries; and an accountant for routine filing once the strategy is settled.
Sources
All sources accessed October 16, 2026. Page dates are given only where the page showed one; otherwise the cell says so.
| Source | URL | Used for | Page date |
|---|---|---|---|
| OECD Global Forum, "International community meets in New Delhi to reflect on latest advances in global tax transparency" | https://www.oecd.org/en/networks/global-forum-tax-transparency/news-events/2025/international-community-meets-in-new-delhi-to-reflect-on-latest-advances-in-global-tax-transparency.html | CRS exchange volumes and jurisdictions | Not shown (plenary opened December 2, 2025) |
| IRS, Foreign Account Tax Compliance Act (FATCA) | https://www.irs.gov/businesses/corporations/foreign-account-tax-compliance-act-fatca | FATCA bank reporting | Reviewed September 24, 2026 |
| Spain, Resolution of March 11, 2026, Plan Anual de Control Tributario y Aduanero 2026 (BOE) | https://www.boe.es/diario_boe/txt.php?id=BOE-A-2026-5843 | Spanish prefilled returns and fake-residence checks | March 12, 2026 |
| Agenzia delle Entrate, L'accesso alla dichiarazione precompilata | https://www.agenziaentrate.gov.it/portale/l-accesso-alla-dichiarazione-precompilata-2026 | Italian prefilled returns | Not shown (2026 edition) |
| Council Directive (EU) 2021/514 (DAC7) | https://eur-lex.europa.eu/legal-content/EN/TXT/HTML/?uri=CELEX:32021L0514 | Platform reporting from 2023 | March 22, 2021 |
| IRS, IR-2025-107, FAQs on Form 1099-K threshold | https://irs.gov/newsroom/irs-issues-faqs-on-form-1099-k-threshold-under-the-one-big-beautiful-bill-dollar-limit-reverts-to-20000 | Form 1099-K | October 23, 2025 |
| IRS, FS-2024-23, Final regulations on broker reporting of digital assets | https://www.irs.gov/newsroom/final-regulations-and-related-IRS-guidance-for-reporting-by-brokers-on-sales-and-exchanges-of-digital-assets | Form 1099-DA from 2025 | Updated November 7, 2025 |
| European Commission, DAC8 | https://taxation-customs.ec.europa.eu/taxation/tax-transparency-cooperation/administrative-co-operation-and-mutual-assistance/directive-administrative-cooperation-dac/dac8_en | EU crypto reporting from 2026 | Not shown |
| OECD, Jurisdictions committed to implement the Crypto-Asset Reporting Framework | https://web-archive-storage.oecd.org/aemint-web-archive-prod/web-archive/c8/c84b4af3884e1acd4f5adfdeac958eb0098d421347c25e756fbc963a39135ab9.pdf | CARF first exchanges in 2027 | June 17, 2025 |
| Pinsent Masons Out-Law, "HMRC finds value in 'big data' after bringing in extra £4.6billion" | https://pinsentmasons.com/out-law/news/hmrc-big-data-tax-revenue-boost-4-6-billion | HMRC Connect (secondary) | Not shown |
| 26 U.S.C. § 7623 (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/7623 | IRS whistleblower awards | Not shown |
| IRS, Whistleblower Office at a glance | https://www.irs.gov/uac/whistleblower-office-at-a-glance | IRS whistleblower awards | Reviewed February 28, 2026 |
| HMRC, Reporting serious tax avoidance or evasion | https://www.gov.uk/guidance/reporting-serious-tax-avoidance-or-evasion | UK whistleblower reward scheme | November 26, 2025 |
| CNBC, Europe tax evasion probe going global | https://www.cnbc.com/2008/02/27/europe-tax-evasion-probe-going-global.html | Germany's purchase of Liechtenstein data (secondary) | February 27, 2008 |
| ICIJ, The Panama Papers | https://www.icij.org/investigations/panama-papers/ | Offshore leaks | April 3, 2016 |
| ICIJ, Pandora Papers | https://www.icij.org/investigations/pandora-papers/ | Offshore leaks | October 3, 2021 |
| IRS, Publication 55B, Data Book FY2025 | https://www.irs.gov/pub/irs-pdf/p55b.pdf | Audit coverage | Not shown (released April 2026) |
| IRS, Compliance presence | https://www.irs.gov/node/13654 | Audit rates by income level | Reviewed June 5, 2026 |
| TIGTA, Snapshot: The IRS's Inflation Reduction Act Spending Through March 31, 2026 (2026-IE-R014) | https://content.govdelivery.com/accounts/USTREASTIGTA/bulletins/4284f24 | 2022 IRS funding and rescissions | September 1, 2026 |
| TIGTA, Snapshot Report: IRS Workforce Reductions as of March 2025 (2025-IE-R017) | https://www.oversight.gov/sites/default/files/documents/reports/2025-05/2025ier017fr.pdf | 2025 IRS staffing cuts | May 2, 2025 |
| 26 U.S.C. § 6501 (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/6501 | U.S. assessment periods | Not shown |
| § 169 Abgabenordnung (lxgesetze.de mirror) | https://lxgesetze.de/ao/169 | German assessment periods | Not shown |
| Taxes Management Act 1970, s.34 | https://www.legislation.gov.uk/ukpga/1970/9/section/34 | UK ordinary four-year limit | Not shown |
| Taxes Management Act 1970, s.36 | https://www.legislation.gov.uk/ukpga/1970/9/section/36 | UK twenty-year limit for deliberate behavior | Not shown |
| Taxes Management Act 1970, s.36A | https://www.legislation.gov.uk/id/ukpga/1970/9/section/36A | UK twelve-year offshore limit | Not shown |
| HMRC Compliance Handbook, CH53100, Assessing time limits: extended time limits | https://www.gov.uk/hmrc-internal-manuals/compliance-handbook/ch53100 | UK extended time limits | Updated October 14, 2026 |
| 26 U.S.C. § 6663 (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/6663 | 75% civil fraud penalty | Not shown |
| FinCEN, Inflation Adjustment of Civil Monetary Penalties (90 FR 5629) | https://www.federalregister.gov/documents/2025/01/17/2025-01374/financial-crimes-enforcement-network-inflation-adjustment-of-civil-monetary-penalties | FBAR willful and non-willful penalty amounts | January 17, 2025 |
| OMB, Memorandum M-26-11, Cancellation of Penalty Inflation Adjustments for 2026 | https://www.fec.gov/resources/cms-content/documents/OMB-Memo-Cancellation-of-Penalty-Inflation-Adjustments-for-2026.pdf | No 2026 FBAR penalty adjustment | April 17, 2026 |
| Bittner v. United States, No. 21-1195 (U.S. Supreme Court) | https://www.supremecourt.gov/opinions/22pdf/21-1195_h3ci.pdf | Non-willful FBAR penalty per report | February 28, 2023 |
| 26 U.S.C. § 7201 (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/7201 | Five-year maximum for tax evasion | Not shown |
| § 370 Abgabenordnung, Steuerhinterziehung | https://www.gesetze-im-internet.de/ao_1977/__370.html | German prison terms for evasion | Not shown |
| Bundesgerichtshof, Press release 221/2008, Grundsatzentscheidung zur Strafhöhe bei Steuerhinterziehung | https://www.bundesgerichtshof.de/SharedDocs/Pressemitteilungen/DE/2008/2008221.html | Prison above €1 million evaded | December 2, 2008 |
| § 238 Abgabenordnung, Höhe und Berechnung der Zinsen | https://www.gesetze-im-internet.de/ao_1977/__238.html | 6% interest on evaded tax | Not shown |
| HMRC, CC/FS7a, Penalties for inaccuracies in returns or documents | https://www.gov.uk/government/publications/compliance-checks-penalties-for-inaccuracies-in-returns-or-documents-ccfs7a/compliance-checks-for-penalties-of-inaccuracies-in-returns-or-documents-ccfs7a-factsheet | UK 100% penalty for deliberate concealment | Updated July 21, 2026 |
| Finance (No. 2) Act 2017, Schedule 18, Requirement to correct | https://legislation.gov.uk/ukpga/2017/32/schedule/18/enacted | UK 200% failure-to-correct penalty | Not shown |
| Finance Act 2007, Schedule 24, Part 2 | https://legislation.gov.uk/ukpga/2007/11/schedule/24/part/2/2023-01-01/data.html | UK offshore penalty categories up to 200% | Version as at January 1, 2023 |
| HMRC, Details of deliberate tax defaulters | https://www.gov.uk/government/publications/publishing-details-of-deliberate-tax-defaulters-pddd | Naming of deliberate defaulters | Updated October 2, 2026 |
| Ley Orgánica 10/1995, Código Penal (BOE consolidated text) | https://www.boe.es/eli/es/lo/1995/11/23/10/con | Spanish criminal threshold, penalties, and regularization | Last update April 9, 2026 |
| AP via Ahram Online, German court sentences Bayern's Uli Hoeness to 3 years, 6 months in jail | https://english.ahram.org.eg/News/96586.aspx | Hoeneß sentence (secondary) | March 13, 2014 |
| Salzburg24, Dreieinhalb Jahre Haft für FC-Bayern-Chef Hoeneß | https://www.salzburg24.at/sport/sportwelt/dreieinhalb-jahre-haft-fuer-fc-bayern-chef-hoeness-art-41500 | Hoeneß evaded amount (secondary) | March 13, 2014 |
| NPR, German Tax-Evasion Scandal Stirs Outrage | https://www.npr.org/2008/02/28/19351580/german-tax-evasion-scandal-stirs-outrage | Zumwinkel resignation (secondary) | Not shown |
| Logistics Manager, Former Deutsche Post CEO sentenced | https://www.logisticsmanager.com/11011-former-deutsche-post-ceo-sentenced | Zumwinkel sentence (secondary) | February 3, 2009 |
| Tagesspiegel, Zumwinkel handelt Bewährungsstrafe aus | https://www.tagesspiegel.de/wirtschaft/zumwinkel-handelt-bewahrungsstrafe-aus-1730776.html | Zumwinkel Liechtenstein foundation (secondary) | Not recorded |
| Hello! magazine, A 500,000-euro fine and two-year suspended sentence for Boris Becker | https://www.hellomagazine.com/celebrities/20021024854519/boris/ | Becker sentence (secondary) | October 23, 2002 |
| JURIST, Paul Manafort found guilty on eight charges of fraud | https://www.jurist.org/news/2018/08/paul-manafort-found-guilty-on-eight-charges-of-fraud/ | Manafort conviction (secondary) | August 21, 2018 |
| U.S. Department of Justice, CEO of Multi-Billion-Dollar Software Company Indicted for Decades-Long Tax Evasion and Wire Fraud Schemes | https://www.justice.gov/usao-ndca/pr/ceo-multi-billion-dollar-software-company-indicted-decades-long-tax-evasion-and-wire | Brockman indictment | October 15, 2020 |
| Bernews, Billionaire Robert Brockman Dies At Age 81 | https://bernews.com/2022/08/81-year-old-robert-brockman-dies/ | Brockman death (secondary) | August 11, 2022 |
| Bloomberg Government, Brockman Estate Settles Tax Fraud Case for $750 Million | https://news.bgov.com/daily-tax-report/estate-of-billionaire-brockman-to-pay-750-million-in-tax-fraud-case | Brockman estate settlement (secondary) | December 24, 2025 |
| CBS Sports, Spanish Supreme Court upholds Messi's 21-month prison sentence for tax fraud | https://www.cbssports.com/soccer/news/spanish-supreme-court-upholds-messis-21-month-prison-sentence-for-tax-fraud | Messi case (secondary) | May 24, 2017 |
| Al Jazeera, Footballer Cristiano Ronaldo fined $21m in tax evasion case | https://www.aljazeera.com/sports/2019/1/22/footballer-cristiano-ronaldo-fined-21m-in-tax-evasion-case | Ronaldo case (secondary) | January 22, 2019 |
| AP via WCAX, Pop star Shakira reaches a deal with Spanish prosecutors on 1st day of tax fraud trial | https://www.wcax.com/2023/11/20/pop-star-shakira-reaches-deal-with-spanish-prosecutors-1st-day-tax-fraud-trial/ | Shakira case and residence issue (secondary) | November 20, 2023 |
| Directive (EU) 2015/849 (consolidated, EUR-Lex) | https://eur-lex.europa.eu/eli/dir/2015/849/2024-12-30 | Tax crimes as EU money laundering predicates | Consolidated version of December 30, 2024 |
| American Bar Association, Tax Times, May tax evasion be charged as a money laundering offense? | https://www.americanbar.org/groups/taxation/resources/tax-times/archive/may-tax-evasion-be-charged-money-laundering-offense/ | U.S. money laundering and tax evasion (secondary) | Not shown |
| Helvering v. Gregory, 69 F.2d 809 (2d Cir. 1934) (vLex) | https://www.courtlistener.com/opinion/1562063/helvering-v-gregory/ | Learned Hand's tax-minimization line (secondary text) | Decided March 19, 1934 |
| Gregory v. Helvering, 293 U.S. 465 (1935) (GovInfo) | https://www.govinfo.gov/app/details/USREPORTS-293/USREPORTS-293-465 | Supreme Court affirmance | Decided January 7, 1935 |
| IRC v Duke of Westminster [1935] UKHL 4 (BAILII) | http://www.bailii.org/uk/cases/UKHL/1935/4.html | Duke of Westminster's case | Not recorded (page could not be opened) |
| 26 U.S.C. § 7701 (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/7701 | Economic substance doctrine, § 7701(o) | Not shown |
| IRS, Notice 2010-62, Interim Guidance under the Codification of the Economic Substance Doctrine | https://www.irs.gov/pub/irs-drop/n-10-62.pdf | 2010 codification of economic substance | Not shown |
| 26 U.S.C. § 6662 (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/6662 | 20%/40% economic substance penalty | Not shown |
| § 42 Abgabenordnung, Missbrauch von rechtlichen Gestaltungsmöglichkeiten | https://www.gesetze-im-internet.de/ao_1977/__42.html | German anti-abuse rule | Not shown |
| Finance Act 2013, Part 5, General anti-abuse rule | https://legislation.gov.uk/ukpga/2013/29/part/5 | UK GAAR and 60% penalty (s.212A) | Not shown |
| HMRC, CC/FS34a, Information about the general anti-abuse rule | https://www.gov.uk/government/publications/compliance-checks-information-about-the-general-anti-abuse-rule-ccfs34a/information-about-the-general-anti-abuse-rule | UK GAAR 60% penalty | Updated September 29, 2022 |
| Decreto Legislativo 5 agosto 2015, n. 128 (Normattiva) | https://www.normattiva.it/eli/id/2015/08/18//15G00146/CONSOLIDATED | Italy's 2015 abuse-of-law codification | August 18, 2015 |
| Council Directive (EU) 2016/1164 (Anti-Tax Avoidance Directive) | https://eur-lex.europa.eu/legal-content/EN/TXT/HTML/?uri=CELEX:32016L1164 | EU general anti-abuse clause | July 12, 2016 |
| CJEU, Case C-196/04, Cadbury Schweppes | https://eur-lex.europa.eu/legal-content/EN/TXT/HTML/?uri=CELEX:62004CJ0196 | Wholly artificial arrangements | September 12, 2006 |
| IRS, IR-2025-111 (Notice 2025-67), 401(k) limit increases to $24,500 for 2026 | https://www.irs.gov/newsroom/401k-limit-increases-to-24500-for-2026-ira-limit-increases-to-7500 | 2026 401(k) and IRA limits | November 13, 2025 |
| IRS, Roth IRAs | https://www.irs.gov/retirement-plans/roth-iras | Roth IRA treatment | Reviewed August 9, 2026 |
| IRS, Rev. Proc. 2025-19 | https://www.irs.gov/pub/irs-drop/rp-25-19.pdf | 2026 HSA limits | Not shown |
| IRS, Topic 313, Qualified tuition programs (529 plans) | https://www.irs.gov/taxtopics/tc313 | 529 plans | Reviewed September 24, 2026 |
| IRS, Topic 409, Capital gains and losses | https://www.irs.gov/taxtopics/tc409 | 0/15/20% rates and $3,000 loss limit | Reviewed September 24, 2026 |
| IRS, IR-2025-103, Tax inflation adjustments for tax year 2026 (Rev. Proc. 2025-32) | https://www.irs.gov/newsroom/irs-releases-tax-inflation-adjustments-for-tax-year-2026-including-amendments-from-the-one-big-beautiful-bill | 2026 gift exclusion, estate exemption, FEIE, 37% rate | October 9, 2025 |
| IRS, Rev. Proc. 2025-32 | https://www.irs.gov/pub/irs-drop/rp-25-32.pdf | 2026 inflation-adjusted amounts | Not shown |
| 26 U.S.C. § 1091 (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/1091 | Wash sale rule | Not shown |
| 26 U.S.C. § 103 (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/103 | Municipal bond interest exemption | Not shown |
| 26 U.S.C. § 170 (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/170 | Gifts of appreciated stock to charity | Not shown |
| 26 U.S.C. § 1014 (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/1014 | Step-up in basis at death | Not shown |
| Public Law 119-21 (GovInfo) | https://www.govinfo.gov/app/details/PLAW-119publ21 | One Big Beautiful Bill Act | July 4, 2025 |
| 26 U.S.C. § 2010 (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/2010 | $15 million estate exemption and indexing | Not shown |
| IRS, What's new — Estate and gift tax | https://irs.gov/businesses/small-businesses-self-employed/whats-new-estate-and-gift-tax | 2026 estate exemption | Reviewed July 23, 2026 |
| 26 U.S.C. § 199A (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/199A | Permanent 20% pass-through deduction | Not shown |
| 26 U.S.C. § 1202 (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/1202 | Qualified small business stock exclusion | Not shown |
| IRS, Like-kind exchanges – Real estate tax tips | https://www.irs.gov/businesses/small-businesses-self-employed/like-kind-exchanges-real-estate-tax-tips | Section 1031 exchanges | Reviewed May 1, 2026 |
| New York State Department of Taxation and Finance, Nonresident Audit Guidelines | https://www.tax.ny.gov/pdf/2021/misc/nonresident-audit-guidelines-2021.pdf | New York residency audits | December 2021 |
| IRS, Foreign Tax Credit | https://www.irs.gov/individuals/international-taxpayers/foreign-tax-credit | Foreign tax credit for expats | Reviewed July 9, 2026 |
| § 20 Einkommensteuergesetz | https://www.gesetze-im-internet.de/estg/__20.html | €1,000 investment income allowance | Not shown |
| Bundesministerium der Finanzen, Glossar: Basisrente | https://www.bundesfinanzministerium.de/Web/DE/Service/FAQ_Glossar/Glossar/Functions/glossar.html?lv2=176550&lv3=176576 | Rürup contribution deduction | Not shown |
| § 23 Einkommensteuergesetz (lxgesetze.de mirror) | https://lxgesetze.de/estg/23 | Ten-year and one-year holding periods | Last amended June 29, 2026 (per mirror) |
| Bundesministerium der Finanzen, Einzelfragen zur ertragsteuerrechtlichen Behandlung bestimmter Kryptowerte | https://www.bundesfinanzministerium.de/Content/DE/Downloads/BMF_Schreiben/Steuerarten/Einkommensteuer/2025-03-06-einzelfragen-kryptowerte.html | Crypto one-year holding period | March 6, 2025 |
| § 16 Erbschaftsteuer- und Schenkungsteuergesetz, Freibeträge | https://www.gesetze-im-internet.de/erbstg_1974/__16.html | €400,000 allowance per child | Not shown |
| § 13a Erbschaftsteuer- und Schenkungsteuergesetz (lxgesetze.de mirror) | https://lxgesetze.de/erbstg/13a | 85%/100% business assets relief | Last amended June 22, 2026 (per mirror) |
| Rödl & Partner, Bundesverfassungsgericht prüft Erbschaftsteuer | https://www.roedl.com/insights/bundesverfassungsgericht-prueft-erbschaftsteuer/ | Pending constitutional challenge (secondary) | August 12, 2026 |
| GOV.UK, Individual Savings Accounts (ISAs) | https://www.gov.uk/individual-savings-accounts | £20,000 ISA allowance | Last updated January 8, 2025 |
| HMRC, Reduction in the cash Individual Savings Account (ISA) limit | https://www.gov.uk/government/publications/reduction-in-the-cash-individual-savings-account-isa-limit | £12,000 cash ISA limit from April 2027 | September 17, 2026 |
| GOV.UK, Tax on your private pension contributions: Annual allowance | https://gov.uk/tax-on-your-private-pension/annual-allowance | £60,000 pension annual allowance | Last updated November 8, 2024 |
| GOV.UK, Tax relief for investors using venture capital schemes | https://www.gov.uk/guidance/venture-capital-schemes-tax-relief-for-investors | EIS 30% and SEIS 50% relief | Last updated April 6, 2026 |
| GOV.UK, Tax relief when you donate to a charity: Gift Aid | https://www.gov.uk/donating-to-charity/gift-aid | Gift Aid | Last updated September 30, 2026 |
| GOV.UK, How Inheritance Tax works: Rules on giving gifts | https://www.gov.uk/inheritance-tax/gifts | Seven-year rule on gifts | Last updated November 8, 2024 |
| Agenzia delle Entrate, Circolare 19/2021, Regime fiscale dei piani di risparmio a lungo termine (PIR) | https://www.agenziaentrate.gov.it/portale/documents/20143/4002800/Circolare+19_2021.pdf/ | PIR five-year exemption | Not recorded (page could not be opened) |
| Legge 11 dicembre 2016, n. 232 (Normattiva) | https://www.normattiva.it/eli/stato/LEGGE/2016/12/11/232/CONSOLIDATED | PIR statutory basis | Not shown |
| COVIP, Informazioni sul trattamento fiscale della previdenza complementare | https://www.covip.it/per-il-cittadino/educazione-previdenziale/faq/trattamento-fiscale | Italian pension fund deduction | Not shown |
| Agenzia delle Entrate, Imposta di successione: Aliquote e franchigie | https://www.agenziaentrate.gov.it/portale/schede/pagamenti/imposta-di-successione/aliquote-e-franchigie | Italian 4% inheritance tax above €1 million | Not recorded (page could not be opened) |
| Agenzia delle Entrate, Circolare 3/E, reform of inheritance and gift tax | https://www.agenziaentrate.gov.it/portale/documents/20143/8410821/Circolare_decreto_delegato_Successioni_Donazioni.pdf | 2024 inheritance tax reform | April 16, 2025 |
| Ley 29/1987, Impuesto sobre Sucesiones y Donaciones (BOE consolidated text) | https://www.boe.es/eli/es/l/1987/12/18/29/con | Spanish 95% family business reduction | Last update December 28, 2022 |
| Comunidad de Madrid, Impuesto de Sucesiones | https://www.comunidad.madrid/atencion-contribuyente/impuesto-sucesiones | Madrid inheritance relief | Last update July 1, 2026 |
| Agencia Tributaria, Régimen fiscal aplicable a los trabajadores desplazados: Régimen especial | https://sede.agenciatributaria.gob.es/Sede/irpf/tengo-que-presentar-declaracion/regimen-fiscal-aplicable-trabajadores-desplazados/regimen-especial.html | Beckham law duration | March 18, 2026 |
| Agencia Tributaria, Manual práctico IRPF 2023: Régimen fiscal especial aplicable a trabajadores desplazados | https://sede.agenciatributaria.gob.es/Sede/ayuda/manuales-videos-folletos/manuales-practicos/irpf-2023/c15-calculo-impuesto-determinacion-cuotas-integras/regimen-fiscal-especial-aplicable-trabajadores.html | Beckham law 24% rate | March 18, 2024 |
| Ondernemersplein (Netherlands government), Vergoeding 30%-regeling expats wordt 27% | https://ondernemersplein.overheid.nl/vergoeding-30-procent-regeling-expats-wordt-27-procent | Dutch expat exemption | Not shown |
| Agenzia delle Entrate, Opzione per i neo residenti | https://www.agenziaentrate.gov.it/portale/schede/agevolazioni/opzione-per-i-neo-residenti/infogen-opzionale-neo-residenti | Italian flat tax for new residents | Not shown |
| Legge 30 dicembre 2025, n. 199 (Normattiva) | https://www.normattiva.it/eli/id/2025/12/30/25G00212/CONSOLIDATED/ | Italian flat tax raised to €300,000 | December 30, 2025 |
| Swiss Federal Department of Finance, Lump-sum taxation | https://www.efd.admin.ch/en/lump-sum-taxation | Swiss lump-sum taxation | April 10, 2024 |
| AADE, Tax incentives under Articles 5A, 5B and 5C of Law 4172/2013 | https://www.aade.gr/sites/default/files/2023-08/Tax%20Incentives%20%28articles%205A%2C5B%2C%205C%20of%20the%20ITC%29.pdf | Greek non-dom regime | Not shown |
| § 6 Außensteuergesetz (lxgesetze.de mirror) | https://lxgesetze.de/astg/6 | German exit tax | Last amended December 22, 2025 (per mirror) |
| Agencia Tributaria, Manual práctico IRPF 2025: Régimen especial de ganancias patrimoniales por cambio de residencia | https://sede.agenciatributaria.gob.es/Sede/ayuda/manuales-videos-folletos/manuales-practicos/irpf-2025/c11-ganancias-perdidas-patrimoniales/regimen-especial-ganancias-patrimoniales-cambio-residencia/introduccion-ambito-aplicacion.html | Spanish exit tax | March 17, 2026 |
| Jongbloed Fiscaal Juristen, Emigratie en conserverende aanslag | https://www.jongbloed-fiscaaljuristen.nl/emigratie/actueel_emigratie/conserverende_aanslagen/ | Dutch exit tax (secondary) | Updated November 1, 2023 |
| IRS, U.S. taxpayers residing in the United States (Streamlined Domestic Offshore Procedures) | https://irs.gov/individuals/international-taxpayers/us-taxpayers-residing-in-the-united-states | Streamlined procedures, 5% penalty | Reviewed July 10, 2026 |
| IRS, U.S. taxpayers residing outside the United States (Streamlined Foreign Offshore Procedures) | https://www.irs.gov/individuals/international-taxpayers/us-taxpayers-residing-outside-the-united-states | Streamlined procedures, no penalty abroad | Reviewed July 11, 2026 |
| IRS Criminal Investigation, Voluntary Disclosure Practice | https://irs.gov/compliance/criminal-investigation/irs-criminal-investigation-voluntary-disclosure-practice | Six-year voluntary disclosure period | Reviewed July 20, 2026 |
| § 371 Abgabenordnung (lxgesetze.de mirror) | https://lxgesetze.de/ao/371 | German voluntary self-disclosure | Not shown |
| § 398a Abgabenordnung, Absehen von Verfolgung in besonderen Fällen | https://www.gesetze-im-internet.de/ao_1977/__398a.html | Self-disclosure surcharge tiers | Not shown |
| HMRC, Make a disclosure using the Worldwide Disclosure Facility | https://www.gov.uk/guidance/worldwide-disclosure-facility-make-a-disclosure | UK offshore disclosure | Last updated April 6, 2026 |
| HMRC, Code of Practice 9: where HMRC suspects fraud (COP9) | https://www.gov.uk/government/publications/code-of-practice-9-where-hmrc-suspects-fraud-cop9 | Contractual Disclosure Facility | June 14, 2023 |
| Agencia Tributaria, Preguntas frecuentes, Ley 11/2021 | https://sede.agenciatributaria.gob.es/static_files/Sede/Actualidad/Novedades/2021/Faq_Ley_11_2021.pdf | Spanish late-filing surcharges | July 22, 2021 |
| Agenzia delle Entrate, Ravvedimento: Che cos'è | https://www.agenziaentrate.gov.it/portale/schede/accertamenti/ravvedimento-operoso/schedai_ravvedimentooperoso | Italian ravvedimento operoso | Not shown |
| 26 U.S.C. § 7525 (Cornell LII) | https://www.law.cornell.edu/uscode/text/26/7525 | Tax practitioner privilege limited to noncriminal matters | Not shown |
| HMRC, Find out about the Non-Statutory Clearance Service | https://www.gov.uk/guidance/non-statutory-clearance-service-guidance | UK clearances | Last updated August 26, 2026 |
| § 89 Abgabenordnung, Beratung, Auskunft | https://www.gesetze-im-internet.de/ao_1977/__89.html | German binding ruling | Not shown |
| Agenzia delle Entrate, Interpello: Che cos'è | https://www.agenziaentrate.gov.it/portale/schede/istanze/scheda-interpello/infogen-interpello | Italian interpello | Not shown |
| Agencia Tributaria, Doctrina y criterios interpretativos | https://sede.agenciatributaria.gob.es/Sede/normativa-criterios-interpretativos/doctrina-criterios-interpretativos.html | Spanish binding consultations | August 7, 2026 |
A note on method: this article is general information, not tax or legal advice, and any decision should be made with a professional who knows your situation and your jurisdiction. The specific thresholds cited above — U.S. retirement account limits, the estate and gift tax exemptions, the Foreign Earned Income Exclusion, FBAR penalties, and the German, British, Italian, and Spanish allowances and rates — were checked against official and professional sources for the 2026 tax year, with inline citations to each. Tax thresholds change annually and should be reconfirmed for your own filing year and jurisdiction.