Key takeaways
- Transparency shrank evasion but not offshore wealth: the EU Tax Observatory's Global Tax Evasion Report 2024 puts offshore household financial wealth at about 10% of world GDP, with only about a quarter of it still untaxed, and profits shifted to tax havens at about $1 trillion in 2022, or 35% of multinationals' foreign profits.
- The UAE levies no personal income tax and introduced a 9% corporate tax for financial years starting on or after 1 June 2023 (UAE Ministry of Finance, Corporate Tax), and it remains the leading net destination for migrating millionaires in the Henley Private Wealth Migration Report 2026.
- Singapore exempts the investment income of family-office funds under Sections 13O and 13U only if they hold S$20 million or S$50 million in designated investments and employ two or three qualifying investment professionals (MAS, Fund Tax Schemes for Family Offices); more than 2,000 single family offices received these incentives as of end-December 2025 (MAS written parliamentary reply, 5 August 2026).
- Zero-tax islands now collect the 15% minimum themselves and hand part of it back: Bermuda's 15% corporate income tax applies from 1 January 2025 to groups with €750 million or more in revenue (Government of Bermuda, Corporate Income Tax Act 2023), alongside a Tax Credits Act enacted in December 2025 (PwC Worldwide Tax Summaries, Bermuda).
- Residence regimes have short political lives: Portugal closed its non-habitual resident regime to new entrants from 2024, the UK abolished non-dom status on 6 April 2025, Spain ended its golden visa on 3 April 2025 (Organic Law 1/2025, BOE), and the EU Court of Justice ruled Malta's investor citizenship scheme unlawful on 29 April 2025 (Case C-181/23, Commission v Malta).
- The main limits of transparency remain unresolved: the CRS does not reach directly held real estate, crypto exchanges under the OECD's Crypto-Asset Reporting Framework only start in 2027 for the first wave of jurisdictions and 2028 or 2029 for others (OECD/Global Forum CARF commitment list), and the United States stays outside the CRS.
What is the paradox in the numbers?
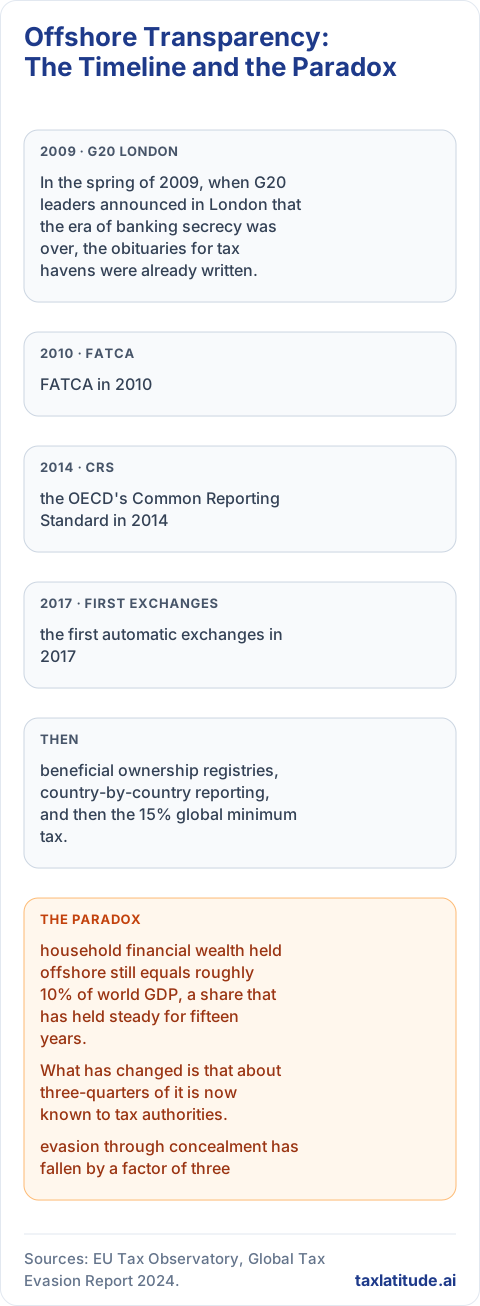
In the spring of 2009, when G20 leaders announced in London that the era of banking secrecy was over, the obituaries for tax havens were already written. What followed seemed to prove them right: FATCA in 2010, the OECD's Common Reporting Standard in 2014, the first automatic exchanges in 2017, beneficial ownership registries, country-by-country reporting, and then the 15% global minimum tax.
The numbers tell a different story. According to the EU Tax Observatory, household financial wealth held offshore still equals roughly 10% of world GDP, a share that has held steady for fifteen years. What has changed is that about three-quarters of it is now known to tax authorities. Boston Consulting Group's annual studies put cross-border financial wealth above $12 trillion and growing steadily, reaching $15.7 trillion in 2025. Switzerland and Hong Kong now run neck and neck for the largest share, each managing around $2.9 trillion as of 2025, with Hong Kong narrowly ahead after overtaking Switzerland for the first time; Singapore ranks third, at about $2.1 trillion and growing faster than either (Boston Consulting Group, Global Wealth Report 2026).
So it is worth taking seriously a hypothesis the public debate long brushed aside: secrecy was only one product in the catalog, and not necessarily the most profitable. Offshore centers lost one clientele, the run-of-the-mill tax cheat, the European doctor or shopkeeper with a few hundred thousand euros in Geneva. They kept, and expanded, the clientele that matters.
What does offshore sell when it no longer sells secrecy?
Tax evasion through concealment was a crude service. What has replaced it is more sophisticated and, for the most part, perfectly legal.
The first product is tax neutrality. An investment fund pools investors from thirty countries to buy assets in twenty others. If the fund itself were taxed, it would add a layer of tax on top of what the portfolio companies and the end investors already pay. So it is domiciled in a jurisdiction that takes nothing: the Cayman Islands for hedge funds, Luxembourg and Ireland for funds sold across Europe. Nobody is hiding. The fund is registered and audited, and its investors are reported to their home tax authorities through the CRS.
The second is law. Offshore jurisdictions in the British tradition offer common law, well-tested trust law, competent commercial courts, and, as a court of last resort, the Judicial Committee of the Privy Council in London. For a Russian, Nigerian, or Brazilian entrepreneur, holding assets through a British Virgin Islands company is above all a way to put them beyond the reach of an arbitrary court system at home. Many emerging-market groups listed in New York or London are, legally speaking, Cayman or Jersey holding companies.
The third is wealth protection: asset protection trusts built to withstand creditors, ex-spouses, and forced heirship rules.
The fourth is still tax, but in a new form: no longer the tax you hide, but the tax you don't owe, because you have legally moved yourself, your company, or your assets.
How did the islands go from mailbox to "substance"?
Starting in 2017, the offensive against zero-tax jurisdictions took the form of an economic substance requirement. Under twin pressure from the OECD's Forum on Harmful Tax Practices and the EU blacklist, the Cayman Islands, Bermuda, the British Virgin Islands, Jersey, Guernsey, the Isle of Man, and the Bahamas passed laws, effective in 2019, requiring companies engaged in certain activities (holding, financing, intellectual property, fund management, insurance) to show proportionate local directors, employees, premises, and spending. Seychelles followed in 2021: its Business Tax (Amendment) Act, in force from September 15, applied a similar economic-substance test to foreign-source passive income, and the EU removed the country from its tax-haven blacklist that October (Seychelles Revenue Commission, SI 78 of 2021 — Business Tax (Amendment) Act, 2020).
The effect was twofold. Tens of thousands of shells were struck off: the British Virgin Islands, which had more than 450,000 active companies in the early 2010s, lost roughly one in four: the register peaked at 481,002 companies in December 2011 and stood at 356,256 at the end of 2025, before rebounding to 362,165 in the first quarter of 2026 (BVI Financial Services Commission, Statistical Bulletin Q4 2025). But for those that remain, substance can be bought. A local industry of resident directors, shared offices, and corporate secretarial services has grown up to supply exactly the required minimum. And the rule created a barrier to entry: what used to cost a thousand dollars a year now costs tens of thousands, which weeds out the small-time cheat and leaves the institutional client untouched.
Because that is where the core business lies. The Cayman Islands is home to nearly 13,000 open-ended funds and, since a 2020 law passed to get off the EU blacklist, more than 15,000 registered closed-ended funds, making it the world's leading domicile for hedge funds and private equity. Bermuda dominates reinsurance and catastrophe bonds, Guernsey captive insurance. Jersey has specialized in private wealth structures and family endowment vehicles.
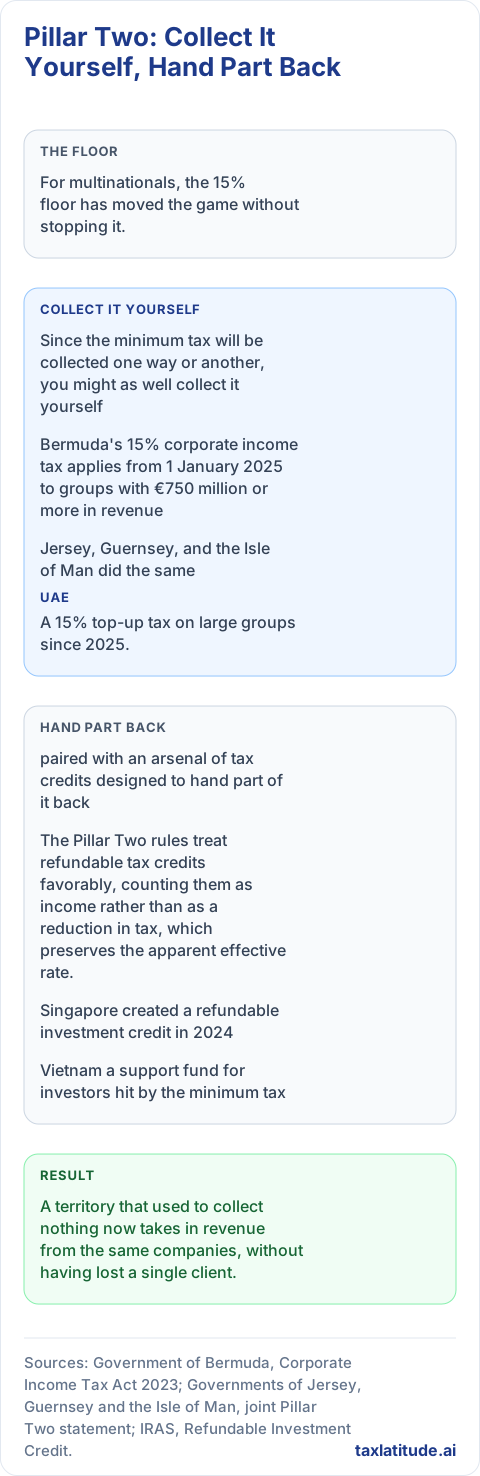
Even Pillar Two has been absorbed. Since the minimum tax will be collected one way or another, you might as well collect it yourself: Bermuda introduced a 15% corporate income tax, in effect since 2025, on groups with €750 million or more in revenue (Government of Bermuda, Corporate Income Tax Act 2023), paired with an arsenal of tax credits designed to hand part of it back (PwC Worldwide Tax Summaries, Bermuda). Jersey, Guernsey, and the Isle of Man did the same (joint statement of the governments of Jersey, Guernsey and the Isle of Man). A territory that used to collect nothing now takes in revenue from the same companies, without having lost a single client.
Why is the Gulf the new center of gravity?
The big winner of the post-secrecy era is Dubai. The United Arab Emirates levies no personal income tax, no capital gains tax, and no estate tax. It participates in the CRS, but transparency changes nothing: data on a UAE resident goes to a government that has no tax to claim from them.
The strategy was methodical. A ten-year golden visa from 2019, in exchange for a real estate investment of about 2 million dirhams (Dubai Land Department, Golden Visa application — Investor). Two English-law financial centers, the DIFC in Dubai and the ADGM in Abu Dhabi, with their own courts and foundation regimes. A 9% corporate tax introduced in June 2023 (UAE Ministry of Finance, Corporate Tax), enough to stop being a "zero-tax" jurisdiction, with an exemption preserved for qualifying free zone income. A 15% top-up tax on large groups since 2025. And removal from the Financial Action Task Force gray list in February 2024, two years after landing on it (FATF, Jurisdictions under Increased Monitoring — 23 February 2024).
The results show up in the flows. Henley & Partners, whose estimates should be handled with care but whose trend is corroborated elsewhere, has ranked the UAE the top destination for migrating millionaires since 2022, a ranking the Henley Private Wealth Migration Report 2026, published June 16, 2026, confirms still holds, as part of a record 165,000 high-net-worth relocations the report projects worldwide for 2026. The DIFC hosts several hundred family offices. The end of the United Kingdom's "non-dom" regime in April 2025 added fuel.
One blind spot remains: real estate. The CRS does not cover directly held property. The Dubai Unlocked investigation, published in 2024 by a media consortium working from leaked property records, along with research by the EU Tax Observatory, puts foreign-owned Dubai real estate at $160 billion in 2022, a significant share of it declared nowhere.
What is Singapore's family office rush?
In Asia, the competition turns on one product: the family office, a structure dedicated to managing a single family's wealth. Singapore exempts the investment income of the funds such offices manage, under Sections 13O and 13U of its Income Tax Act, subject to minimum assets (S$20 million for the first regime, S$50 million for the second), local spending, and the hiring of investment professionals (MAS, Fund Tax Schemes for Family Offices). The number of family offices there went from about 400 in 2020 to more than 2,000 in 2024. In 2020 the city-state also created a purpose-built fund vehicle, the Variable Capital Company, of which more than a thousand have been formed.
The foundation of the model is a territorial system: foreign-source income is in principle not taxed, and the city-state taxes neither capital gains nor estates.
There is a flip side. In August 2023, a police operation uncovered a money laundering ring involving about S$3 billion and a group of foreign nationals (OCCRP), some of whom had obtained the family office tax incentives. Approval conditions have since been tightened.
Why is Europe the quiet champion?
The world's biggest offshore centers are not tropical islands. The Tax Justice Network's Corporate Tax Haven Index puts the British Virgin Islands, Cayman, and Bermuda at the top, followed, in its 2024 edition, by Switzerland, Singapore, Hong Kong, the Netherlands, Jersey, Ireland, and Luxembourg in 10th place (Tax Justice Network, Corporate Tax Haven Index).
Luxembourg, which gave up banking secrecy in 2013, now administers more than €6.7 trillion in fund assets (CSSF, global situation of undertakings for collective investment, end of August 2026), making it the world's second-largest fund domicile after the United States. Its recent success owes much to a vehicle created in 2016, the Reserved Alternative Investment Fund (RAIF), which needs no prior approval from the regulator, and to the special limited partnership, modeled on the Anglo-American LP. The OpenLux investigation, published in 2021 using the public beneficial ownership registry, counted about 55,000 offshore companies holding €6.5 trillion in assets. Transparency made it possible to know that. It changed nothing about it.
Ireland closed the Double Irish in 2015, with a phase-out through 2020. U.S. groups then moved their intellectual property onshore to Ireland, where capital allowances on it absorb a large share of profits, an arrangement nicknamed the "Green Jersey." As a result, corporate tax receipts grew more than sixfold in ten years, topping €28 billion in 2024 and €32.9 billion in 2025, excluding the Apple payment in both years (Department of Finance, Fiscal Monitor for December 2025), with more than half paid by about ten groups. Dublin has set up two sovereign wealth funds to put aside a windfall it knows is precarious (Government of Ireland, Future Ireland Fund and Infrastructure, Climate and Nature Fund).
The Netherlands has made the clearest effort: a conditional withholding tax on interest and royalties paid to low-tax jurisdictions since 2021, extended to dividends in 2024. Flows through Dutch letterbox companies have fallen noticeably. Switzerland abolished its privileged cantonal regimes in 2020, replaced them with very low ordinary rates (around 12% in several cantons), a patent box, and R&D deductions, and remains the world capital of commodities trading. Cyprus and Malta round out the picture, the latter with a shareholder refund system that brings its 35% headline rate down to an effective 5% or so.
What is the market for residence?
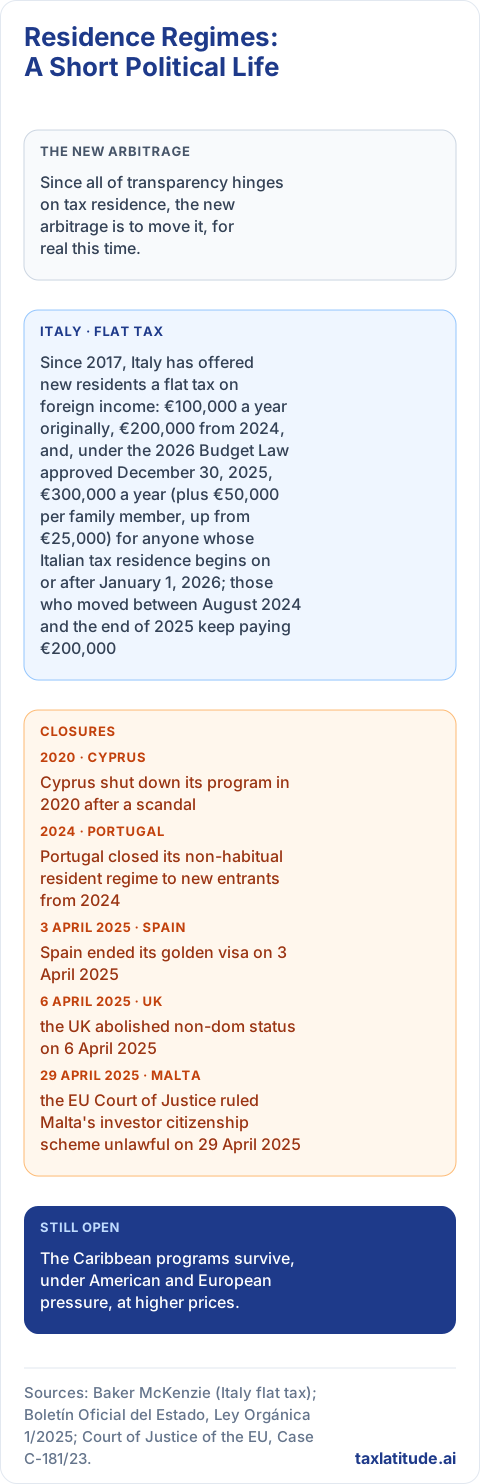
Since all of transparency hinges on tax residence, the new arbitrage is to move it, for real this time. TaxLatitude's tax residency tool walks through how that determination actually gets made. Since 2017, Italy has offered new residents a flat tax on foreign income: €100,000 a year originally, €200,000 from 2024, and, under the 2026 Budget Law approved December 30, 2025, €300,000 a year (plus €50,000 per family member, up from €25,000) for anyone whose Italian tax residence begins on or after January 1, 2026; those who moved between August 2024 and the end of 2025 keep paying €200,000 (Baker McKenzie). Milan got an influx of bankers and large fortunes out of it. Greece copied the scheme, Switzerland has practiced lump-sum taxation based on living expenses for more than a century, and Monaco never went away.
But the political life cycle of these regimes is short. Portugal closed its non-habitual resident program in 2024, blamed for sending housing prices soaring, and replaced it with a scheme limited to scientific and technical profiles. The United Kingdom abolished its two-century-old non-dom regime. Spain scrapped its golden visa in 2025 (Organic Law 1/2025, BOE).
As for passports sold with no residency requirement, the vise is tightening in Europe. Cyprus shut down its program in 2020 after a scandal, and the EU's Court of Justice ruled in April 2025 that Malta's violated EU law, since citizenship cannot be the object of a commercial transaction (Judgment of the Court of Justice, Case C-181/23, Commission v Malta). The Caribbean programs survive, under American and European pressure, at higher prices.
How did corporations move from rate competition to credit competition?
For multinationals, the 15% floor has moved the game without stopping it. The Pillar Two rules treat refundable tax credits favorably, counting them as income rather than as a reduction in tax, which preserves the apparent effective rate. Several jurisdictions have accordingly reshaped their incentives in that form. Singapore created a refundable investment credit in 2024 (IRAS, Refundable Investment Credit), Vietnam a support fund for investors hit by the minimum tax, Bermuda its own toolkit (PwC Worldwide Tax Summaries, Bermuda). The government collects 15% with one hand and gives part of it back with the other.
Add to that the substance-based income exclusion, which exempts a fixed return on payroll and tangible assets, and the side-by-side safe harbor the Inclusive Framework adopted on January 5, 2026, which excludes U.S.-parented groups from the Income Inclusion Rule and the Undertaxed Profits Rule for fiscal years beginning on or after January 1, 2026, while each country's own qualified domestic minimum top-up tax still applies to them (Baker McKenzie, Pillar Two Side-by-Side Package Released). The EU Tax Observatory estimates that profits shifted to tax havens still run close to $1 trillion a year, about 35% of multinationals' foreign profits, a share unchanged in ten years.
Why is the United States secrecy's last refuge?
That leaves the central irony of this story. The country that forced transparency on the world never joined the CRS and sends only partial information abroad under FATCA. South Dakota, which abolished the rule against perpetuities back in 1983, taxes neither trust income nor trust capital gains and guarantees the confidentiality of court proceedings involving trusts. Assets held by its trust companies topped $500 billion at the start of the decade and have kept growing; the Pandora Papers identified dozens of trusts there tied to foreign fortunes. Nevada, Wyoming, Alaska, and Delaware compete for the same market. (The full story of why the U.S. stays outside the CRS.)
The Corporate Transparency Act was supposed to clean this up by requiring beneficial ownership reporting. In March 2025, Treasury exempted U.S. companies and their American owners. A European can no longer hide in Zurich. A Latin American still can in Sioux Falls.
Hold assets through a US trust as a non-American? South Dakota and similar states guarantee confidentiality locally, but that says nothing about your own country's reporting rules or what you owe the US on US-source income. Check your actual US exposure →
What blind spots remain?
Concealment hasn't disappeared. It has moved to what the CRS can't see. Real estate, in Dubai, London, or Miami. The freeports of Geneva, Luxembourg, and Singapore, where billions in art and precious metals sit in storage. Crypto assets, which the OECD's reporting framework will begin to cover only with the first exchanges scheduled for 2027 (OECD/Global Forum CARF commitment list). Luxembourg life insurance, fully reported, but whose wrapper defers taxation and structures the transfer of wealth between generations. And failures of execution: self-certifications of convenience, and receiving tax agencies unable to make use of the files they get.
What did transparency change, and what can't it change?
It would be wrong to conclude that nothing has moved. The ordinary tax cheat is gone: no established bank opens undeclared accounts anymore, and evasion through concealment has fallen by a factor of three (EU Tax Observatory, Global Tax Evasion Report 2024). The cost of access to tax planning has risen sharply, making it a narrower privilege than before. Governments finally have the data to legislate with their eyes open, as the debate over a minimum tax on the very wealthy shows.
But transparency has also had an effect its champions didn't see coming: it legitimized offshore. A financial center rated compliant by the Global Forum, off the FATF gray list, with a 15% tax and substance rules, is no longer a tax haven as the lists define one. It is a respectable competitor. Banking secrecy was an information problem, and it has largely been solved. What remains is a sovereignty problem: as long as some countries have an interest in offering mobile capital and mobile people terms their neighbors can't match, there will be an industry to organize the move. Transparency lets you see the arbitrage. It doesn't prohibit it — the line between hiding money and legal tax planning still runs through it.
Frequently asked questions
If I move to Dubai, will my home country still see my bank accounts?
Under the CRS, account data is reported to the country where you are tax resident, so a genuine UAE resident's data goes to the UAE, which has no personal income tax to collect; if your home country still treats you as resident, it can still receive the data. Directly held Dubai property sits outside the CRS altogether, which is why the Dubai Unlocked leak revealed holdings that had been declared nowhere.
How much money does a Singapore family office need to qualify for the 13O or 13U tax exemption?
The fund must hold S$20 million in designated investments for Section 13O or S$50 million for Section 13U throughout the incentive period, and the family office must employ two or three qualifying investment professionals, at least one of them not a family member (MAS). Local business spending requirements also apply.
What is Italy's flat tax for new residents in 2026?
For people whose Italian tax residence begins on or after 1 January 2026, the substitute tax on foreign income is €300,000 a year plus €50,000 per family member, while those who arrived earlier keep the €100,000 or €200,000 amount in force when they moved.
Are the Cayman Islands still a tax haven after the economic substance rules?
The Cayman Islands still levy no corporate tax on most entities and remain the leading domicile for hedge funds and private funds, with 12,876 mutual funds and 17,722 private funds at the end of 2025. The Tax Justice Network's Corporate Tax Haven Index still ranks Cayman second, even though the OECD rates its regime as not harmful.
Why doesn't the United States participate in the CRS?
The United States relies on its own FATCA regime, which obliges foreign banks to report U.S. account holders but sends only partial information back to partner countries, so it never joined the CRS. That gap, combined with the March 2025 exemption of U.S. companies and owners from beneficial ownership reporting under the Corporate Transparency Act, is why states such as South Dakota attract foreign trust money.
Will crypto held on a foreign exchange be reported to my tax authority?
Increasingly, yes: under the OECD's Crypto-Asset Reporting Framework, the first wave of jurisdictions, including most EU member states, the UK, Jersey, Guernsey, the Isle of Man and the Cayman Islands, is committed to first exchanges in 2027, with others, including the UAE, committed for 2028, and the United States for 2029 (OECD/Global Forum CARF commitment list). Until those exchanges begin, crypto is one of the main assets the CRS does not reach.
When should you hire a professional?
The regimes in this guide change every year, depend on residence tests and approval conditions that turn on individual facts, and interact with the tax rules of the country you are leaving, so any real decision needs advice on your specific situation rather than a general overview.
- Moving to the UAE, Singapore, or a European residence regime. Whether your home country still treats you as resident, levies an exit tax, or keeps taxing certain income depends on its own rules, not on the destination's.
- Running a fund near a domicile threshold. Economic substance tests in Cayman, the BVI, Jersey, Guernsey or the Isle of Man require proportionate local directors, staff and spending, and a shortfall can mean penalties or strike-off.
- Setting up a Singapore family office. The 13O and 13U incentives require minimum assets, investment professionals and local spending throughout the incentive period, and MAS has added pre-application screening.
- Holding assets in a blind-spot category. Real estate, freeport storage, crypto or U.S. trusts may not be reported automatically today, but you may still have a personal disclosure obligation at home, and CARF exchanges are starting.
- Managing a multinational group affected by Pillar Two. Refundable credits, domestic minimum top-up taxes and the 2026 side-by-side safe harbor change effective rates group by group and jurisdiction by jurisdiction.
- Considering a citizenship- or residence-by-investment program. Programs in Cyprus, Malta, Portugal and Spain have closed or been struck down within a few years, and terms elsewhere can change before an application is decided.
A cross-border tax attorney fits questions about what follows you home and about structuring, an immigration or residence-planning specialist fits visa and investment-program questions, and an international tax adviser fits fund substance, family office and Pillar Two questions for businesses.
Sources
All sources accessed October 16, 2026. Page dates are given only where the page showed one; otherwise the cell says so.
| Source | URL | Used for | Page date |
|---|---|---|---|
| EU Tax Observatory, Global Tax Evasion Report 2024 | https://taxobservatory.eu/publication/global-tax-evasion-report-2024/ | Offshore wealth at about 10% of world GDP, share untaxed, $1 trillion shifted profits, threefold fall in evasion | Not shown |
| Boston Consulting Group, Global Wealth Report 2026 | https://www.bcg.com/publications/2026/global-wealth-growth-in-an-era-of-reordering | Cross-border wealth totals and booking-center ranking (freshness flag) | Not shown |
| Henley & Partners, Henley Private Wealth Migration Report 2026 | https://www.henleyglobal.com/publications/henley-private-wealth-migration-report-2026 | UAE as top millionaire destination; change of report methodology | 16 June 2026 |
| UAE Ministry of Finance, Corporate Tax | https://mof.gov.ae/corporate-tax/ | UAE corporate tax effective for financial years from 1 June 2023 | Not shown |
| Dubai Land Department, Golden Visa application — Investor | https://dubailand.gov.ae/en/eservices/request-for-golden-visa-investor | AED 2 million threshold for 10-year residence | Not shown |
| FATF, Jurisdictions under Increased Monitoring — February 2024 | https://www.fatf-gafi.org/en/publications/High-risk-and-other-monitored-jurisdictions/Increased-monitoring-february-2024.html | UAE removal from the gray list | 23 February 2024 |
| OCCRP, What Is Dubai Unlocked? | https://www.occrp.org/en/dubai-unlocked/what-is-dubai-unlocked-everything-you-need-to-know | Dubai Unlocked investigation and foreign-owned property estimate | Not shown |
| Monetary Authority of Singapore, Fund Tax Schemes for Family Offices | https://www.mas.gov.sg/schemes-and-initiatives/fund-tax-incentive-scheme-for-family-offices | Sections 13O/13U asset and staffing conditions | 05 August 2024 |
| Monetary Authority of Singapore, Written reply on the number of Single Family Offices | https://www.mas.gov.sg/news/parliamentary-replies/2026/written-reply-on-sfos | More than 2,000 incentivized SFOs as of end-December 2025 | 05 August 2026 |
| Caproasia, MAS Chairman on family offices (parliamentary reply of 5 February 2025) | https://www.caproasia.com/2025/02/06/singapore-mas-chairman-gan-kim-yong-on-family-offices-2000-single-family-offices-awarded-tax-incentives-employ-2200-singapore-citizens-permanent-residents/ | Growth from 400 SFOs (2020) to over 2,000 (2024) — secondary | 6 February 2025 |
| OCCRP, Singapore Recovers Billions of Dollars in Money Laundering Case | https://occrp.org/en/news/singapore-recovers-billions-of-dollars-in-money-laundering-case | S$3 billion laundering case of August 2023 | Not shown |
| Fortune, Six family offices tied to Singapore money-laundering case | https://dc.fortune.com/asia/2024/07/03/singapore-biggest-money-laundering-scandal-ever-family-offices-linked-to-case/ | Link between the case and incentivized family offices — secondary | Not shown |
| IRAS, Refundable Investment Credit (RIC) | https://www.iras.gov.sg/schemes/disbursement-schemes/refundable-investment-credit-(ric) | Singapore refundable investment credit introduced in Budget 2024 | Not shown |
| EY, Singapore Budget 2024 — Refundable Investment Credit | https://www.ey.com/en_gl/technical/tax-alerts/singapore-budget-2024---introduction-of-refundable-investment-cr | Qualified refundable tax credit treatment under GloBE — secondary | Not shown |
| Government of Bermuda, Tabling of the Corporate Income Tax Act 2023 | https://www.gov.bm/news/tabling-corporate-income-tax-act-2023 | Bermuda 15% CIT for groups with €750 million+ revenue from 2025 | Not shown |
| PwC Worldwide Tax Summaries, Bermuda — Corporate | https://taxsummaries.pwc.com/bermuda/corporate | Bermuda CIT effective date and Tax Credits Act 2025 | Last reviewed 19 February 2026 |
| Governments of Jersey, Guernsey and the Isle of Man, joint Pillar Two statement | https://www.gov.je/SiteCollectionDocuments/Tax%20and%20your%20money/News%20Release%20-%20Crown%20Dependencies%20announce%20agreed%20approach%20to%20Pillar%20Two%20Framework%20(1).pdf | Crown Dependencies' 15% domestic minimum tax from 2025 | Not shown |
| Cayman Finance, Cayman fund registrations increase 40% since 2020 | https://caymanfinance.ky/2026/01/28/cayman-fund-registrations-increase-40-since-2020/ | Cayman mutual and private fund counts at end-2025 — secondary | Not shown |
| BVI Financial Services Commission, Statistical Bulletin Q4 2025 | https://www.bvifsc.vg/sites/default/files/q4_2025_statistical_bulletin_kp.pdf | BVI active company count | Not shown |
| Tax Justice Network, Indexes and tools (Corporate Tax Haven Index 2024) | https://taxjustice.net/?p=9445 | Corporate Tax Haven Index ranking | Not shown |
| CSSF, Global situation of undertakings for collective investment, end of August 2026 | https://www.cssf.lu/fr/2026/10/situation-globale-des-organismes-de-placement-collectif-a-la-fin-du-mois-daout-2026/ | Luxembourg fund net assets (freshness flag) | Not shown |
| OCCRP, Shedding Light on Big Secrets in Tiny Luxembourg (OpenLux) | https://www.occrp.org/en/openlux/shedding-light-on-big-secrets-in-tiny-luxembourg | OpenLux investigation | Not shown |
| Chartered Accountants Ireland, Fiscal Monitor for December 2025 published | https://www.charteredaccountants.ie/our-impact/News/news-item/fiscal-monitor-for-december-2025-published | Irish 2025 corporation tax receipts excluding Apple (freshness flag) | Not shown |
| Government of Ireland, First annual transfer of 0.8% of GDP into Future Ireland Fund | https://www.gov.ie/en/department-of-finance/press-releases/first-annual-transfer-of-08-of-gdp-into-future-ireland-fund/ | Ireland's two sovereign wealth funds | 22 October 2024 |
| PwC Netherlands, Draft bill introducing conditional source tax on dividend payments | https://pwc.nl/en/insights-and-publications/tax-news/enterprises/draft-bill-introducing-conditional-source-tax-on-dividend-payments.html | Dutch conditional withholding tax dates — secondary | 29 March 2021 |
| Homburger, Swiss Tax Reform — Passed by the People's referendum | https://homburger.ch/en/insights/swiss-tax-reform-passed-by-the-peoples-referendum | Abolition of Swiss cantonal regimes and patent box from 2020 — secondary | Not shown |
| Baker McKenzie, Italy: Government intends to increase again the flat tax on foreign-sourced income for new residents | https://insightplus.bakermckenzie.com/bm/tax/italy-government-intends-to-increase-again-the-flat-tax-on-foreign-sourced-income-for-new-residents | History of Italy's flat tax and grandfathering — secondary | Not shown |
| Outbound Investment, Italy Officially Raises Its Flat Tax to €300,000 for New Residents | https://outboundinvestment.com/italy-officially-raises-its-flat-tax-to-e300000-for-new-residents/ | Current €300,000 flat tax under the 2026 Budget Law — secondary | Not shown |
| Cuatrecasas, End of NHR regime — 2024 State Budget Law approved | https://www.cuatrecasas.com/en/portugal/tax/art/end-of-nhr-regime-2024-state-budget-law-approved-1 | Closure of Portugal's NHR regime and new incentive — secondary | December 7, 2023 |
| ACCA, Non-dom tax regime abolished | https://www.accaglobal.com/gb/en/technical-activities/technical-resources-search/2024/October/Non-dom-tax-regime-abolished.html | End of the UK non-dom regime on 6 April 2025 — secondary | Not shown |
| Boletín Oficial del Estado, Ley Orgánica 1/2025 | https://www.boe.es/buscar/act.php?id=BOE-A-2025-76 | End of Spain's golden visa | Not shown |
| Al Jazeera, Cyprus abolishes citizenship through investment programme | https://www.aljazeera.com/news/2020/10/13/cyprus-abolishes-citizenship-through-investment-programme | Closure of Cyprus investor citizenship in 2020 — secondary | 13 October 2020 |
| Court of Justice of the EU, Case C-181/23 Commission v Malta (judgment documents) | https://curia.europa.eu/juris/documents.jsf?num=C-181/23 | Ruling that Malta's investor citizenship scheme breaches EU law | Not shown |
| Court of Justice of the EU, press release on Case C-181/23 | https://infocuria.curia.europa.eu/tabs/affair?sort=AFF_NUM-DESC&searchTerm=%2522C%252D181%252F23%2522&publishedId=C-181%2F23 | Date and summary of the Malta judgment | 29 April 2025 |
| Mayer Brown (via vLex), OECD Pillar Two Side-by-Side System and New Safe Harbors | https://vlex.com/vid/oecd-pillar-two-side-1102951649 | Implementation of the U.S.-parented group exemption (freshness flag) — secondary | 20 January 2026 |
| Baker McKenzie, Pillar Two Side-by-Side Package Released | https://www.bakermckenzie.com/en/insight/publications/2026/01/pillar-two-side-by-side-package-released | Side-by-side safe harbor timing and continued QDMTT application — secondary | Not shown |
| OECD/Global Forum, Jurisdictions committed to implement the CARF | https://web-archive-storage.oecd.org/aemint-web-archive-prod/web-archive/c8/c84b4af3884e1acd4f5adfdeac958eb0098d421347c25e756fbc963a39135ab9.pdf | CARF first exchanges in 2027 and 2028 | Last update 17 June 2025 |
| OECD Global Forum, Jurisdictions committed to implement the Crypto-Asset Reporting Framework | https://www.oecd.org/content/dam/oecd/en/networks/global-forum-tax-transparency/commitments-carf.pdf | CARF first exchanges in 2027, 2028 and 2029; United States in 2029 | September 14, 2026 |
| ICIJ, Pandora Papers: U.S. trusts and South Dakota | https://www.icij.org/investigations/pandora-papers/us-trusts-offshore-south-dakota-tax-havens/ | Pandora Papers findings on South Dakota trusts | Not shown |
| KELOLAND News, SD regulator, trust lawyer fire back at Pandora Papers | https://digital-release.keloland.com/news/capitol-news-bureau/sd-regulator-trust-lawyer-fire-back-at-pandora-papers/amp/ | South Dakota trust assets of $500–607 billion — secondary | Not shown |
| Kelley Drye, FinCEN Exempts Domestic Reporting Companies and Persons from CTA Reporting Requirements | https://www.kelleydrye.com/viewpoints/client-advisories/fincen-exempts-domestic-reporting-companies-and-persons-from-cta-reporting-requirements-2 | March 2025 Corporate Transparency Act exemption — secondary | Not shown |
A note on scope: this article is general information, not tax or legal advice. Whether a given structure is still effective, or lawful, for your own situation depends on facts this overview does not cover. Consult a qualified professional before acting on it.