Key takeaways
- When official and market exchange rates differ, the IRS generally wants the free market rate, not the official one. Section 988 regulations say the spot rate is "generally... the free market rate" when the two differ — but the same rule can't be used to arbitrage a cheap official rate for personal gain.
- Blocked income can be deferred, but only through a specific election — not by simply not reporting it. You attach a second Form 1040 labeled "Report of Deferrable Foreign Income, pursuant to Rev. Rul. 74-351," and switching the method later requires IRS permission on Form 3115.
- A currency devaluation can create a taxable dollar gain even when you repaid exactly what you borrowed, or tripled your money locally. Repaying a local-currency loan after a devaluation is a separate taxable event from the underlying purchase or sale, and a loss on the loan itself can't offset a gain on a home sale.
- The FBAR applies even to a frozen or restricted account you can't actually access. FinCEN's valuation rules carve out no exemption for frozen funds — a depositor whose bank won't release dollars still has a reportable "financial interest" in them.
- The foreign tax credit uses different exchange-rate rules depending on how you pay. The rate on the day tax was actually paid for cash-basis taxpayers, versus the year's average rate for accrual-basis taxpayers — except for taxes in an "inflationary currency" (30%+ cumulative inflation over 36 months), which get the payment-date or year-end rate instead.
- None of the foreign tax credit, deduction, or exclusion machinery helps on income you already excluded. §911(d)(6) denies any credit for tax allocable to amounts excluded under the FEIE, and Form 1116 also denies any credit at all for taxes paid to section 901(j) countries.
If you are a US citizen or green card holder living in a country that restricts access to dollars, the IRS still expects you to report your worldwide income in US dollars and to pay the tax in dollars, even when your money cannot leave the local banking system. That gap raises questions most expat tax material never addresses: which exchange rate to use when the official and market rates differ, whether you can postpone tax on money that is stuck, how a devaluation changes the result on a home sale or a mortgage, how to claim credit for foreign tax paid in a collapsing currency, and how to report an account you cannot withdraw from.
This article works through each question with the applicable rules, numerical examples and primary sources. It does not describe each country's exchange rules. For which countries restrict dollar access today, see our world map of currency controls.
Why does the IRS want everything in dollars?
Under section 985 of the Internal Revenue Code, all federal income tax determinations are made in the taxpayer's "functional currency," which for an individual is the US dollar (26 U.S.C. § 985). The only exception is a qualified business unit (QBU): a separate and clearly identified unit of a trade or business that keeps separate books and records (26 U.S.C. § 989(a)). A QBU may use the currency of the economic environment in which a significant part of its activities take place, if it keeps its books in that currency. Your salary, rental apartment and savings account are not QBUs. A business run abroad with separate local books may be one; see our article on owning a company abroad.
The IRS spells out the consequence: if the dollar is your functional currency, you must immediately translate into dollars every item of income, expense and tax you receive, pay or accrue in a foreign currency, at the exchange rate prevailing when the item is received, paid or accrued. Payments of US tax must be made in dollars (IRS, Foreign currency and currency exchange rates; IRS Pub. 54). A federal appeals court rejected an American couple's attempt to measure the gain on their UK home in pounds, holding that individuals outside a QBU cannot adopt a foreign functional currency (Quijano v. United States, 93 F.3d 26 (1st Cir. 1996)).
Under currency controls this creates three problems. The translation rate may be one you could never obtain. The tax must be paid in dollars you may not have. And every exchange rate movement between two dates (buying and selling a property, borrowing and repaying a loan, accruing and paying a tax) can produce a dollar gain or loss with no counterpart in local currency.
Official rate or parallel rate: which one goes on your return?
What do the IRS and the regulations say?
The IRS rule is one sentence: if there is more than one exchange rate, use the one that most properly reflects your income (IRS, Foreign currency and currency exchange rates).
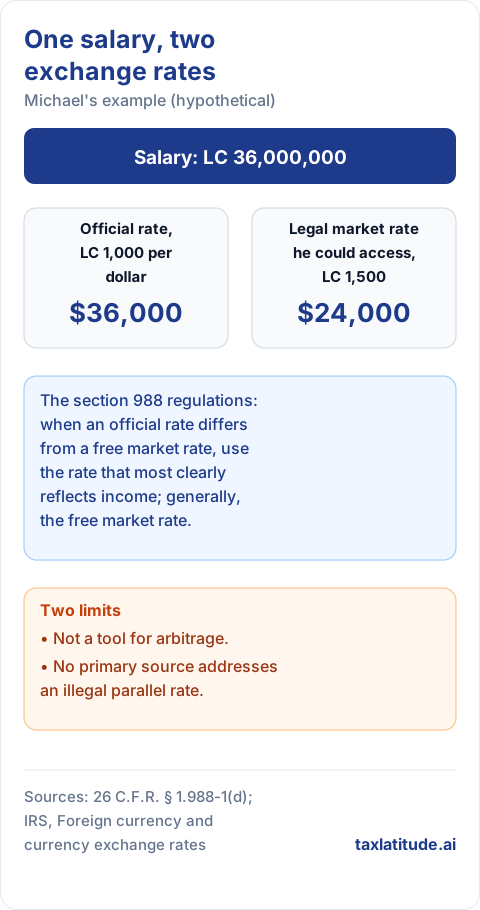
The section 988 regulations go further. They define the "spot rate" as a fair market rate of exchange available to the public under a spot contract in a free market, involving representative amounts. When a currency has an official government rate that differs from a free market rate, the spot rate is the one that most clearly reflects the taxpayer's income, and "generally, this shall be the free market rate" (26 C.F.R. § 1.988-1(d)(1) and (d)(4)). In one of the regulation's examples, a country restricts dividend remittances, the official rate is 1 to 1 and the free market rate 4 to 1, and the dividend is translated at the free market rate.
The same regulation sets two limits. A second example applies the official rate to a taxpayer who bought local currency cheaply on a secondary market to capture the spread, so the rule is not a tool for arbitrage. And the regulation speaks of a rate "available to the public" in a "free market" without saying whether an illegal street market qualifies. No primary source addresses an illegal parallel rate directly. A legal financial-market rate accessible through a bank or broker is easier to defend than an informal black-market quote.
What happens to a salary in a split-rate economy?
Michael (hypothetical) earns LC 36,000,000 from a local employer. The average official rate was LC 1,000 per dollar; the only legal market where he could buy dollars averaged LC 1,500. His salary is $36,000 at the official rate and $24,000 at the rate he could access. If he claims the foreign earned income exclusion and both figures fall under the annual exclusion amount (inflation-adjusted under section 911(b)(2)(D)), the salary itself stays tax-free either way. The rate still matters. Under section 911(f), tax on his other income is computed as if the excluded amount were added back, so a larger excluded figure pushes that other income into higher brackets. The rate also affects his housing amounts, his foreign tax credit, and any rental or investment income, which the exclusion never covers.
What do consistency and documentation require?
If inconsistent sources of spot rate quotations distort income, the IRS may determine the appropriate rate (26 C.F.R. § 1.988-1(d)(2)). So:
- Use the same rate source for income, deductible expenses and the foreign taxes on that income.
- Keep the method from year to year unless the facts change, for example when rates are unified.
- Keep, for each year, the source of each rate (central bank data, bank or broker confirmations of your actual conversions), the dates used, and a short note on why the rate most properly reflects your income.
The IRS yearly average currency exchange rates are a convenience, not an obligation. In a split-rate country, check which rate a published average reflects before using it.
Blocked income: the option to defer
What counts as blocked?
If, because of restrictions in a foreign country, your income is not readily convertible into US dollars or into other money or property readily convertible into dollars, it is "blocked" or "deferrable" income (IRS Pub. 54, Blocked Income). The test is convertibility, not convenience. Income you can convert at a poor rate generally remains convertible. Income held in a bank that will not release it, or in a currency that cannot legally be exchanged above a quota, is a stronger candidate.
You have two choices: report the income now and pay the US tax with dollars held in the United States or elsewhere, or postpone reporting it until it becomes unblocked.
How do you make the election?
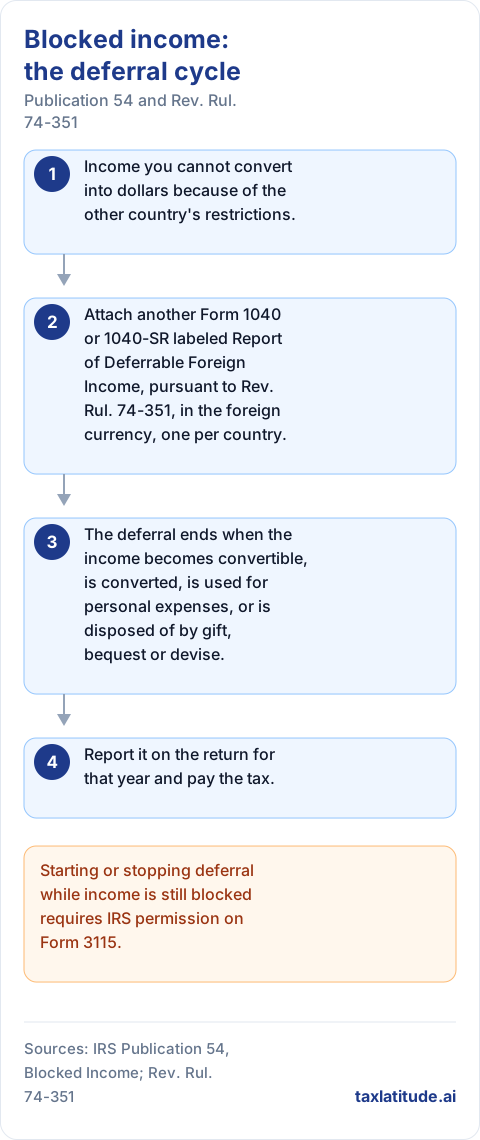
To postpone, you attach an information return to your regular return: another Form 1040 or 1040-SR labeled "Report of Deferrable Foreign Income, pursuant to Rev. Rul. 74-351." On it you:
- declare that you will include the income in taxable income for the year it becomes unblocked;
- waive any right to claim it was includible in an earlier year;
- report the income in the foreign currency in which you received it, with a separate information return for each country.
When does the deferral end?
Income becomes reportable when it becomes convertible or is converted into dollars or other money or property convertible into dollars, and also when you use it for personal expenses or dispose of it by gift, bequest or devise (IRS Pub. 54). Blocked pesos spent on your own rent or school fees stop being deferred to that extent.
Publication 54 tells you to keep checking. If income on which you have not paid tax is no longer blocked, take immediate steps to pay the tax, file a declaration or amended declaration of estimated tax, and include the income on the return for the year it became unblocked. Publication 54 does not say which exchange rate applies in that year, so document the rate you use and why.
The deferral is a method of accounting. Switching from deferral to current inclusion while income is still blocked, or starting to defer after years of not doing so, requires IRS permission on Form 3115, Application for Change in Accounting Method (IRS Pub. 54). The first year you have blocked income is the simplest moment to elect.
What is the example and the exclusion problem?
Dana (hypothetical) earns LC 30,000,000 in Year 1. LC 12,000,000 is paid into a usable account; LC 18,000,000 is credited to an account the bank will neither convert nor transfer. She reports the LC 12,000,000 and attaches a deferral return showing LC 18,000,000. In Year 3 the balance becomes convertible. If she translates it at the rate on that date, LC 2,400 in this example, $7,500 is included in Year 3.
There is a catch for wages. Section 911(b)(1)(B)(iv) excludes from "foreign earned income" amounts received after the close of the taxable year following the year the services were performed (26 U.S.C. § 911(b)). Publication 54 does not say how this rule applies to wages deferred as blocked income, so whether wages reported two years or more after the work can still be excluded is unclear. If your salary is fully covered by the exclusion in the year earned, reporting it currently may be simpler than deferring.
What is the Fulbright exception?
If at least 70 percent of a Fulbright grant is paid in nonconvertible currency, the grantee can pay the US tax attributable to the blocked income in host-country currency, through a certified statement and a deposit with the Department of State disbursing officer (IRS Pub. 54, Fulbright Grant).
Currency gains and losses under section 988
What are the rule and the personal exception?
Section 988 treats foreign currency gain or loss on a "section 988 transaction" as ordinary, computed separately from gain on the underlying asset. Section 988 transactions include becoming the obligor under a debt and disposing of nonfunctional currency, including foreign-currency bank deposits (26 U.S.C. § 988). A dollar account at a foreign bank is not nonfunctional currency for an American.
Section 988(e) excludes an individual's personal transactions, meaning any transaction except to the extent its allocable expenses qualify under section 162 (business) or 212 (investment). In addition, when an individual disposes of foreign currency in a personal transaction, exchange gain is not recognized unless it exceeds $200 on that transaction. The exclusion covers gains only.
What happens to a local-currency mortgage when the currency collapses?
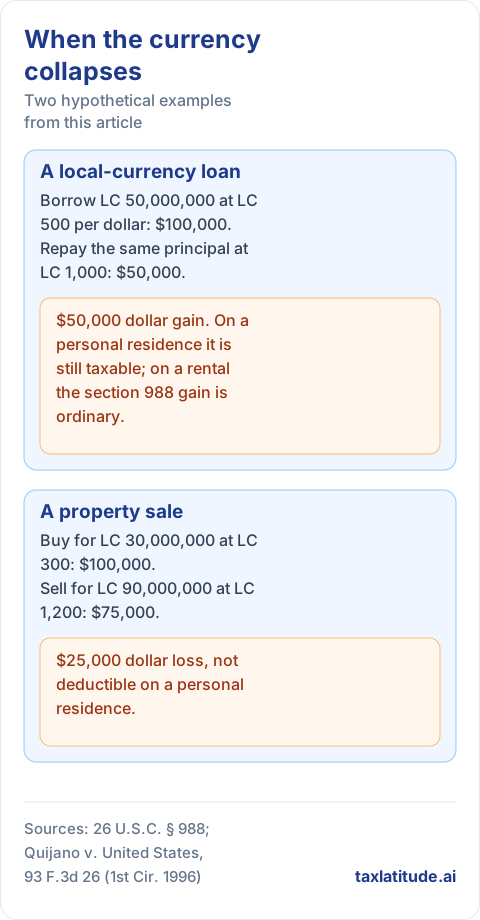
When you borrow in a currency that later loses value, you repay with fewer dollars than you borrowed. The difference is a dollar gain.
- Personal residence. Section 988 does not apply, but the gain does not escape tax. The 1986 conference report said section 988 would not apply to exchange gain or loss recognized by a US individual residing outside the United States on repayment of a foreign-currency mortgage on a principal residence, and that prior-law principles would continue to apply. Under those principles, as in Willard Helburn, Inc. v. Commissioner cited by the court, repaying a loan with cheaper foreign currency produces a taxable gain. Under Rev. Rul. 90-79, as quoted in Quijano, the loan is a separate transaction from the purchase and sale of the home, and a loss on it is not deductible under section 165(c). The First Circuit applied both points in Quijano, refusing to offset a currency loss on the loan against the gain on the house (Quijano, 93 F.3d 26).
- Rental or investment property. The debt is a section 988 transaction and the personal exception generally does not apply, so gain or loss on repayment is ordinary.
Hypothetical: you borrow LC 50,000,000 at LC 500 per dollar ($100,000). After a devaluation you repay the full principal at LC 1,000, which costs $50,000. You have a $50,000 dollar gain although you repaid exactly what you borrowed.
Repaid a local-currency loan after a devaluation and assumed there was nothing to report? The currency movement on the loan itself is a separate taxable event from the underlying purchase or sale. Ask TaxLatitude to work through your own repayment numbers →
What happens when selling a property after a devaluation?
The property's cost and selling price are translated at the rates on the purchase date and the sale date respectively, under Rev. Rul. 54-105, as applied in Quijano. Hypothetical: you buy for LC 30,000,000 at LC 300 ($100,000) and sell for LC 90,000,000 at LC 1,200 ($75,000). In local terms you tripled your money; in dollars you lost $25,000. On a personal residence that loss is not deductible. If instead the local currency strengthens, an unchanged local price can produce a taxable dollar gain.
Proceeds kept in local currency and converted later create a separate currency disposition, with a basis equal to their dollar value when received. For investment gains generally, see our article on capital gains and crypto.
Claiming the foreign tax credit in a controlled currency
How do you translate the tax you paid?
The Form 1116 instructions, which follow section 986, set these rules (Instructions for Form 1116; 26 U.S.C. § 986):
- Credit for taxes paid. Use the rate on the day the tax was paid or withheld. For a refund, use the rate when you paid.
- Credit on an accrual basis. Generally use the average rate for the year to which the tax relates, except when the tax is paid more than two years after that year ends, paid before it begins, or denominated in an inflationary currency. Those taxes are translated at the payment-date rate, and accrued but unpaid taxes in an inflationary currency at the rate on the last day of the US tax year.
- Inflationary currency means one with cumulative inflation of at least 30 percent over the 36 calendar months before year-end, based on the IMF's consumer price data.
- Election. An accrual-basis taxpayer can elect the payment-date rate instead of the average rate; the election binds later years unless the IRS consents to revocation.
You must attach a detailed explanation of how you figured any conversion.
Hypothetical: you pay LC 2,400,000 in four installments of LC 600,000 while the currency slides, at rates of LC 1,000, 1,200, 1,500 and 2,000 on the payment dates. On a cash basis the installments translate to $600, $500, $400 and $300, a credit base of $1,800.
How do consistency and blocked income interact?
Section 986 refers to exchange rates "as of the time such taxes were paid" without addressing multiple-rate countries. No primary source says whether the free market preference of the section 988 regulations also governs section 986. Use the same rate logic for the income and the tax on it, and explain it in the Form 1116 statement. If you defer blocked income but pay foreign tax on it currently, income and tax fall in different years, and the sources cited here do not say how the credit is timed in that case.
Why is there no credit on excluded income or for certain countries?
Section 911(d)(6) denies any deduction, exclusion or credit, including the foreign tax credit, to the extent properly allocable to amounts excluded under the foreign earned income exclusion (26 U.S.C. § 911(d)(6)); Publication 54 states the same rule. See our comparison of the exclusion and the foreign tax credit. The Form 1116 instructions also deny any credit for taxes paid to countries designated as supporting terrorism, countries without US diplomatic relations, and unrecognized governments (the section 901(j) category). The instructions refer to Publication 514 for the list of these countries; check it if you live in or earn income from a sanctioned country.
Frozen and restricted accounts: FBAR and Form 8938
Does the FBAR still apply?
You must file FinCEN Form 114 if you have a financial interest in, or signature authority over, foreign financial accounts whose combined value exceeds $10,000 at any time during the year (IRS Pub. 54). FinCEN's valuation instructions contain no exemption for accounts a bank or government has frozen. A depositor in Lebanon whose dollar balance the bank will not release still has a financial interest in it (country context: world map).
How do you value the account?
FinCEN's method (Reporting Maximum Account Value):
- Find each account's maximum value during the calendar year in its own currency; statements may be relied on if they fairly reflect the maximum. For a dollar account, use the largest dollar value.
- Convert a foreign-currency maximum at the Treasury reporting rate for the last day of the year (Treasury Reporting Rates of Exchange). If no Treasury rate exists, use another verifiable rate and give its source. For a country with multiple rates, use the rate that would apply if the balance were converted into dollars on the last day of the year.
Hypothetical: an account peaked at LC 40,000,000. The December 31 Treasury rate of LC 1,000 gives $40,000; the rate at which the balance could actually have been converted, LC 1,600, gives $25,000. FinCEN does not say how the Treasury-rate rule and the multiple-rate rule interact. The Treasury rate is the conservative choice; if you use the lower figure, document it. Either way the account is reportable.
Not sure which exchange rate to use for a frozen account on your FBAR? The Treasury year-end rate and the rate you could actually convert at can give very different reportable values, and FinCEN doesn't say which one governs when they conflict. Ask TaxLatitude to work through your account's actual numbers →
A frozen dollar account is reported at its largest dollar balance, even if the local market values those dollars at a discount. If you have fewer than 25 accounts and cannot determine whether the aggregate exceeded $10,000, FinCEN lets you complete the account sections and check the "amount unknown" box (item 15a). Our FBAR article covers filing and penalties.
What about Form 8938?
Form 8938 is a separate FATCA filing attached to your return; it does not replace the FBAR (Instructions for Form 8938). If your tax home is abroad and you meet a presence abroad test, you file when specified foreign financial assets exceed $200,000 on the last day of the year or $300,000 at any time (unmarried or filing separately), or $400,000 and $600,000 (filing jointly). Values are converted at the Treasury rate for purchasing dollars on the last day of the tax year, even for assets disposed of earlier; if none exists, use another publicly available rate and disclose it. You may also rely on the rate shown on an annual account statement. There is no special rule for multiple-rate countries. A foreign country's penalties for disclosure are not reasonable cause for not filing. See our pages on FATCA and the Common Reporting Standard.
Interest credited to a frozen account is still income. If it is credited in a currency that cannot be converted and cannot be accessed, it may meet the Publication 54 definition of blocked income.
What about Social Security and pensions?
US Social Security benefits are calculated in dollars and are not adjusted for exchange rate changes (SSA, Your Payments While You Are Outside the United States). Treasury regulations prohibit sending payments to residents of Cuba or North Korea (SSA Handbook § 1848), and other restrictions can apply in some countries (SSA's Payments Abroad Screening Tool gives the current position); US citizens can recover withheld payments after moving to a country where payments can be sent. Keeping benefits in a US account avoids local conversion rules. For the tax treatment, see our article on retiring abroad.
A foreign pension paid in a controlled currency follows the translation rules above and may be blocked income if it cannot be converted. It is never excludable, because section 911(b)(1)(B)(i) removes pensions and annuities from foreign earned income.
What happens when renting out, then selling, an apartment in Buenos Aires?
The figures are hypothetical, not current Argentine rates, and leave out depreciation, which a real return would include. The rates are invented to show a gap between an official and a market rate; for Argentina's current rules, see our world map.
What happens in Year 1 with rental income?
Sarah, a single US citizen living in Buenos Aires, rents out a second apartment she bought for $150,000. She collects ARS 12,000,000 in rent. The average official rate was ARS 1,000; the legal financial-market rate she could use averaged ARS 1,300.
- Rent at the official rate: $12,000.
- Rent at the rate she could obtain: $9,231.
Following the IRS rule and the regulation's preference for the free market rate, she reports $9,231 and documents her source. Her expenses (fees, repairs, local property tax) of ARS 1,800,000 become $1,385 at the same rate, for net rental income of $7,846 before depreciation. The foreign earned income exclusion does not cover rent.
She pays ARS 600,000 of Argentine tax on the rent when the accessible rate is ARS 1,350, or $444 on a cash basis, claimed on Form 1116 in the passive category subject to the limitation.
She keeps ARS 3,000,000 of rent in pesos (basis about $2,308 at ARS 1,300) and later converts at ARS 1,600, receiving $1,875. Because the pesos come from a rental whose expenses fall under section 212, the personal-transaction exception may not apply, and the $433 loss would then be an ordinary section 988 loss rather than a nondeductible personal loss. The sources cited here do not settle the point.
What happens in Year 2 with the sale?
She sells for $210,000, priced and paid in dollars as her purchase was, so there is no translation issue: the gain is $60,000 before depreciation adjustments.
- No earned income exclusion. The exclusion covers earned income only, so the full gain is taxable; see our article on capital gains and crypto for rates.
- No home sale exclusion. Section 121 requires ownership and use as a principal residence for periods totaling two years in the five years before the sale (26 U.S.C. § 121). A rental fails that test.
- Credit. Any Argentine tax on the sale is translated at the payment-date rate and claimed on Form 1116.
Change one fact: the deed says $210,000, but the buyer pays ARS 210,000,000 computed at the official rate, while Sarah can only convert at ARS 1,300. The pesos are worth $161,538 to her, and under the "most properly reflects income" logic the gain could be $11,538 rather than $60,000. No primary source addresses this case directly, so keep the bank records of the conversion and a note explaining the figure.
What happens in Year 2 with repatriation and reporting?
The $210,000 lands in her dollar account at an Argentine bank. Moving her own money home is not taxable, but the account is reportable. Its maximum is at least $210,000, so it goes on her FBAR with her peso account. For Form 8938, as a single taxpayer abroad she files only if her foreign assets exceed $200,000 at year-end or $300,000 at any time. If she wires $150,000 to a US account in November and holds nothing else abroad, her year-end total is about $60,000 and her maximum $210,000, so Form 8938 is not required. The FBAR still is.
Common mistakes
- Using the official rate by default when you could only convert at a weaker one.
- Translating income, expenses and foreign tax with different rate sources.
- Spending blocked funds while treating them as deferred.
- Starting or stopping deferral without Form 3115.
- Netting a mortgage currency loss against a home sale gain, or forgetting the taxable gain when a devaluation shrinks a local loan.
- Claiming a foreign tax credit on excluded income.
- Skipping the FBAR because the account is frozen, or using IRS yearly averages instead of the year-end Treasury rate.
- Assuming Form 8938 replaces the FBAR.
Checklist before you file
- List every foreign account, frozen ones included, with its maximum balance in its own currency, and convert at the December 31 Treasury rate (or a sourced verifiable rate).
- Test Form 8938 against the thresholds for taxpayers living abroad.
- For each currency, choose the rate that most properly reflects your income, apply it to income, expenses and taxes, and keep the evidence.
- Decide whether any income was truly blocked and, if so, whether to report it or attach a Rev. Rul. 74-351 return per country in the foreign currency.
- Check whether prior deferred amounts became convertible, were converted, or were spent.
- Compute the dollar gain or loss on any local-currency loan principal repaid.
- Translate property cost at the purchase-date rate and proceeds at the sale-date rate.
- Translate foreign taxes on the correct basis, attach the conversion explanation, and exclude taxes allocable to excluded income or paid to section 901(j) countries.
How can you get help with your own situation?
Every case turns on details: which country, which years, which accounts, whether the money is still stuck. You can put your exact situation to TaxLatitude, which answers from the Internal Revenue Code, IRS guidance and the relevant tax treaty, cites each source and lists what it could not confirm. For example:
"I'm a US citizen in Lagos. Part of my 2025 salary is still sitting in naira because my bank limits dollar purchases. Can I defer reporting it, and which exchange rate should I use for the part I report?"
A note on scope: this article is general information, not tax, legal or financial advice. Rules change and every situation is different, so check the cited sources and, for any filing decision, consult a qualified tax professional.
Frequently asked questions
Which exchange rate do I use on my US tax return if there's an official rate and a market rate?
Use whichever rate most properly reflects your income, which the IRS and the section 988 regulations say will generally be the free market rate when a country has both an official government rate and a free market rate. The regulations define the "spot rate" as a fair market rate available to the public under a spot contract in a free market, involving representative amounts. In one of the regulation's own examples, a country restricts dividend remittances with an official rate of 1 to 1 and a free market rate of 4 to 1, and the dividend is translated at the free market rate. This is not a tool for arbitrage: a separate example applies the official rate to a taxpayer who bought local currency cheaply on a secondary market to capture the spread.
What is "blocked income" for US tax purposes?
Income is "blocked" or "deferrable" when restrictions in a foreign country keep it from being readily convertible into US dollars or into other money or property readily convertible into dollars. The test is convertibility, not convenience: income you can convert at a poor rate generally still counts as convertible, while income held in a bank that will not release it, or in a currency that cannot legally be exchanged above a quota, is a stronger candidate.
Can I postpone paying US tax on blocked foreign income?
Yes. You can either report the income now and pay the US tax with dollars held in the United States or elsewhere, or postpone reporting it until it becomes unblocked. To postpone, you attach a second Form 1040 or 1040-SR as an information return, labeled "Report of Deferrable Foreign Income, pursuant to Rev. Rul. 74-351," on which you declare that you will include the income in taxable income for the year it becomes unblocked, waive any right to claim it was includible in an earlier year, and report it in the foreign currency received, with a separate information return for each country.
When does deferred blocked income become taxable?
It becomes reportable when it becomes convertible, or is actually converted into dollars or other convertible money or property, and also as soon as you use it for personal expenses or dispose of it by gift, bequest or devise. Blocked foreign currency spent on your own rent or school fees stops being deferred to that extent.
Do I still have to file the FBAR if my foreign account is frozen or restricted?
Yes. You must file FinCEN Form 114 if you have a financial interest in, or signature authority over, foreign financial accounts whose combined value exceeds $10,000 at any time during the year, and FinCEN's valuation instructions contain no exemption for accounts a bank or government has frozen. Someone whose dollar balance a bank will not release still has a financial interest in it for FBAR purposes.
How do I convert foreign tax paid in a controlled or inflationary currency for the foreign tax credit?
The Form 1116 instructions, following section 986, set the rate depending on how you claim the credit. For tax actually paid or withheld, use the rate on the day it was paid (or, for a refund, the rate when you paid). On an accrual basis, generally use the average rate for the year the tax relates to, except when the tax is paid more than two years after that year ends, paid before it begins, or denominated in an inflationary currency, a currency with cumulative inflation of at least 30 percent over the 36 calendar months before year-end based on IMF data; those taxes are translated at the payment-date rate, or, if accrued but unpaid, at the rate on the last day of the US tax year.
Sources
Primary sources (accessed October 29, 2026)
- IRS Publication 54 (Rev. December 2025): foreign currency, blocked income and Rev. Rul. 74-351, Form 3115, Fulbright grants, FBAR, Form 8938, excluded income
- IRS, Foreign currency and currency exchange rates: functional currency, translation date, multiple exchange rates, payment in dollars
- IRS, Yearly average currency exchange rates
- 26 U.S.C. § 985, Functional currency
- 26 U.S.C. § 986, Determination of foreign taxes
- 26 U.S.C. § 988, Treatment of certain foreign currency transactions: ordinary treatment, personal transactions, $200 exclusion
- 26 U.S.C. § 989, Other definitions and special rules: qualified business unit
- 26 U.S.C. § 911: foreign earned income, denial of double benefits
- 26 U.S.C. § 121 (2023 edition, govinfo.gov): principal residence exclusion
- 26 C.F.R. § 1.988-1: spot rate, consistency, official versus free market rate
- IRS, Instructions for Form 1116 (2025): currency conversion, inflationary currency, payment-date election, section 901(j) countries
- IRS, Instructions for Form 8938: thresholds abroad, currency conversion
- FinCEN, Reporting Maximum Account Value: FBAR valuation, multiple exchange rates, amount unknown box
- Bureau of the Fiscal Service, Treasury Reporting Rates of Exchange
- Quijano v. United States, 93 F.3d 26 (1st Cir. 1996): functional currency of individuals, Rev. Rul. 90-79, Rev. Rul. 54-105, 1986 conference report
- SSA, Your Payments While You Are Outside the United States
- SSA Handbook § 1848, What are the restricted countries?
A note on method: the rules in this article were checked on October 29, 2026 against sections 985 to 989 of the Internal Revenue Code and the section 988 regulations, IRS Publication 54, the instructions for Forms 1116 and 8938, FinCEN's guidance on account values, and the First Circuit's opinion in Quijano. The people and exchange rates in the examples are hypothetical. Where only a secondary source was available, the text labels it; where no official source settles a question, the text says so. Paraphrases are ours, so check the cited text before you rely on it.