Key takeaways
- You remain a US person wherever you go — and you carry US sanctions with you, which your non-American neighbors don't. OFAC sanctions bind US citizens and green card holders regardless of where they live; a German or Canadian neighbor in the same country is not subject to them.
- Blocked or inconvertible money is still taxable money. An American whose pesos or rupees are stuck still has to report the income, the gain and the account on a US return, though relief exists in some cases as "blocked income."
- Your residency status abroad often decides which rules apply — and the same American can be classified differently depending on the transaction. A US citizen living in Buenos Aires is a resident under Argentine rules; selling an inherited flat from Chicago, the same person is a non-resident.
- How money entered a country can determine whether it can ever leave. Thailand and Morocco both reward buyers who brought foreign currency in through the banking system and kept the transfer certificate.
- 2026 brought both directions at once. Russia tightened (transfer ban extended through December 7, 2026) and Iran sanctions tightened sharply (key general licenses suspended August 2026), even as Argentina and South Africa kept loosening.
- A frozen or restricted account still counts for FBAR purposes, and many countries now report account information to the IRS under FATCA or to their own tax authority under the Common Reporting Standard.
More than three decades after the great wave of financial liberalization, a large part of the world still rations access to foreign currency. Governments cap how many dollars a resident may buy, force exporters to convert their earnings, screen transfers abroad, or freeze the accounts of foreigners from countries they consider hostile. Several large economies, from Egypt to Argentina, have loosened their grip since 2023. Others, Russia first among them, have tightened.
For an American abroad, these rules are not an abstraction. They decide whether you can wire the proceeds of an apartment sale home, whether your pension lands in a local account you can actually use, how much cash you can carry through the airport, and what happens to your savings the day you decide to leave. This article maps the world's currency controls for U.S. citizens and green card holders who live, work, invest or own property in a controlled country.
What is a currency control, and why does it hit Americans differently?
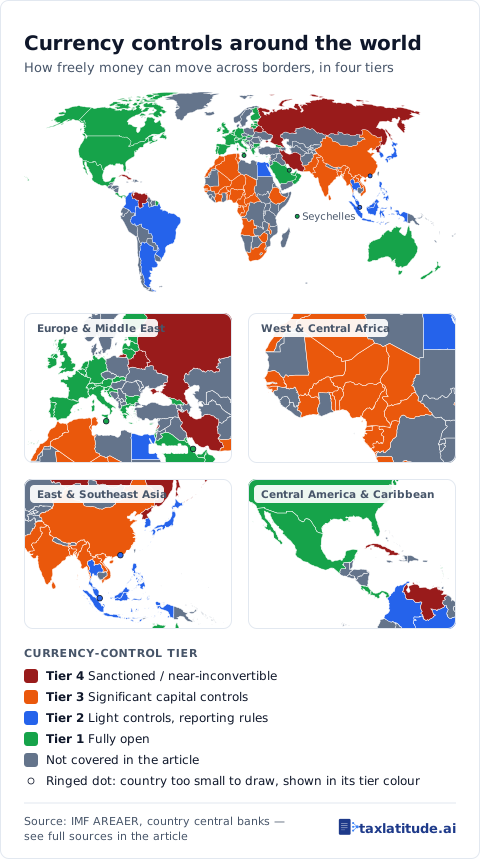
A currency control is any rule a government uses to limit the buying, selling or transfer of foreign money. There is no clean line between open and closed countries. At the light end are reporting requirements and annual caps for residents. At the heavy end, the local currency cannot be converted at all, the state sets several official rates, and a parallel market thrives alongside. In between, many countries leave current payments such as imports, travel and family support largely free, but restrict capital movements such as investing abroad, buying foreign securities or repatriating the proceeds of an asset sale.
The International Monetary Fund documents these regimes country by country in its Annual Report on Exchange Arrangements and Exchange Restrictions (AREAER), the standard reference for what each member country restricts. The United States, the eurozone, the United Kingdom, Switzerland, Japan, Canada, Singapore, Hong Kong and the Gulf states generally let money move freely, apart from sanctions and anti-money-laundering rules.
Three things make the experience different for an American than for a local resident.
You are taxed on worldwide income regardless of where the money is stuck. An American whose pesos are stuck still reports the income, the gain and the account on a U.S. return. Blocked money does not stop being taxable money, although relief exists in some cases (see the section on your U.S. return below).
Your residency status abroad often decides which rules apply. Most control regimes distinguish residents from non-residents, and the same American can be either. A U.S. citizen living in Buenos Aires is a resident individual under Argentine rules; the same citizen selling an inherited flat from Chicago is a non-resident. In India, a U.S. citizen of Indian origin may fall under rules for persons of Indian origin, while an American with no Indian background falls under rules for foreign nationals. Before you read any limit, ask which category you are in.
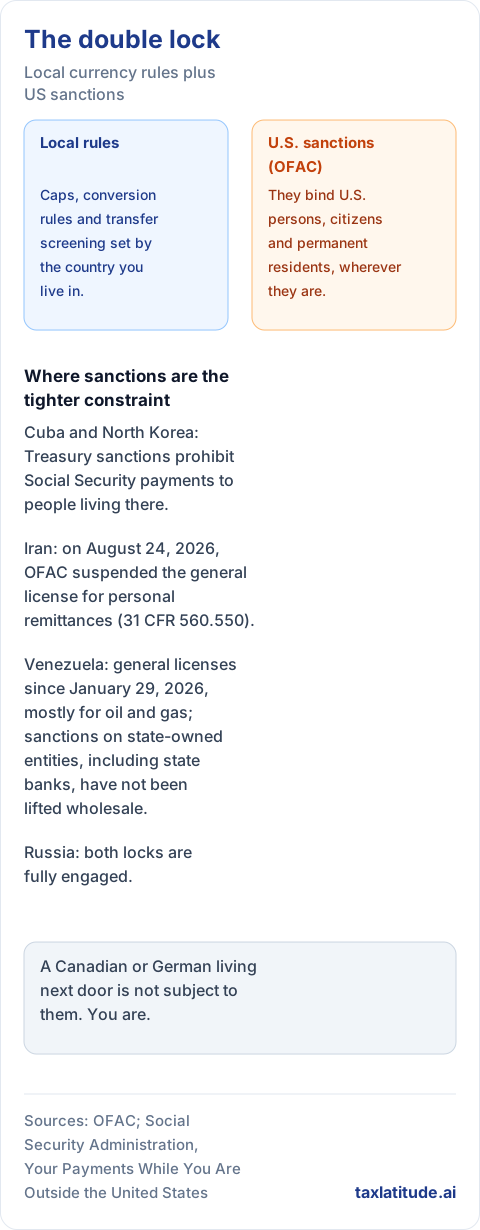
You carry U.S. sanctions with you. Sanctions administered by the Treasury Department's Office of Foreign Assets Control (OFAC) bind "U.S. persons," a term that covers U.S. citizens and permanent residents wherever they are. A Canadian or German living next door is not subject to them. You are.
How do local rules and U.S. sanctions combine?
For a handful of countries, U.S. sanctions are the tighter constraint, and they can prohibit transactions the local government would allow.
Cuba and North Korea
Treasury sanctions prohibit Social Security payments to people living in Cuba or North Korea. The Social Security Administration's guide to payments outside the United States (April 2026 edition) states that U.S. citizens living in either country can receive the withheld payments once they move to a country where payments can be sent; non-citizens lose the payments for those months permanently.
For Cuba, OFAC's Cuban Assets Control Regulations govern what a U.S. person may send or spend. In June 2022 OFAC removed the $1,000 quarterly cap on family remittances and restored authorization for donative remittances to Cubans who are not prohibited officials or their close relatives. Check OFAC's current Cuba guidance before sending money, because the program has been tightened and loosened several times.
North Korea is subject to comprehensive U.S. sanctions, which leave almost no room for personal transactions.
Iran
Iran is the clearest example of U.S. rules tightening in 2026. On August 24, 2026, OFAC suspended indefinitely several general licenses under the Iranian Transactions and Sanctions Regulations, including 31 CFR 560.550, which had authorized certain noncommercial, personal remittances to or from Iran. A wind-down license (General License BB) ran until September 8, 2026. After that date, family remittances that previously fell under the general license need a specific license from OFAC. A second round of suspensions on September 8, 2026 covered licenses on overflight payments, aircraft safety, and bunkering and emergency repairs.
The suspension notice does not list 31 CFR 560.543, the general license that has allowed U.S. persons to sell certain real and personal property in Iran (property acquired before becoming a U.S. person, or inherited from persons in Iran) and transfer the proceeds. OFAC can still change it, so confirm its status on OFAC's Iran sanctions page before any sale. Iranian-American families with inherited property should treat every transfer as a sanctions question first and an exchange control question second.
Venezuela
Venezuela moved in the opposite direction. Following the January 2026 political transition, OFAC issued a series of general licenses starting January 29, 2026, mostly opening the oil and gas sector to U.S. companies (summarized by a secondary source). The underlying sanctions on the Government of Venezuela and state-owned entities, including state banks, have not been lifted wholesale. An American with a pension or bank account in Venezuela should check whether the bank is government-owned before moving money through it.
Russia
Russia is the case where both locks are fully engaged. On the U.S. side, Executive Order 14071 prohibits U.S. persons from providing certain services to persons located in Russia; OFAC's FAQ 1058 explains who counts as located there, and a general license authorizes accounting and tax preparation services for U.S. individuals living in Russia, so that they can still file U.S. returns. Another general license, described in OFAC FAQ 1028, allows personal remittances of U.S. dollar banknotes to individuals in Russia despite the broader banknote export ban. See our Russia guide.
Which countries have currency controls?
For each country: what is limited, what it means for an American who lives or owns property there, and where to read more.
Asia
China. The yuan has never been fully convertible. Under rules issued by the State Administration of Foreign Exchange, each domestic individual has an annual quota of USD 50,000 for buying foreign currency and the same amount for selling it, with documentation required above the quota. For foreign individuals, banks apply the USD 50,000 quota to converting foreign currency into yuan, while purchases of foreign currency require proof of the source of funds (per a major bank's published guidance, secondary source). For an American working in China, the answer is paperwork: keep payslips and tax certificates, because they are what allows you to convert yuan savings back into dollars when you leave. Cash is capped separately: according to China's immigration authority, travelers may carry no more than RMB 20,000 in cash, and any amount above that, or foreign cash above USD 5,000, must be declared to customs. See our China guide.
India. The rupee is convertible for trade and travel but the capital account is partly closed. Resident individuals may send up to USD 250,000 per financial year (April to March) under the Reserve Bank of India's Liberalised Remittance Scheme. For Americans of Indian origin who live in the United States, the more relevant rule is the RBI's Master Direction on Remittance of Assets, updated June 29, 2026: non-resident Indians and persons of Indian origin may remit up to USD 1 million per financial year from their non-resident ordinary (NRO) accounts, including the proceeds of selling inherited property, with larger amounts requiring RBI approval. The same direction contains separate, narrower rules for foreign nationals of non-Indian origin, such as retirees from employment in India or heirs. Cash: RBI regulations require a declaration on arrival in India when foreign currency notes exceed USD 5,000 or total foreign exchange exceeds USD 10,000, and limit rupee notes to INR 25,000. See our India guide.
Thailand. Thailand's controls are light but they matter for property. A foreigner buying a condominium in their own name must transfer the purchase money from abroad in foreign currency, and for transfers of USD 50,000 or more the receiving bank issues a Foreign Currency Transaction Form as proof. The Land Department asks for these certificates before it registers the unit in your name. Keep them afterward too: they are the record of the foreign money you brought in, and you will want that record when you sell. See our Thailand guide.
Malaysia. Bank Negara Malaysia states that non-residents are free to invest in ringgit assets and to repatriate divestment proceeds, profits and income, provided repatriation is made in foreign currency. Residents follow different rules, so whether a long-stay American counts as a resident or a non-resident under Bank Negara's definitions decides which rules apply. See our Malaysia guide.
Elsewhere in Asia. Vietnam, Laos, Bangladesh, Pakistan, Sri Lanka and Myanmar maintain tighter regimes, often reinforced during recent balance-of-payments crises; Myanmar has tightly policed foreign currency since its 2021 coup. Hong Kong, Singapore, Japan, South Korea, the Philippines and Indonesia are comparatively open for individuals, although each has its own reporting rules; see our guides for Hong Kong, Singapore, Japan, South Korea, the Philippines and Indonesia.
Middle East and North Africa
Egypt. On March 6, 2024, the Central Bank of Egypt let the exchange rate be set by market forces and raised its key rate by 600 basis points, citing foreign exchange shortages and a parallel market (copy of the CBE release hosted by a secondary source). The CBE said the move would unify the exchange rate by closing the spread between the official and parallel markets. For Americans, the aim was to end the gap that had made converting dollars through official channels costly. Cash rules remain: travelers may carry no more than EGP 5,000 in Egyptian banknotes, according to local press (secondary source).
Morocco. The dirham is not freely convertible, but Morocco has been liberalizing gradually. The Office des Changes publishes its rules in a General Instruction on Foreign Exchange Operations, revised regularly. For residents, the personal travel allowance starts at MAD 100,000 per year with a supplement that brings the total to at most MAD 500,000 per person per calendar year (secondary source). For a non-resident American who buys property in Morocco, the key point is the transfer guarantee: an investment financed with foreign currency brought into Morocco through the banking system can generally be repatriated, including the capital gain, after tax. A purchase financed with dirhams earned locally may not carry the same guarantee.
Algeria and Tunisia. Neither dinar is freely convertible. Both countries limit travel allowances, prohibit exporting local banknotes and require approval for many transfers; in Algeria, the gap between the official and parallel dinar rates remains wide.
Lebanon. Lebanon never passed a formal capital control law, yet banks have restricted dollar withdrawals and transfers since 2019. These de facto controls trapped the savings of depositors, including Lebanese Americans who kept accounts there. An American with a frozen Lebanese account still has U.S. reporting obligations on it.
Iran. See the sanctions section above. U.S. rules dominate.
The Gulf. The UAE and its neighbors impose essentially no currency controls on individuals. See our UAE guide.
Sub-Saharan Africa
Nigeria. On June 14, 2023, the Central Bank of Nigeria collapsed its multiple exchange windows into a single Investors and Exporters window with a market-determined rate (as analyzed by a Nigerian law firm, secondary source). Unification eased access to dollars at the official rate; it did not remove the documentation banks require for transfers abroad.
Ethiopia. The National Bank of Ethiopia moved to a market-based exchange rate on July 29, 2024, under a new foreign exchange directive (FXD/01/2024), allowing banks to buy and sell foreign currency at negotiated rates (reported by the state news agency, secondary source). Capital outflows remain controlled, according to local business press (secondary source). An Ethiopian American who sells family property may find that the proceeds cannot leave the country in foreign currency without a specific permission.
South Africa. South Africa keeps a control regime inherited from the apartheid era, but it is now generous. The South African Reserve Bank's Exchange Control Circular No. 6/2026 doubled the single discretionary allowance to R2 million per calendar year for resident individuals aged 18 and over, on top of an R10 million foreign capital allowance that requires tax clearance. The same circular lets foreign nationals receive a travel allowance within the R2 million limit. An American treated as a South African resident for exchange control purposes can therefore move meaningful sums each year, but larger moves (such as the proceeds of a house sale) need tax clearance from the South African Revenue Service.
The CFA franc zone. The fourteen countries using the West and Central African CFA francs live with a paradox: the currency is pegged to the euro with guaranteed convertibility, yet transfers outside the zone are policed by regional rules, which Central Africa (CEMAC) tightened in a 2018 overhaul.
Elsewhere. Zimbabwe, Angola and Malawi also manage access to dollars. Seychelles is open; see our Seychelles guide.
Latin America
Argentina. On April 11, 2025, the central bank announced Phase 3 of its economic program, and Communication A 8226, effective April 14, 2025, removed the restrictions on resident individuals buying foreign currency, including the USD 200 monthly cap. The BCRA's own April 2025 exchange market report confirms that individuals may now buy foreign currency without limits of amount or purpose. For an American living in Argentina, a peso salary or rental income can again be converted on the official exchange market.
For non-residents, Communication A 8230 (April 2025) allowed non-resident investors to repatriate new investments without prior central bank approval, and a later communication removed the minimum holding period in June 2025 (per a law firm summary, secondary source). The IMF said in July 2025 that Argentina had eased most foreign exchange restrictions, not all of them. According to press coverage of the IMF staff report (secondary source), the remaining restrictions covered certain corporate debt payments, dividends from pre-2025 profits, and dollar purchases by non-resident credit card users. On April 9, 2026, Communication A 8417 relaxed limits on foreign currency cash advances (per a legal news summary, secondary source) and set new bank checks, from April 10, 2026, on individuals' transfers of dollars from local accounts to their own accounts abroad (per a law firm summary, secondary source). The IMF reached a staff-level agreement on the second program review on April 15, 2026. A word of history: Argentina already lifted its controls in late 2015 and reimposed them in 2019.
Brazil. Brazil modernized its framework with a new foreign exchange law (Law 14.286 of 2021). Travelers must file an electronic declaration (e-DBV) when carrying cash above USD 10,000 or its equivalent, and the undeclared excess above that threshold can be forfeited. See our Brazil guide.
Colombia. Colombia's regime turns on whether a transaction is an exchange operation, which must go through the regulated exchange market, or a purely domestic one. A published opinion of the bank's board secretariat addressed a U.S. citizen resident in Colombia buying rural property and concluded that buying it from another resident is a domestic transaction, not a foreign direct investment subject to registration with the bank. Residency again changes the answer. See our Colombia guide.
Venezuela and Cuba. See the sanctions section above. Venezuela has a long history of multiple official rates and a parallel market; Cuba's peso remains essentially inconvertible for ordinary purposes.
The rest of the region. Mexico, Panama and Costa Rica impose no significant currency controls on individuals. See our guides for Mexico, Panama and Costa Rica.
Russia, Eastern Europe and Central Asia
Russia. The United States is on Russia's list of unfriendly countries, and its rules for individuals from such countries remain strict. The Bank of Russia announced on June 1, 2026 that from June 8 through December 7, 2026, non-resident individuals from unfriendly countries who work in Russia may transfer abroad only the amount of their wages, while those who do not work in Russia remain banned from cross-border transfers. Transfers abroad from brokerage and trust accounts of non-residents from unfriendly countries remain suspended: on September 24, 2026, the Bank of Russia extended the suspension for another six months from October 1, 2026. Since June 1, 2026, payments to depositors from unfriendly countries above RUB 10 million per month must go to restricted type C ruble accounts (per summaries by two Russian law firms, secondary sources). For an American who sells a Moscow apartment, the proceeds may end up in a restricted account and stay in Russia. Get advice from a Russian lawyer before you sign.
Belarus and Central Asia. Belarus has adopted its own restrictions since 2022. For retirees, a separate U.S. limit matters: the Social Security Administration generally cannot send payments to persons in Azerbaijan, Belarus, Kazakhstan, Kyrgyzstan, Tajikistan, Turkmenistan or Uzbekistan, unless the beneficiary qualifies for an exception and accepts restricted payment conditions.
Georgia is open; see our Georgia guide.
Everywhere else
Within the European Union, the United Kingdom, Switzerland, Canada, Australia, New Zealand, Japan, Israel and the Gulf, the constraints an American faces are reporting and anti-money-laundering checks, not exchange controls. See our guides for France, Portugal, Spain, the UK, Canada, Australia and Israel.
Five situations where controls bite
What happens when you sell property and bring the money home?
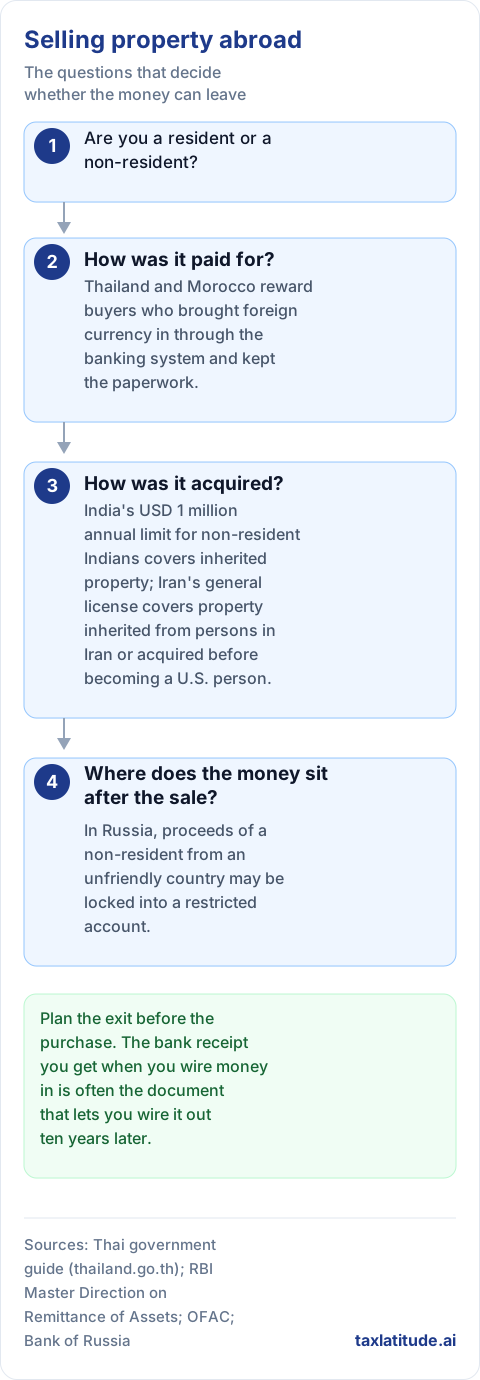
The rules typically depend on three facts: whether you are a resident or a non-resident, how the property was paid for, and how it was acquired.
- How it was paid for. Thailand and Morocco both reward buyers who brought foreign currency in through the banking system and kept the paperwork. A buyer who paid with locally earned money may find the proceeds harder to export.
- How it was acquired. India's USD 1 million annual limit for non-resident Indians covers inherited property; Iran's property-sale general license covers property inherited from persons in Iran or acquired before becoming a U.S. person.
- Where the money sits after the sale. In Russia, sale proceeds received by a non-resident from an unfriendly country may be locked into a restricted account. In Argentina, a resident can now buy dollars freely, but a non-resident should confirm which rules apply to their transaction before closing.
Plan the exit before the purchase. The bank receipt you get when you wire money in is often the document that lets you wire it out ten years later.
Planning to sell property in a country with currency controls? Whether the proceeds can actually leave the country depends on your residency status, how the property was paid for, and paperwork you may not have kept. Ask TaxLatitude what applies to your specific country and situation →
What happens when you receive a pension or Social Security?
Social Security pays in dollars and, according to the SSA, does not adjust benefits for exchange rate changes. You can have benefits deposited into a U.S. bank account wherever you live, unless a payment restriction applies, or into a foreign bank in a country with an international direct deposit agreement. In a country with currency controls, keeping the deposit in the United States is often the safer choice: the dollars stay convertible and you transfer only what you need. Check your country with the SSA's Payments Abroad Screening Tool before you move. Foreign pensions earned in a controlled country are a different problem: they may be payable only into a local account in local currency. For broader planning, see our article on retiring abroad.
What happens when you pay rent or tuition?
Inside a controlled country, paying local expenses is rarely the problem; paying across the border is. If you rent out an apartment in India and want the rent in the United States, current income such as rent can be remitted from an NRO account, but the bank will ask for tax documentation showing the tax on that income. If you live in India or South Africa, earn in local currency and pay tuition in the United States, the resident allowances described above (USD 250,000 under India's scheme, R2 million in South Africa) set the pace at which you can pay without extra approvals. In China, the USD 50,000 purchase quota applies to domestic individuals; foreigners instead document the source of their funds.
What happens when you carry cash?
Carrying cash is legal almost everywhere; failing to declare it is not. The United States requires anyone transporting more than USD 10,000 in currency or monetary instruments into or out of the country to file FinCEN Form 105. Brazil uses the same USD 10,000 threshold for its declaration. China and India are stricter: foreign cash above USD 5,000 must be declared to Chinese customs and on arrival in India, and both limit local banknotes (RMB 20,000 and INR 25,000). Egypt caps Egyptian banknotes at EGP 5,000.
What happens when you leave the country for good?
Common traps include accounts that convert automatically to a restricted non-resident status, investment accounts that cannot be closed into foreign currency, and pensions that can only be paid locally. Before departure, convert and transfer what you can while you still qualify as a resident, collect bank certificates and tax receipts for every inward transfer, and find out whether your accounts will be reclassified. In India, for example, the resident savings accounts of someone who becomes a non-resident are converted to NRO accounts.
Leaving a country with currency controls for good? Accounts can automatically reclassify to non-resident status, and some pensions only ever pay locally — worth checking before you go, not after. Ask TaxLatitude what to sort out before you leave →
Are currency controls easing or getting stricter?
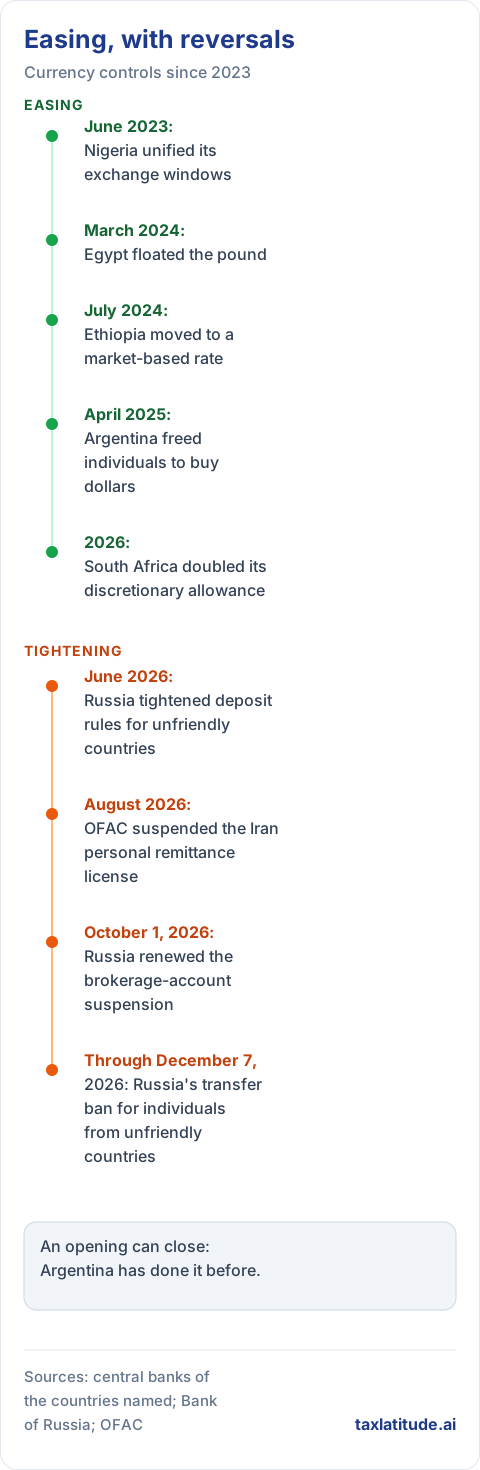
The broad trend since 2023 has been loosening. Nigeria unified its exchange windows in June 2023, Egypt floated the pound in March 2024, Ethiopia moved to a market-based rate in July 2024, Argentina freed individuals in April 2025, and South Africa doubled its discretionary allowance in 2026.
The counter-trend is driven by geopolitics. Russia extended its transfer ban for individuals from unfriendly countries through December 7, 2026, tightened its deposit rules in June 2026, and renewed the brokerage-account suspension from October 1, 2026. On the U.S. side, OFAC suspended the general license for personal remittances to and from Iran in August 2026, while easing parts of the Venezuela program earlier in the year. An opening can close: Argentina has done it before.
What does this mean for your U.S. tax return?
When a country has an official and a parallel rate, the rate you use to translate income matters; income you cannot convert or move may qualify for deferral as blocked income; a frozen or restricted account still counts for FBAR purposes; and foreign taxes paid on blocked income raise their own credit questions. We cover these points in detail, with a worked example of an apartment in Buenos Aires, in U.S. taxes under currency controls. For account reporting, see our FBAR guide and our guide to FATCA. Note too that banks in many controlled countries report account information to tax authorities under the Common Reporting Standard, and to the IRS under FATCA. For gains on property or securities sold in a controlled country, see capital gains and crypto; if you own a local company, see owning a company abroad.
Common mistakes
- Assuming the rules for locals apply to you. Your residency status, your origin and your U.S. person status can each put you in a different category.
- Buying property with local money and no paper trail. In countries with transfer guarantees, the guarantee usually follows foreign currency brought in through a bank, not cash or local earnings.
- Using the parallel market. It may offer a better rate, but in most controlled countries it is illegal, and the paperwork it leaves (none) can block you from repatriating the money later.
- Splitting cash to stay under a threshold. Structuring transfers or cash to avoid a reporting limit is itself an offense in the United States and in many other countries.
- Forgetting U.S. sanctions. A transaction can be perfectly legal under Iranian, Russian or Cuban law and still violate OFAC rules for a U.S. person.
- Ignoring a frozen account. Restricted accounts in Lebanon, Russia or elsewhere still belong on your FBAR and, where thresholds are met, on Form 8938.
- Waiting until the last week. Repatriation approvals, tax clearances and bank certificates take time.
Before you go: a checklist
- Look up the country's chapter in the IMF's AREAER and the central bank's current rules for non-residents and foreign nationals.
- Check OFAC's sanctions programs for the country, and whether any general license covers what you plan to do.
- Run the SSA's Payments Abroad Screening Tool if you receive or will receive Social Security.
- Decide whether to keep pension and Social Security deposits in a U.S. account.
- Bring investment money in through a bank, in foreign currency, and keep every transfer certificate and form.
- Learn the cash declaration thresholds for the country and for the United States (USD 10,000 on FinCEN Form 105).
- Ask which account types (resident, non-resident, convertible) you may open, and how your accounts will be treated if you become a non-resident.
- Plan the exit: how you would sell, convert and transfer your assets if you left in a year.
- Confirm your U.S. reporting obligations (FBAR, Form 8938) for every foreign account, including restricted ones.
A note on scope: this article is general information, not tax, legal or financial advice. Currency controls and sanctions change often, sometimes overnight, and the figures above reflect official sources as of October 29, 2026. Before moving money in or out of a controlled country, confirm the current rules with the central bank, OFAC and a qualified adviser who knows your situation.
Frequently asked questions
What are currency controls?
A currency control is any rule a government uses to limit the buying, selling or transfer of foreign money. The spectrum runs from light reporting requirements and annual caps at one end to full inconvertibility, multiple official exchange rates and a parallel market at the other. Many countries leave everyday payments such as imports, travel and family support largely free while restricting capital movements such as investing abroad or repatriating the proceeds of an asset sale.
Which currencies or countries have the strictest controls?
Per the IMF's AREAER and the country sources cited above, the most restricted currencies belong to countries that are sanctioned or near-inconvertible: North Korea, Cuba, Iran, Venezuela, Russia, Belarus and Lebanon. A second tier of significant capital controls covers countries including China, India, Myanmar and Algeria. At the open end, the United States, the eurozone, the United Kingdom, Switzerland, Japan, Canada, Singapore, Hong Kong and the Gulf states generally let money move freely, apart from sanctions and anti-money-laundering rules.
Does the United States have currency controls?
No, not in the sense of capital or exchange controls. The U.S. lets money move freely apart from sanctions and anti-money-laundering rules. The one limit that applies at the border is a reporting threshold, not a cap: anyone transporting more than USD 10,000 in currency or monetary instruments into or out of the country must file FinCEN Form 105.
How much cash can I carry across a border?
It depends on the country, and carrying cash is legal almost everywhere — failing to declare it is not. The United States and Brazil both use a USD 10,000 threshold for a mandatory declaration. China requires foreign cash above USD 5,000 to be declared to customs and caps local banknotes at RMB 20,000. India requires a declaration when foreign currency notes exceed USD 5,000 or total foreign exchange exceeds USD 10,000, and caps rupee notes at INR 25,000. Egypt caps Egyptian banknotes at EGP 5,000.
If my money is blocked abroad, do I still owe U.S. tax on it?
Yes. An American whose funds are stuck in a controlled country still reports the income, the gain and the account on a U.S. return — blocked money does not stop being taxable money, although relief can exist in some cases. The restricted account itself still has to be reported where FBAR or Form 8938 thresholds are met. See our detailed article on U.S. taxes under currency controls for a worked example.
Can U.S. sanctions restrict money transfers even where the local government allows them?
Yes. OFAC sanctions bind "U.S. persons" — a term covering U.S. citizens and permanent residents wherever they are — regardless of what the local government permits. For a handful of countries, including Cuba, North Korea, Iran, Venezuela and Russia, U.S. sanctions are the tighter constraint, and they can prohibit a transaction the local government would otherwise allow.
Sources
Primary sources (accessed October 29, 2026)
- International Monetary Fund, Annual Report on Exchange Arrangements and Exchange Restrictions 2023, December 19, 2024
- International Monetary Fund, Press Release No. 25/272, first review of Argentina's Extended Fund Facility, July 31, 2025
- International Monetary Fund, Press Release No. 26/120, staff-level agreement on Argentina's second review, April 15, 2026
- U.S. Treasury, OFAC, Suspension of Certain Iranian Transactions and Sanctions Regulations General Licenses, updated September 8, 2026
- Federal Register, OFAC rule staying 31 CFR 560.544, 560.550 and 560.554, effective August 24, 2026
- U.S. Treasury, OFAC, Cuba-related FAQs added June 8, 2022
- U.S. Treasury, OFAC, FAQ 1058, persons located in the Russian Federation
- U.S. Treasury, OFAC, FAQ 1028, U.S. dollar banknote remittances to Russia
- U.S. Treasury, OFAC, General license authorizing certain accounting services to U.S. individuals located in the Russian Federation
- Social Security Administration, Your Payments While You Are Outside the United States, Publication No. 05-10137, April 2026
- Social Security Administration, Payments Abroad Screening Tool
- FinCEN, Form 105, Report of International Transportation of Currency or Monetary Instruments
- State Administration of Foreign Exchange (China), Q&A on the Detailed Rules for Individual Foreign Exchange Administration
- National Immigration Administration (China), Welcome to China, currency rules for travelers
- Reserve Bank of India, Master Direction, Liberalised Remittance Scheme
- Reserve Bank of India, Master Direction, Remittance of Assets, updated June 29, 2026
- Reserve Bank of India, Foreign Exchange Management (Export and Import of Currency) Regulations, 2015, as amended
- Government of Thailand, Procedure for accepting foreign money transfers to buy assets in Thailand
- Bank Negara Malaysia, Investing in Malaysia, rules for non-residents
- South African Reserve Bank, Exchange Control Circular No. 6/2026
- Bank of Russia, Restrictions on cross-border funds transfers for individuals from unfriendly countries maintained, June 1, 2026
- Bank of Russia, Restrictions on cross-border transfers from brokerage and trust management accounts retained, September 24, 2026
- Banco Central de la República Argentina, Inicio de la Fase 3 del Programa Económico, April 11, 2025
- Banco Central de la República Argentina, Comunicación A 8226
- Banco Central de la República Argentina, Comunicación A 8230
- Banco Central de la República Argentina, Evolución del Mercado de Cambios y Balance Cambiario, April 2025
- Government of Brazil, Declarar bens para viagem internacional (e-DBV)
- Banco de la República (Colombia), Concept JDS-25888 of the Board Secretariat
Secondary sources
- HSBC China, Foreign exchange settlement and purchase (secondary source)
- Central Bank of Egypt, Special MPC press release, March 6, 2024, as hosted by Amwal Al Ghad (secondary source)
- Egypt Independent, CBE: local currency limit for passengers remains at LE5,000 (secondary source)
- Aujourd'hui le Maroc, IGOC 2026 travel allowance (secondary source)
- Templars, Significant Progress Made Towards Unifying FX Markets in Nigeria, June 2023 (secondary source)
- Ethiopian News Agency, NBE announces foreign exchange reform, July 29, 2024 (secondary source)
- Addis Fortune, Ethiopia lifts foreign exchange restrictions in sweeping reform, July 29, 2024 (secondary source)
- Estudio O'Farrell, BCRA eases access to the exchange market for non-residents, June 2025 (secondary source)
- Abogados.com.ar, BCRA flexibiliza controles de cambio, April 2026 (secondary source)
- Allende & Brea, BCRA eases exchange regime for exports, foreign currency transfers and financial payments, April 14, 2026 (secondary source)
- Buenos Aires Herald, IMF grants Argentina reserve waiver and cuts accumulation target, 2025 (secondary source)
- ALRUD, The Bank of Russia clarifies new rules for foreign depositors at Russian banks, 2026 (secondary source)
- Moscow Legal (mosgolaw.com), Restrictions on deposits of citizens from unfriendly countries, 2026 (secondary source)
- Winston & Strawn, United States issues significant new sanctions relief for Venezuela's oil and gas sector, February 19, 2026 (secondary source)
A note on method: each cap, date and rule in this article was checked on October 29, 2026 against the official source of the country or agency concerned, including the Bank of Russia, the Reserve Bank of India, the South African Reserve Bank, Argentina's central bank, Bank Negara Malaysia, Colombia's Banco de la República, China's foreign exchange and immigration authorities, the IMF, OFAC, FinCEN and the Social Security Administration. Where only a secondary source was available, the text labels it; where no official source settles a question, the text says so. Paraphrases are ours, so check the cited text before you rely on it.